


EN
Learn Why The Bull Case For Kemper Stock Could Change Following Return To Profitability
- Kemper Corporation reported third quarter 2026 revenue of US$1,090.6 million and net income of US$52.4 million, reversing a loss a year earlier, alongside a quarterly dividend of US$0.32 per share declared in November 2026.
- The swing to quarterly profitability came as Kemper emphasized underwriting results, reduced personal auto policy counts, shifted its business mix across states and introduced a new segmented auto product supported by a refreshed distribution setup.
- Next, the focus will be on how Kemper's return to quarterly profitability could influence the investment narrative around its restructuring efforts.
Kemper Investment Narrative Recap
To own Kemper, you need to believe the restructuring in specialty auto and the shift in geographic mix can steadily translate into cleaner underwriting and more stable earnings. The third quarter return to profit, helped by tighter pricing and fewer personal auto policies, speaks directly to that. The key near term swing factor remains whether these underwriting changes can hold up across more quarters.
The biggest risk still sits in weak segments and legacy issues. Management is working against a recent period where nine month results showed a sizeable net loss and earlier impairment charges weighed on equity. Pressure in California personal auto, plus debt levels and an uncovered dividend, means any stumble on pricing or cost control could slow the earnings repair story highlighted in the analyst consensus Narrative on Simply Wall St.
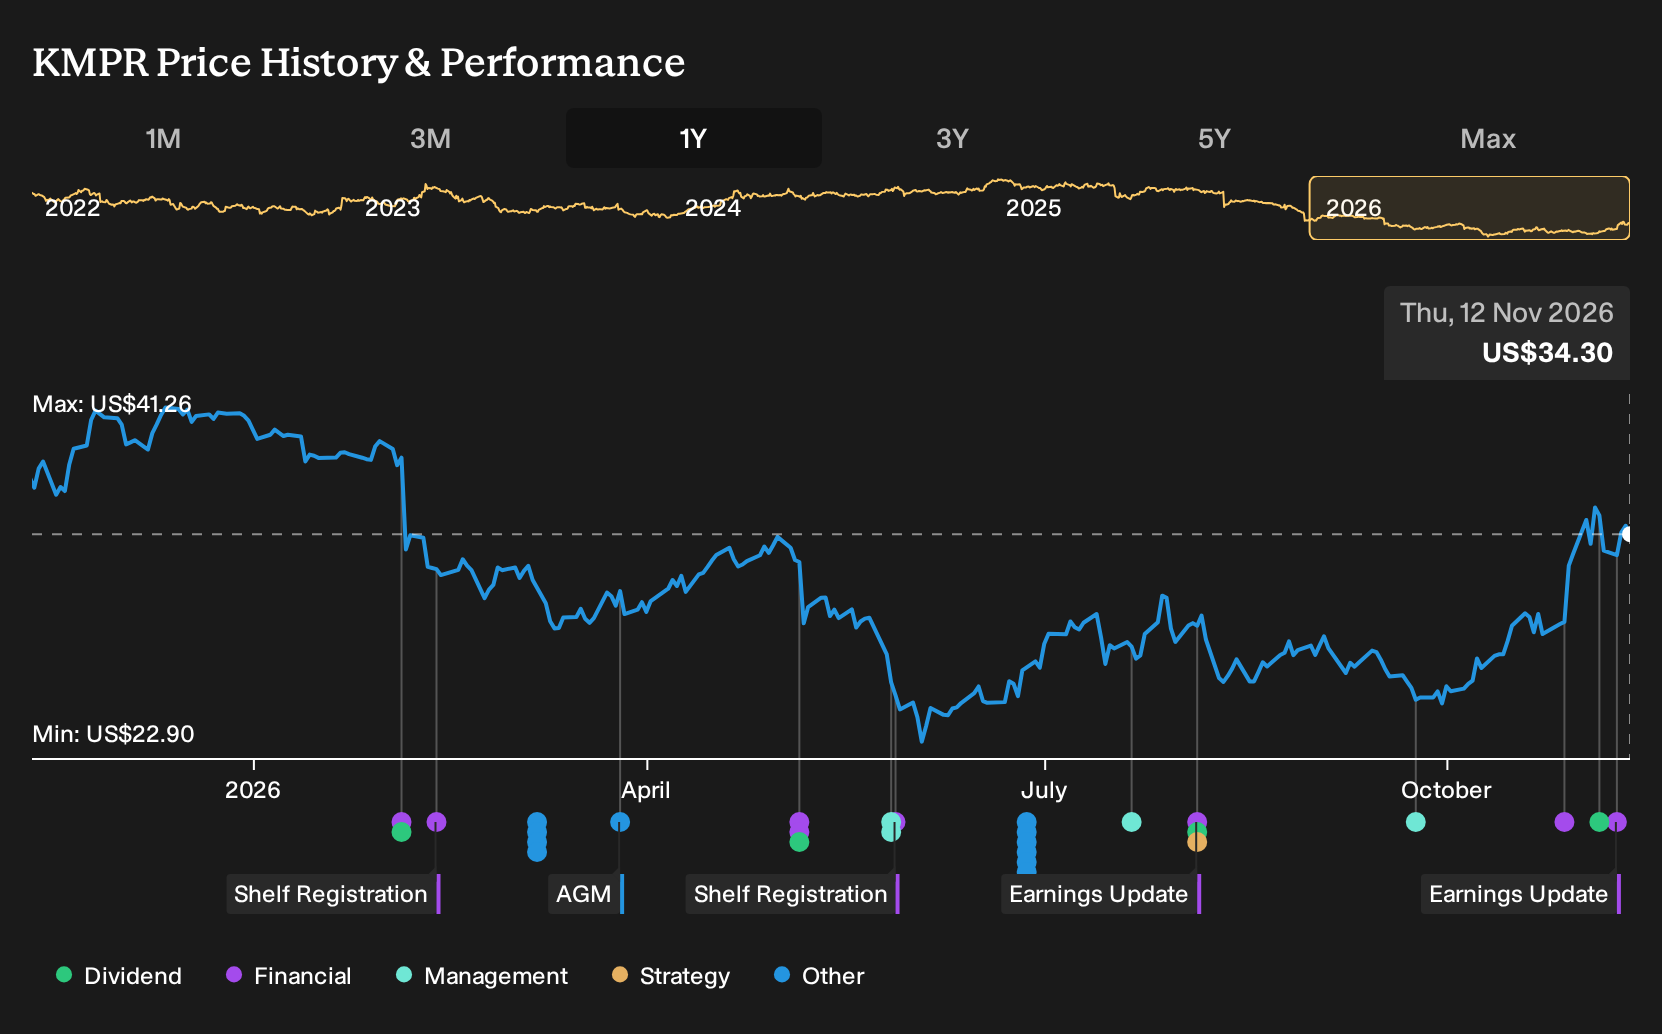
The most relevant recent move is Kemper’s decision to maintain a quarterly dividend of US$0.32 per share, payable on 2 December 2026. For you as a shareholder, that focuses attention on whether improving underwriting and the new auto product rollout can support both capital needs and ongoing cash returns while the business is still working through losses year to date.
This payout also sharpens the trade off between income and balance sheet flexibility. With Kemper reporting a net loss of US$414.1 million for the first nine months of 2026 and carrying a high level of debt, continued dividends lean on future execution. The durability of the restructuring program, the state mix shift, and cost reductions will matter if the firm wants to keep that dividend without constraining operational catalyst delivery.
Kemper's current earnings are a loss of US$495.5 million, while analysts forecast consensus earnings of US$527.0 million by 2029. This implies an earnings swing of about US$1,022.5 million. These projections also incorporate an annual revenue decline rate of 2.2%, with revenues expected to reach US$4.3 billion by 2029.
Uncover how Kemper's fair value indicates a 6% potential upside to its current price before the discount starts to close.
Exploring Other Perspectives
One alternate view zooms in on the risk that Kemper’s earnings repair stalls. The most cautious analysts were assuming revenue of about US$4.1b and earnings of roughly US$520.3m by 2029, yet they still saw the stock as expensive. Those forecasts were set before this latest profit return, so their story may evolve from here.
Explore 3 other Kemper fair value estimates, including one that suggests as much as 21% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kemper research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kemper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemper's overall financial health at a glance.
Looking for more ideas beyond Kemper?
If Kemper has sharpened your focus on underwriting discipline and balance sheet strength, it can be useful to line it up against a wider watchlist of insurers and financials. The Simply Wall St Screener lets you filter for traits that match your risk appetite and income goals, rather than chasing headlines.
- If you want potential mispriced opportunities with solid quality markers, scan our 32 high quality undervalued stocks that already meet strict fundamentals filters.
- If capital preservation and resilience matter most to you, review a 29 resilient stocks with low risk scores that groups stocks with sturdier financial profiles and lower risk scores.
- If you prefer to hunt for future leaders before they are widely followed, check out a 20 high quality undiscovered gems that already screen well on quality and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com