


EN
How Investors May Respond To BJ's Restaurants (BJRI) Raised Profit Guidance
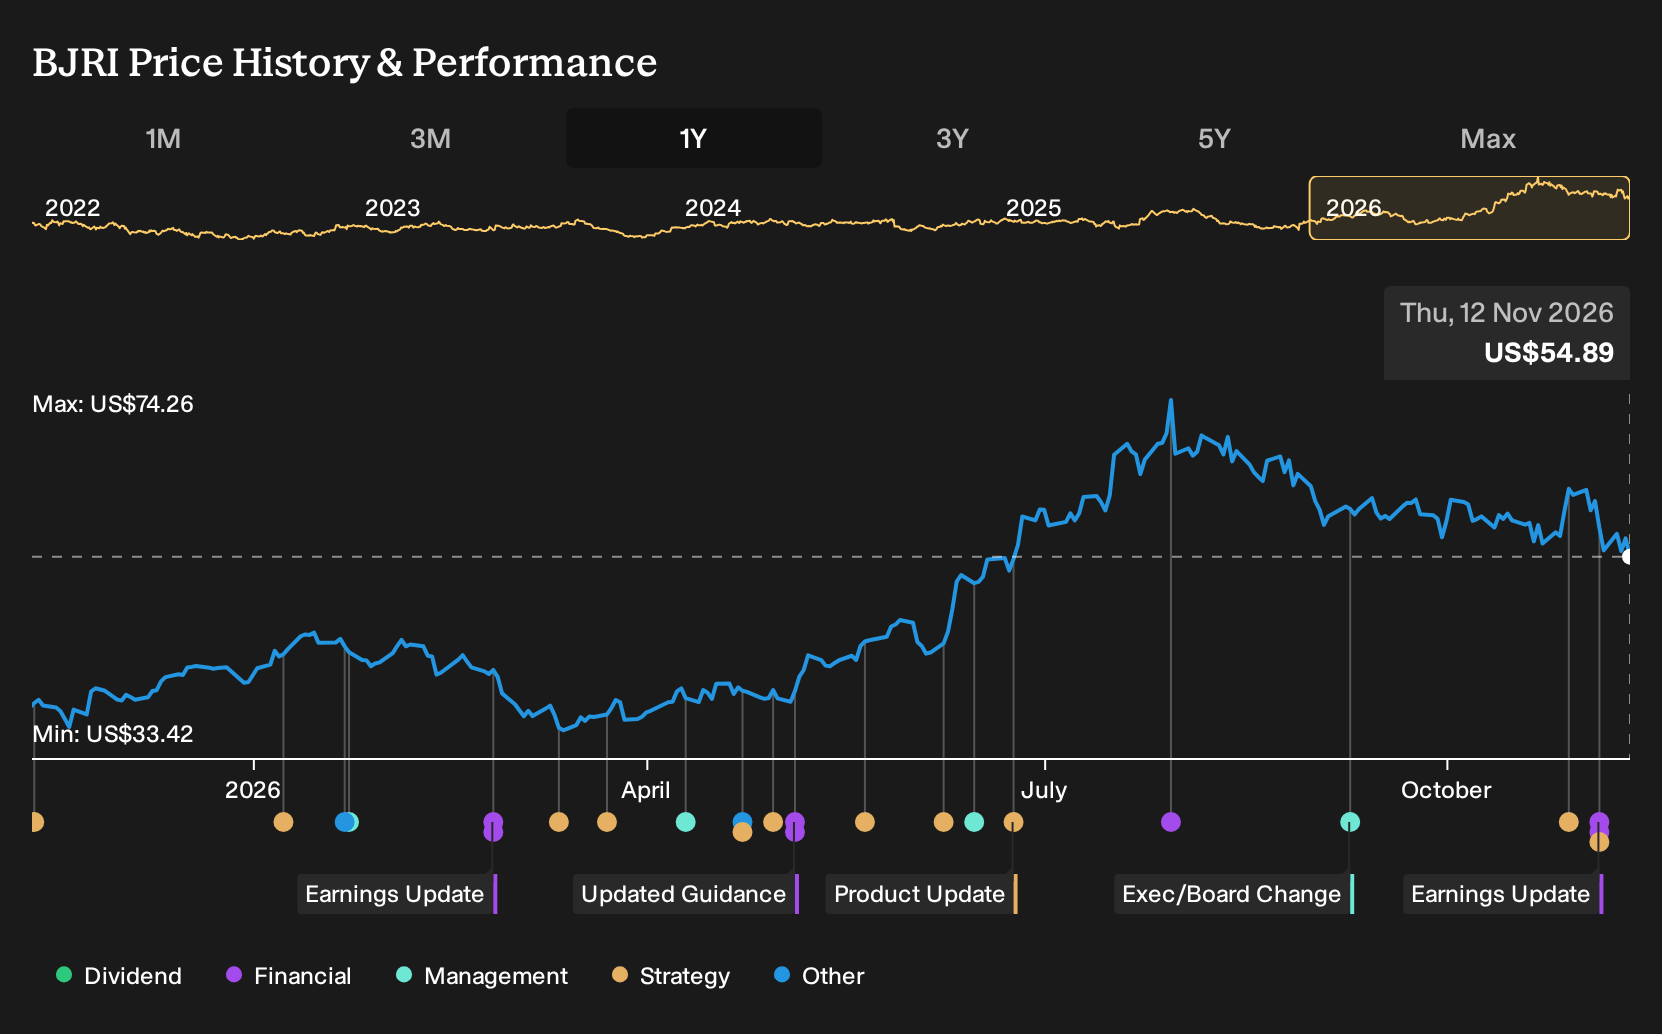
- BJ's Restaurants reported third quarter 2026 sales of US$358.63 million and net income of US$5.32 million, along with higher full-year restaurant-level operating profit guidance and updated comparable sales expectations.
- The new holiday menu, featuring higher ticket items such as a 16 ounce Hawaiian Rib Eye and premium shareable sides, highlights how BJ's Restaurants is leaning on menu mix and seasonal innovation to support its operating targets.
- This article will examine how BJ's Restaurants' investment narrative aligns with the stronger quarterly earnings and higher operating profit guidance.
BJ's Restaurants Investment Narrative Recap
For BJ's Restaurants, the basic belief is that menu renovation, traffic from dessert platforms like Pizookies and tighter in store execution can support healthy restaurant level profit over time. The latest quarter shows sales of US$358.63 million and net income of US$5.32 million, which keeps attention firmly on margin quality rather than sheer expansion.
The raised restaurant level operating profit guidance to US$233 million to US$237 million puts near term focus on whether those store level economics hold. The biggest operational risk still sits with cost pressures and relatively low gross margin, which could compress earnings if food or labor inflation affects that upgraded profit range.
The most relevant fresh data point is the revised full year operating profit outlook. Management is now guiding to US$233 million to US$237 million and expects comparable restaurant sales to increase about 4.7%. That update directly relates to the main near term catalyst, which is whether higher traffic and richer check averages can support better cash generation per location.
This guidance also tests the risk flagged in the analyst consensus Narrative on Simply Wall St around limited pricing power and cost sensitivity. If BJ's Restaurants maintains that profit range while continuing menu and labor process changes, it supports the view that restaurant level margins can improve. If input costs or weaker off premise demand affect results, that thesis becomes harder to support with numbers.
BJ's Restaurants' narrative points to revenues of US$1.6b and earnings of US$72.2 million by 2029. Analysts are assuming revenue rises at about 4.4% a year, and that this outcome would mean earnings grow by roughly US$31.3 million from US$40.9 million today.
Uncover why BJ's Restaurants' fair value indicates a 37% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish catalyst that contrasts with the baseline caution is how aggressively some analysts leaned into revenue acceleration at BJ's Restaurants even before this earnings beat and holiday menu news. The most optimistic forecasts were built around revenue of about US$1.7b and earnings of US$69.9 million by 2029. That is a step up from the consensus view near US$1.6b and US$72.2 million. You can treat this quarter and the upgraded guidance as a live test of those stronger assumptions. Analyst opinions clearly span a wide range, so it can help to compare both narratives against your own expectations and stay open to revisions as fresh data lands.
Explore another BJ's Restaurants fair value estimate, including one that suggests up to 37% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BJ's Restaurants research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for BJ's Restaurants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BJ's Restaurants' overall financial health at a glance.
Looking For More Ideas Beyond BJ's Restaurants?
If the story around BJ's Restaurants has sharpened how you think about quality, pricing power and operational execution, it can help to compare it against a wider set of opportunities. The Simply Wall St Screener lets you filter for traits that matter to you and then track how those businesses stack up over time.
- If capital preservation sits at the top of your list, start with a basket of companies screened for resilience through a 29 resilient stocks with low risk scores that focuses on steadier risk profiles and stronger fundamentals.
- If you care more about balance sheet strength than headline growth, scan a list of solid balance sheet and fundamentals (23 results) and zero in on businesses with cleaner debt levels and supportable funding structures.
- If you want potential upside without the constant spotlight, widen the search to a curated 20 high quality undiscovered gems that highlights under-followed stocks with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com