


EN
Are Wall Street Analysts Predicting Albemarle Stock Will Climb or Sink?
Charlotte, North Carolina-based Albemarle Corporation (ALB) develops, manufactures, and markets engineered specialty chemicals for mobility, energy, connectivity, and health solutions. With a market cap of $11.3 billion, the company offers critical ingredients used in grid storage, automotive, aerospace, conventional energy, electronics, construction, agriculture and food, pharmaceuticals, and medical devices.
Shares of this lithium giant have underperformed the broader market over the past year. ALB has declined 14% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.8%. In 2026, ALB stock is down 32.9%, compared to the SPX’s 10.9% rise on a YTD basis.
Narrowing the focus, ALB’s underperformance is also apparent compared to the Global X Lithium & Battery Tech ETF (LIT). The exchange-traded fund has declined about 4.6% over the past year. Moreover, the ETF’s 8.4% losses on a YTD basis outshine the stock’s double-digit dip over the same time frame.
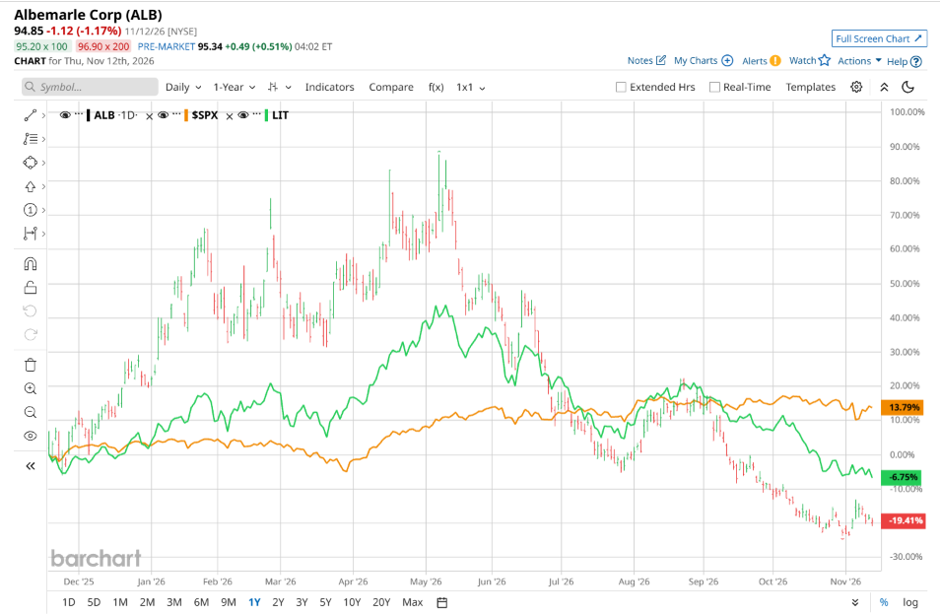
ALB’s underperformance has been heavily pressured by a prolonged cyclical downturn in lithium prices, driven by an oversupplied global market and slower-than-expected near-term adoption rates for electric vehicles.
On Nov. 4, ALB shares closed up over 5% after reporting its Q3 results. Its adjusted EPS of $2.58 beat Wall Street expectations of $2.56. The company’s revenue was $1.6 billion, topping Wall Street forecasts of $1.5 billion.
For the current fiscal year, ending in December, analysts expect ALB’s EPS to grow significantly to $10.64 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 23 analysts covering ALB stock, the consensus is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, two “Moderate Buys,” and nine “Holds.”
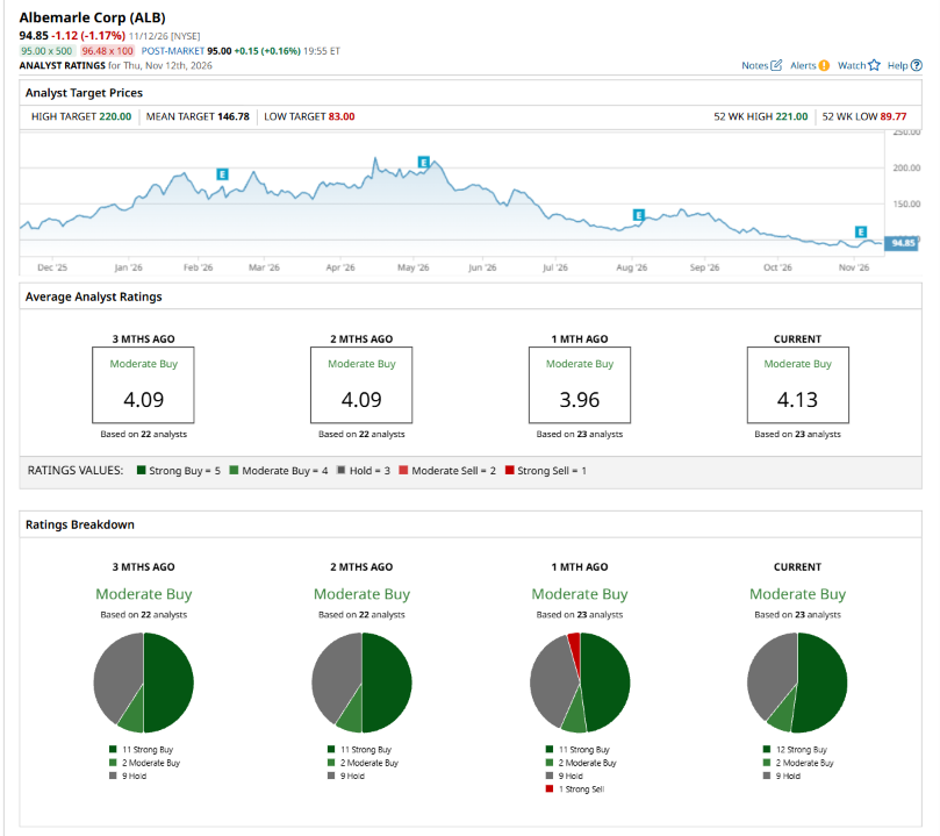
This configuration is more bullish than a month ago, with 11 analysts suggesting a “Strong Buy,” and one recommending a “Strong Sell.”
On Nov. 12, Bank of America Corporation (BAC) analyst Matthew DeYoe kept a “Buy” rating on ALB and lowered the price target to $120, implying a potential upside of 26.5% from current levels.
The mean price target of $146.78 represents a 54.7% premium to ALB’s current price levels. The Street-high price target of $220 suggests an ambitious upside potential of 131.9%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.