


EN
Is NGL Energy Partners (NGL) Reasonable After Its 6x Run?
NGL Energy Partners has delivered a very strong multi year share price run, which puts a spotlight on whether the current valuation can still be grounded in its sales. With that backdrop, the key issue for you now is how much revenue strength is already reflected in the price you see on screen.
- The unit price is up about 6x over the past 5 years. As a result, any fresh capital going into NGL Energy Partners today is far more exposed to whether its sales base can justify that kind of move.
- Recent progress in produced water treatment and pipeline projects, along with higher water volumes and related revenues, may support expectations for a larger and potentially more stable sales stream over time. That, in turn, feeds directly into how rich or restrained the revenue multiple feels.
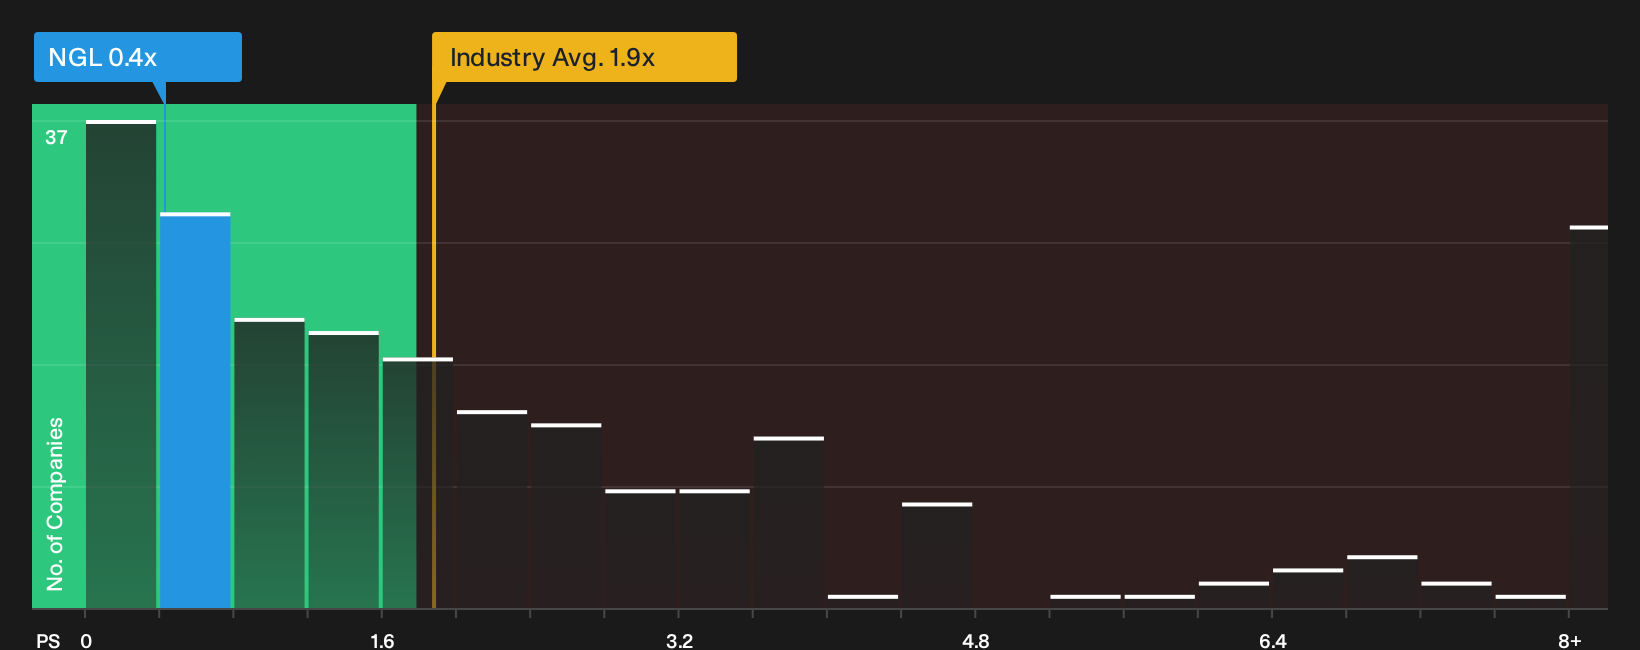
- Would you pay the same price for NGL Energy Partners's peers? See how NGL Energy Partners's 0.4x P/S compares with its peers.
The issue now is whether the current unit price of NGL Energy Partners is adequately supported by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales based valuation question across a wider field, compare NGL Energy Partners with 32 high quality undervalued stocks
Where Does NGL Energy Partners Sit on Sales?
The P/S ratio works well for NGL Energy Partners because investors are weighing the unit price against a revenue stream that is front and center in its water infrastructure story. On this metric, the partnership trades on a P/S of 0.4x, which is below both the Oil and Gas industry average of 1.9x and the peer group average of 2.6x.
The Fair Ratio, which reflects what you might expect for NGL Energy Partners given its size, margins, industry and risk profile, points to a level not far from where the current P/S sits. Because the produced water treatment and pipeline expansions reported in recent quarters have already sharpened focus on the water segment, this relatively low sales multiple suggests the market price is broadly about right when set against that tailored benchmark. To judge whether that still leaves room on the table, you need to decide how durable those water volumes and contracts look over a full cycle. Explore the numbers behind NGL Energy Partners's P/S valuation.
The NGL Energy Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for NGL Energy Partners build on the valuation puzzle above by spelling out which revenue, margin and earnings paths would need to play out for the units to be worth materially more or less than today’s price. They sit on the partnership's Community page. Each narrative links its number to a specific view on how growth, profitability and risk could evolve, giving you something concrete to track as fresh information comes through.
A clear, written Narrative on NGL Energy Partners' units is useful now because it pins down the specific sales, margin and water infrastructure assumptions that would need to hold for today’s P/S to look reasonable as new information lands. With fresh developments like the produced water treatment project in Reeves County and the announced pipeline extension and related volume contract, a number-driven view lets you track whether those projects and contracts actually deliver the revenue and earnings profile implied in the current valuation.
Share your own Narrative for NGL Energy Partners and set out the assumptions behind your valuation.
One more NGL Energy Partners check that belongs next to the price tag
Before you move on from NGL Energy Partners, it is worth asking who is steering the business and how their pay packets line up with your interests. See who runs NGL Energy Partners and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com