


EN
Surgery Partners (SGRY) Could Be 12% Below Fair Value On Third Quarter Earnings
Surgery Partners (SGRY) has released third quarter and nine-month 2026 results, reporting sales of $815.3 million and a quarterly net loss of $21.1 million.
The latest earnings update lands after a sharp swing in sentiment around Surgery Partners. The share price has climbed strongly in recent weeks, with a 30-day share price return of 82.68% and a year-to-date gain of 74.18%. However, the 5-year total shareholder return is still down 46.01%, which suggests recent momentum is rebuilding from a weaker long-term base.
Spot fresh momentum stories around Surgery Partners by scanning our hand-picked 32 high quality undervalued stocks with stronger balance sheets and fundamentals.Bulls view Surgery Partners as a recovery story following the sharp rebound, while bears highlight ongoing losses and a weaker long-term record. Which side does the current valuation evidence appear to support next?
Most Popular Narrative: 16% Overvalued
The analyst consensus Narrative on Simply Wall St places Surgery Partners' fair value at $22.90, which sits below the last close of $26.58 and presents the current rebound within a more cautious long term earnings profile built into that model.
The current valuation, including the agreed US$6b take-private transaction at US$25.00 per share with additional potential monthly payments, implies that Surgery Partners will justify a premium price even though this narrative characterizes the stock as overvalued and bearish.
See why 6 investors see Surgery Partners as 16% overvalued.
Result: Fair Value of $22.90 (OVERVALUED)
Still, two pressure points could flip the Surgery Partners story: the higher government payer mix and the elevated leverage even after the Idaho Falls sale.
Find out about the key risks to this Surgery Partners narrative.
Another View: Cash Flows Point A Different Way For Surgery Partners
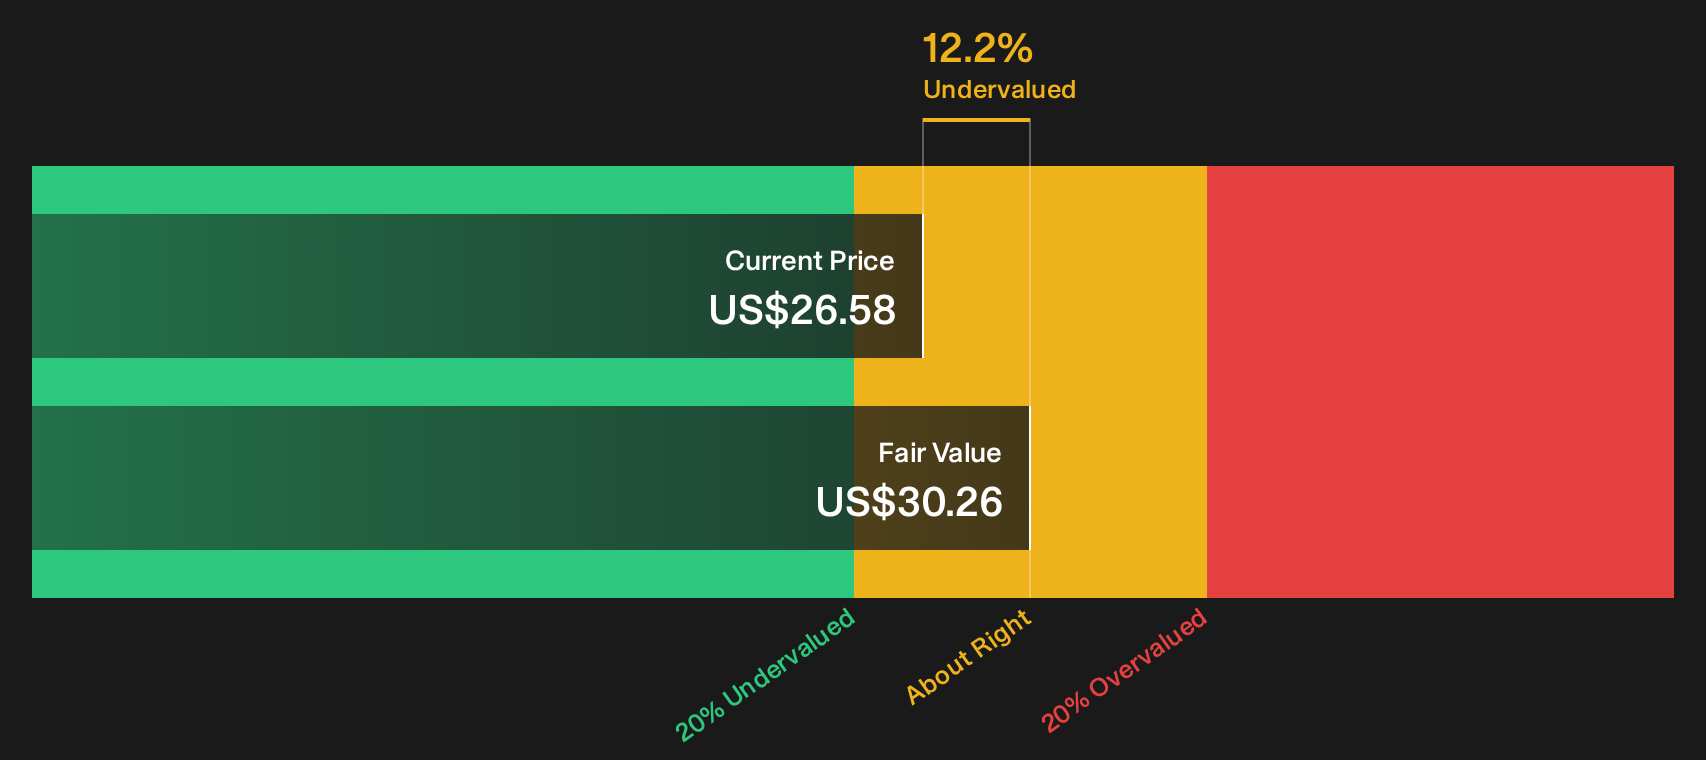
The analyst narrative tags Surgery Partners as 16% overvalued against a fair value of $22.90, yet our DCF model lands in a different place. Using that approach, the stock trades about 12.2% below an estimated future cash flow value of $30.26. This raises a simple question: which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Surgery Partners is clearly split, which is exactly why looking at the underlying data yourself matters right now so you can decide where you stand. To frame that decision with both the upside and the concerns side by side, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Surgery Partners?
If the split views on Surgery Partners have sharpened your focus, use that momentum to hunt for other opportunities before the next move passes you by.
- Target steadier compounding potential by scanning a 6 dividend fortresses that focus on reliable cash returns as part of the total return picture.
- Broaden your watchlist with a list of solid balance sheet and fundamentals (23 results) so you are not caught off guard by fragile financial positions when conditions change.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems that highlight strong fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com