


EN
Qunzhi Consulting: Global tablet panel shipments in the third quarter were about 67.8 million pieces, down 10.9% year on year
The Zhitong Finance App learned that according to Sigmaintell (Sigmaintell) statistics, in the third quarter of 2026, global tablet panel shipments were about 67.8 million pieces, down 10.9% year on year and 10.1% month on month. Unlike the overall shipment performance in the first half of the year, downward pressure on the market began to show at the total volume level in the third quarter. In the first three quarters of 2026, global flat panel shipments totaled about 214 million pieces, a year-on-year decrease of 3.9%.
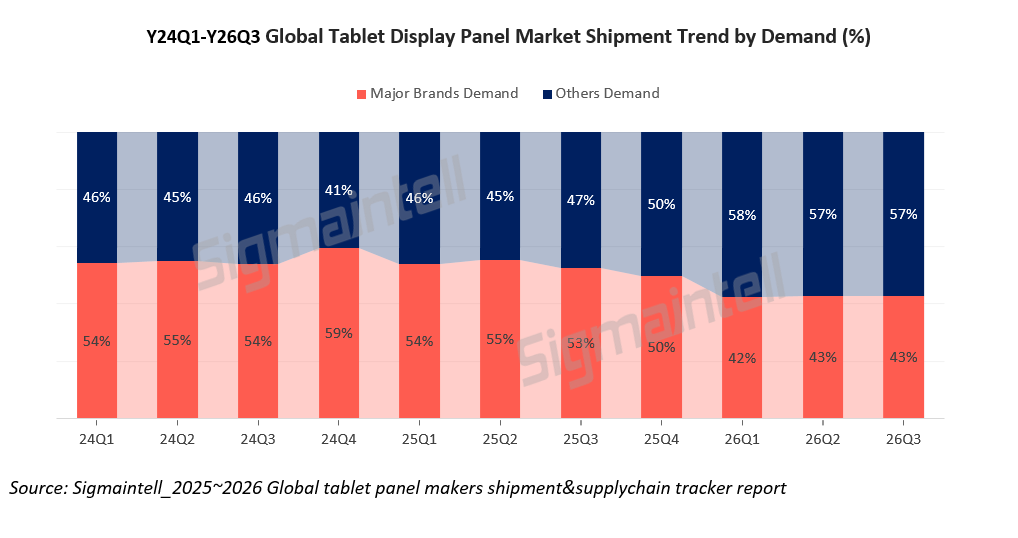
Looking at the market structure, 26Q3's major brands shipped about 29 million tablet panels, down 27.5% year on year, down 10.1% month on month, down about 11 million pieces from the same period last year; the Others market, which mainly focuses on tablets in South China, shipped about 38.8 million tablets, up 7.4% year on year, up about 2.7 million tablets year on year, but the growth momentum slowed significantly from the first half of the year. The increase in the South China tablet market is no longer enough to offset the contraction in demand on the brand side, and the share of panel demand from major brands also dropped from about 53% in the same period last year to about 43%.
Cumulatively, in the first three quarters, major brands shipped about 91 million tablet panels, a year-on-year decrease of 24.1%, a decrease of about 28.9 million pieces; the number of flat panel panels shipped about 123 million pieces, an increase of 19.7% over the previous year, an increase of about 20.1 million pieces.
Overall, rising storage costs are driving up the price of complete terminals and curbing demand for switching. Major brands are becoming more cautious in their procurement strategies, and panel demand continues to shrink. The South China tablet market maintained year-on-year growth with cost control capabilities and channel advantages. Among them, it also benefited from some panel manufacturers actively expanding the channel market after brand demand slowed down. However, the current channel-side inventory level is relatively high, and subsequent inventory digestion pressure is worth paying attention to. As cost pressure gradually spreads downstream, the growth momentum of the South China tablet market has also begun to weaken, and shipments have declined markedly in the third quarter compared to the previous quarter.
Panel technology structural differentiation: Oxide bucked the trend, a-Si and LTPS continued to be pressured, and OLED bottomed out in the short term
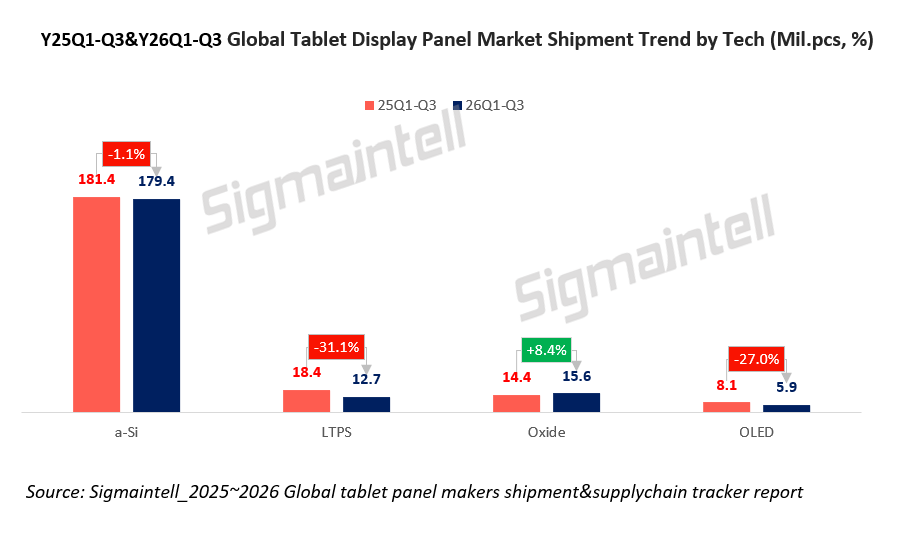
Judging from the technical structure, the technical route differentiation of the global flat panel market further intensified in the first three quarters of 2026. With the exception of Oxide LCD, cumulative shipments of other major technology routes all showed a year-on-year decline. Among them, technology routes that are highly relevant to the brand market were particularly affected by shrinking demand.
a-Si: The South China market provides demand support, and brand-side demand shrinks at an accelerated pace
In the first three quarters of 2026, global a-Si LCD shipments totaled about 179 million pieces, down 1.1% year on year; of these, 26Q3 shipped about 56.6 million pieces, down 9.4% year on year, down 10.5% month on month, and the decline increased markedly. By market, demand for a-Si in the South China tablet market has maintained year-on-year growth, which is the main demand support for the a-Si LCD market; demand for a-Si in the brand tablet market fell by about 30% year on year in the third quarter, which is the main reason for the overall decline in a-Si. Demand for a-Si on the brand side declined. On the one hand, it was affected by the increase in the price of the whole machine, and the low-end tablet market shrank markedly; on the other hand, some products gradually switched from A-Si to oxide LCD, further exacerbating the contraction in demand for a-Si in the brand market.
LTPS: Demand adjustment continues, and full-year shipments are expected to drop by about 31%
In the first three quarters of 2026, global LTPS LCD shipments totaled about 12.7 million pieces, a year-on-year decrease of 31.1%. It is still the LCD technology route with the biggest decline; of these, 26Q3 shipped about 3.8 million pieces, a year-on-year decrease of 28.5%. Demand in the middle and high-end tablet market continues to be under pressure due to the overdraft effect of national supplements and price increases for flagship tablets. At the same time, as the application of oxide LCD gradually expands and OLED continues to penetrate the high-end market, LTPS LCD faces a two-way squeeze from two technology routes. #群智咨询(Sigmaintell)预计2026年全年LTPS LCD shipped about 16.5 million pieces, a year-on-year decrease of about 31%; in 2027, it fell further to about 11.5 million units, and the market size continued to shrink.
Oxide: Technology upgrades continue to be promoted, becoming the only technical route to maintain growth
In the first three quarters of 2026, global Oxide LCD shipped about 15.6 million tablets, up 8.4% year on year; of these, 26Q3 shipped about 5 million tablets, up 11.7% year on year, down 15.7% month on month. The growth of oxide LCD mainly benefits from panel manufacturers promoting technological upgrading of brand products. Some tablet products that originally used the A-Si solution gradually switched to oxide LCD, driving the continuous increase in their market penetration rate. Although shipments declined slightly from month to month due to weakening overall demand in the third quarter, growth continued year-on-year. Shipments of 26Q4 oxide LCD are expected to increase by about 45% year on year, and shipments for the full year of 2026 will increase by about 18% year on year. As brand product technology upgrades continue to advance, demand for Oxide LCD is expected to increase further in 2027.
OLED: Short-term demand is low and is expected to restart a new round of growth in 2027
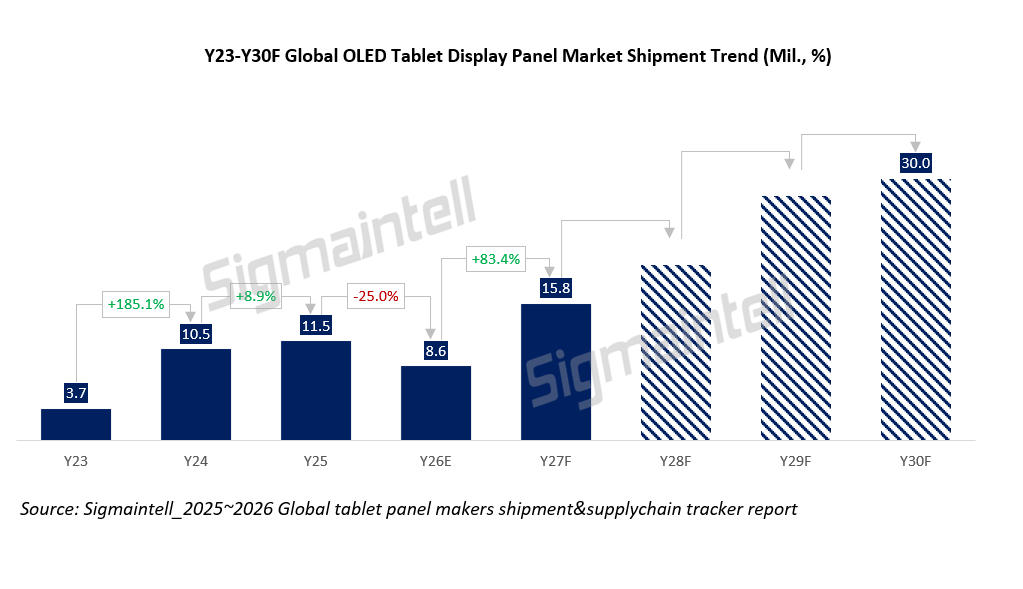
In the first three quarters of 2026, global OLED panel shipments totaled about 5.9 million pieces, a year-on-year decrease of 27.0%; of these, 26Q3 shipped about 2.4 million pieces, a year-on-year decrease of 37.5%, and a year-on-month increase of 30.1%. Due to rising terminal prices and weak demand for high-end tablets, the actual demand for OLED panels is still low. However, shipments picked up month-on-month in the third quarter, driven by new products, and short-term demand is expected to gradually stabilize. It is estimated that about 8.6 million OLED panel panels will be shipped in 2026, a year-on-year decrease of about 25%.
In the medium to long term, the OLED tablet market is still in the early stages of growth. Subsequent growth mainly comes from three aspects: first, the gradual release of Apple iPad Air OLED products, driving a recovery in demand for brand OLED tablets; second, the gradual release of the G8.6 OLED production line, which is expected to improve the cost competitiveness of medium-sized OLED panels; and third, OLED continues to penetrate into large productivity tablets and flagship small-size tablets, driving further expansion of the scope of application. With the introduction of new products and supply chain cost optimization, global OLED panel shipments are expected to rise to about 15.8 million pieces in 2027, an increase of more than 80% over the previous year, and the market is expected to enter a new growth cycle.
Summary and outlook: Brand demand continues to be under pressure, South China channel inventory needs to be digested, and global shipments are expected to drop by about 4% year-on-year in 2026
In the third quarter of 2026, the global flat panel market changed from a relatively stable volume in the first half of the year to a year-on-year decline, and the market demand structure was further divided. The decline in demand for tablet panels from major brands increased to about 28%, and rising machine prices and weak consumer demand continued to inhibit brand procurement; although the South China tablet market still maintained year-on-year growth, the growth rate was slowing down and falling month-on-month, and channel inventory levels were relatively high, so subsequent growth and inventory digestion still need to be watched.
In 2026, global flat panel shipments are expected to be about 285 million pieces, a year-on-year decrease of 4.1%. Among them, demand from major brands was about 123 million tablets, down 21.8% year on year; demand for South China tablets was about 162 million tablets, up 15.7% year on year. The growth of the South China tablet market is difficult to fully hedge against shrinking demand on the brand side, and the overall market is still facing certain demand pressure.
Looking ahead to 2027, the pressure on storage costs is expected to continue. The growth momentum of the South China tablet market is weakening, overall demand in the global tablet panel market is still not optimistic, and Sigmaintell (Sigmaintell) expects a further decline in shipments throughout the year. However, the overall contraction does not mean that technological upgrades have stopped. The penetration rate of Oxide LCD and OLED in the brand tablet market is expected to further increase, driving the panel market to gradually shift from scale competition to technology and product structure upgrades. Although the total industry growth dividend is weakening, the technology route switch will still bring new product and supply chain opportunities to panel manufacturers.