


EN
Powell Industries (POWL) Heads Into Earnings As Backlog Optimism Meets A Full Valuation
Powell Industries (POWL) is back in focus after affirming a quarterly dividend of US$0.09 per share, with investors weighing that payout against a record US$2.4b project backlog and near term earnings risks.
Recent trading has been choppy for Powell Industries, with the share price down 22.44% over the past 30 days and 33.59% over 90 days, even after a 13.36% gain in the last week that hints at short term momentum returning. In contrast, the stock’s 20.65% year to date share price return and very large 5 year total shareholder return underline how the long run story has looked very different from the recent pullback.
Compare Powell Industries with a hand picked group of power grid and electrification plays using our 43 power grid technology and infrastructure stocks while this sector absorbs the data center and AI build out.
Bulls point to Powell Industries’ US$2.4b backlog and data center exposure, while bears focus on recent share price weakness and margin risk. Which story does the current valuation actually reflect?
Most Popular Narrative: 57% Undervalued
Powell Industries' bullish analyst Narrative on Simply Wall St anchors a fair value of $333 against the last close of $141.77. This implies a steep valuation gap built on optimistic growth and margin forecasts, all discounted at 9.22%.
The multi year build out of U.S. LNG export facilities and related natural gas infrastructure is contributing to a pipeline of large, complex projects, supporting backlog stability, higher plant utilization and stronger gross margins.
Strategic capacity expansions in Houston and ongoing productivity investments are increasing throughput and manufacturing leverage. This may enable Powell to convert its record backlog more efficiently and support higher operating margins over time.
See why 5 investors see Powell Industries as 57% undervalued.
Result: Fair Value of $333 (UNDERVALUED)
Still, the bullish Powell Industries story could be knocked off course if LNG projects are delayed, or if record gross margins retreat from recent levels.
Find out about the key risks to this Powell Industries narrative.
Another View: What Powell Industries' P/E Is Saying
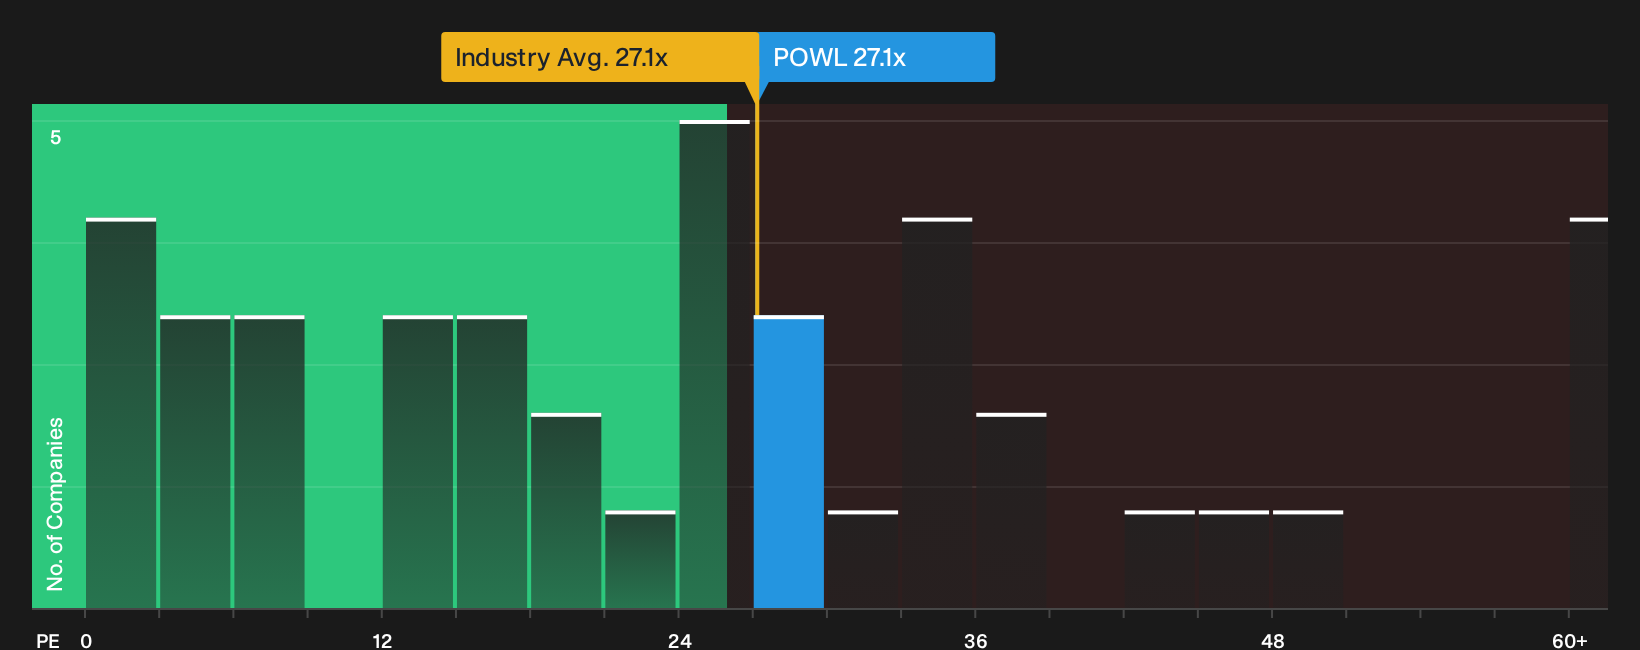
There is a very different message in Powell Industries' current P/E of 27.1x. That multiple is higher than the 19x peer average and roughly in line with the US Electrical industry at 27.1x, yet close to the fair ratio estimate of 27.5x, which leaves less obvious room for error if growth expectations cool.
When the valuation signal from earnings multiples looks this tight, how much confidence do you place in the more optimistic fair value story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity: only the data will tell. Move quickly and review both the upside potential and the downside flags across the 4 key rewards and 1 important warning sign.
Looking for more Powell Industries investment ideas?
If you want to stress test your Powell Industries thesis and avoid getting boxed into a single story, widen the lens and compare it with other opportunities.
- Target potential upside in quality businesses that the market may be overlooking by scanning our 20 high quality undiscovered gems.
- Prioritise resilience and sleep better at night by filtering for companies in the 29 resilient stocks with low risk scores.
- Lean into disciplined fundamentals and stronger balance sheets by reviewing a curated list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com