


EN
What Tanger (SKT)'s Raised Earnings Guidance Means For Shareholders
- Tanger Inc. reported third quarter 2026 sales of US$149.05 million and revenue of US$157.72 million, with net income of US$33.65 million and diluted EPS from continuing operations of US$0.29. The company also updated nine month figures that were higher than the prior year.
- The outlet center owner raised its full year 2026 diluted net income per share guidance to a tighter range of US$1.08 to US$1.12, which reflects how current operating trends are feeding into Tanger’s view of its earnings power for the rest of the year.
- The next step is to examine how Tanger’s investment narrative could be influenced by its tighter, slightly higher full year earnings guidance.
Tanger Investment Narrative Recap
To own Tanger, you need to believe the outlet and open air model can keep attracting strong tenants and shoppers while management steadily fills and reprices space. The analyst consensus Narrative on Simply Wall St leans on tight supply, re-tenanting at higher rents and ancillary income as the key earnings drivers. The latest quarter, with higher year to date revenue and net income versus 2025, broadly supports that operating story.
The near term swing factor is still execution on backfilling space and keeping center level costs under control. Elevated operating expenses or a slower pace of leasing on vacated boxes would matter more than this guidance tweak. The raised but tighter EPS range does not radically change the risk that interest costs and property expenses could pressure margins.
The most relevant update is Tanger’s revised full year 2026 diluted net income per share guidance of US$1.08 to US$1.12. That range is slightly higher at the low end and narrower overall compared with the prior US$1.06 to US$1.13 bracket. It signals management’s current read through from nine month results into the final quarter.
For catalysts, that guidance brackets investor expectations around how leasing, re-tenanting and ancillary revenue flow through to the income statement over the next few months. It also frames the main risk flagged in earlier research that interest payments are not well covered by earnings. If operating trends track the midpoint of guidance, the debate shifts more toward how sustainable that earnings level looks into 2027.
Tanger's narrative projects US$654.7 million revenue and US$148.4 million earnings by 2029. This scenario assumes 1.4% yearly revenue growth and an earnings increase of about US$22.3 million from US$126.1 million today.
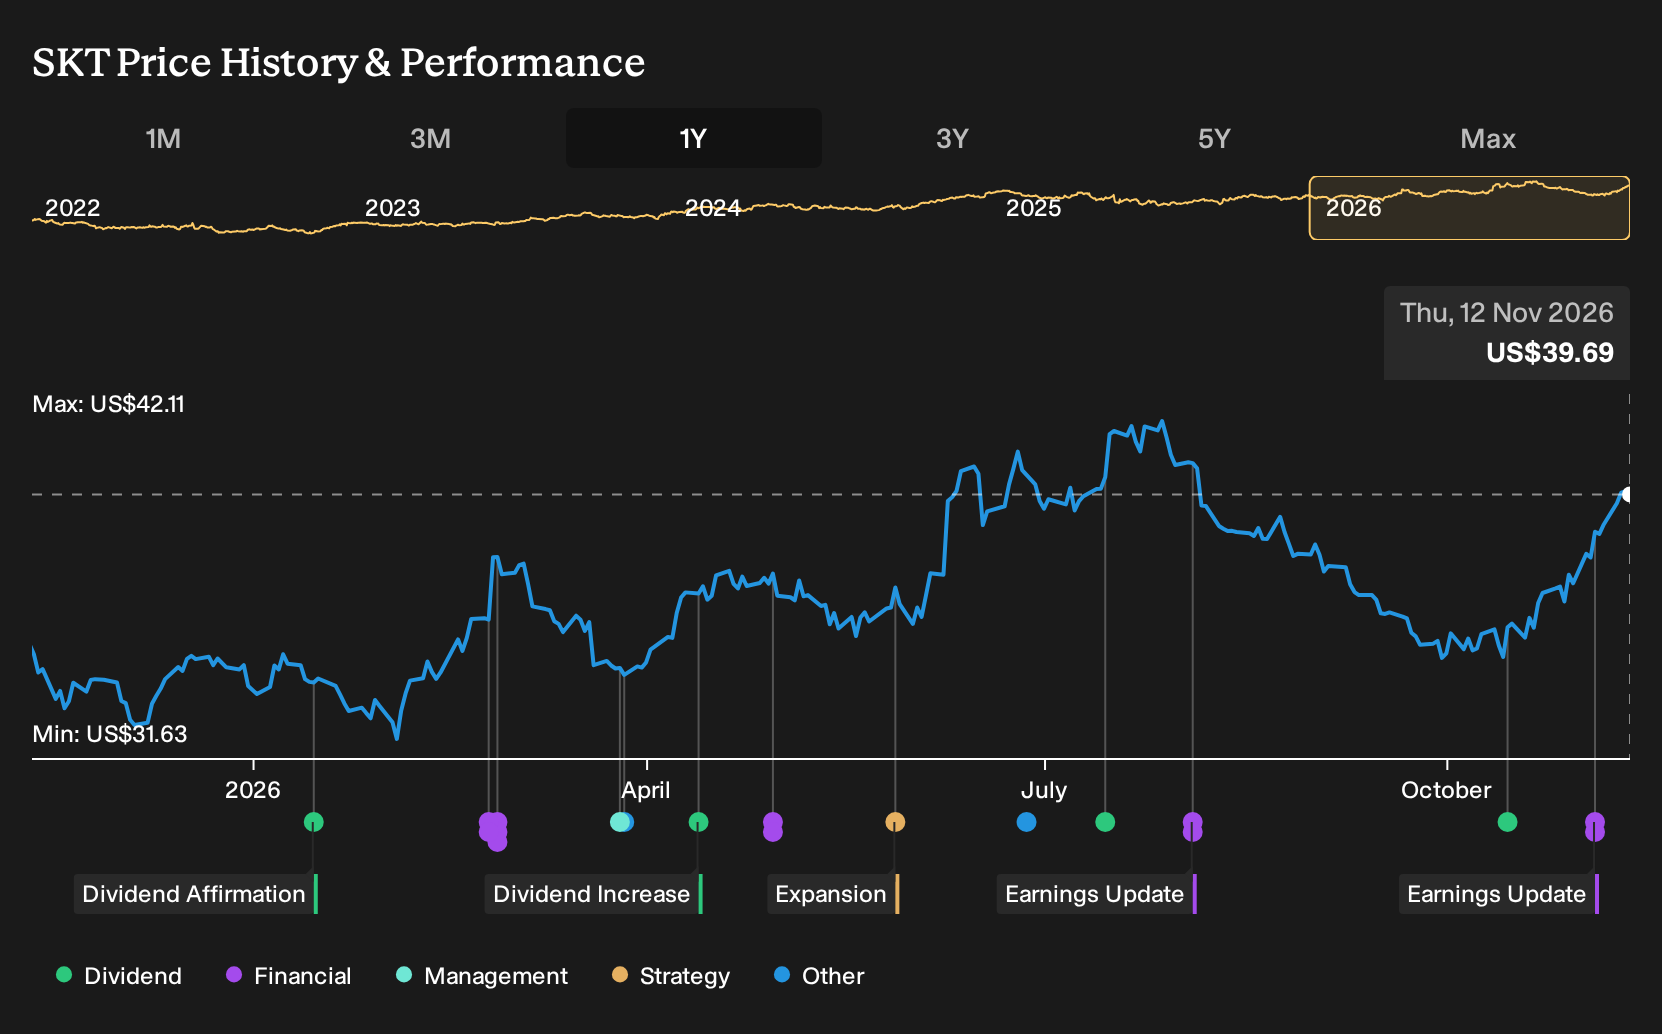
Uncover why Tanger's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$41 and about US$45 per share, which still sit before Tanger’s latest earnings and guidance update. You can weigh those retail investor views against risks such as higher operating costs or potential catalysts such as re-tenanting at higher rents and decide which narrative feels more convincing.
Explore another Tanger fair value estimate, including one that suggests it could be worth just $41.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tanger research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tanger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tanger's overall financial health at a glance.
Looking For More Ideas Beyond Tanger?
If Tanger has sharpened your thinking around earnings quality, it can help to line it up against other companies with different strengths. The Simply Wall St Screener lets you quickly compare fundamentals, balance sheet resilience and income potential so you can build a watchlist that truly matches your own risk and return preferences.
- For investors who want potential upside without ignoring quality, scan a curated pool of 20 high quality undiscovered gems that combine solid fundamentals with under-the-radar profiles.
- If capital preservation matters most to you, sort through 29 resilient stocks with low risk scores that score well on resilience and have fewer red flags on key risk checks.
- For readers focused on financial strength first, filter for a list of solid balance sheet and fundamentals (23 results) so you are starting with companies that have robust fundamentals before you even look at the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com