


EN
FLEX LNG (FLNG) Reaffirmed Guidance And Held Its Dividend, Is The Stock Fully Priced?
FLEX LNG (NYSE:FLNG) just paired its strongest reported third quarter with a fresh confirmation of full year revenue guidance in the US$345 million to US$370 million range and another US$0.75 dividend.
The fresh earnings beat, confirmed revenue guidance and another quarterly dividend have come against a choppy backdrop for FLEX LNG, with the 30 day share price return down 15.34% and the 90 day share price return down 16.14%. However, the 1 year total shareholder return is 10.20% and the 5 year total shareholder return is 104.98%, which suggests longer term momentum has held up even as shorter term sentiment has cooled around the US$25.83 level.
Spot under-the-radar dividend payers with similar income appeal to FLEX LNG by scanning our hand-picked 6 dividend fortresses.FLEX LNG now trades below both its analyst target and an implied intrinsic value, even after strong quarterly numbers. Is that caution a reasonable read on risk, or has pricing swung too far?
Most Popular Narrative: 1% Undervalued
On the analyst consensus Narrative on Simply Wall St, FLEX LNG screens as only slightly below its narrative fair value of $26.13 versus the last close at $25.83. That framing relies on contract cover and LNG trade data rather than short term price moves.
The main thing that has to go right is that FLEX LNG continues to translate its multi-year charter backlog, high fleet utilization and current guidance for 2026 revenues of $345 to $370 million and adjusted EBITDA of $255 to $280 million into cash flows that comfortably support its dividend and balance sheet commitments.
See why 26 investors see FLEX LNG as 1% undervalued.
Result: Fair Value of $26.13 (UNDERVALUED)
Still, the heavy orderbook of 285 to 290 vessels and questions around the US$0.75 quarterly dividend coverage could upset this FLEX LNG fair value story.
Find out about the key risks to this FLEX LNG narrative.
Another View: FLEX LNG Through The Earnings Lens
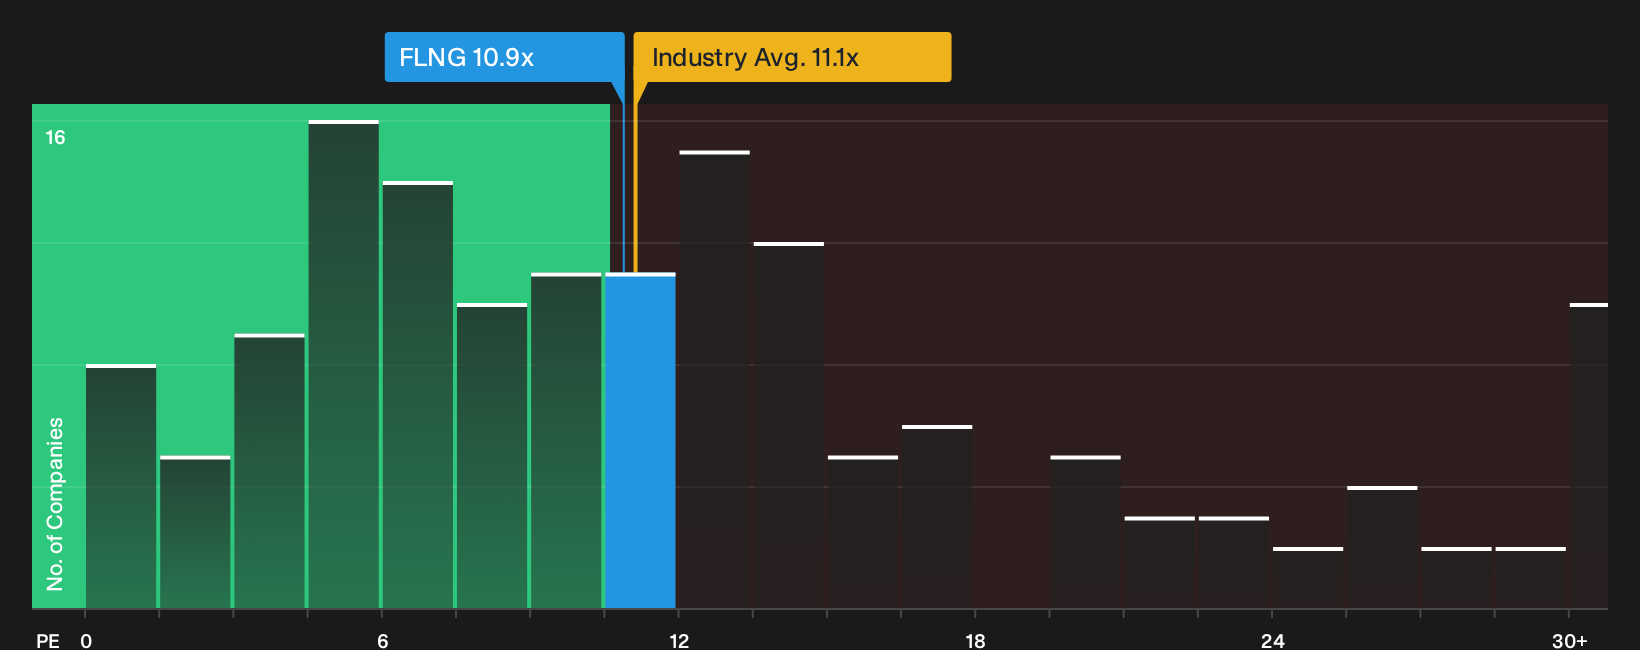
Looking at FLEX LNG through simple earnings multiples changes the picture. The stock trades on a P/E of 10.9x, which is slightly below the US Oil and Gas industry at 11x, yet above both peers at 10.3x and its own fair ratio of 9.3x. That mix points to some valuation risk if sentiment cools further. How much weight do you give this compared with the DCF-style fair value story?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around FLEX LNG can easily pull you in one direction, so move quickly, review the underlying data, and weigh both the 1 key reward and 3 important warning signs.
Looking for more FLEX LNG style investment ideas?
If FLEX LNG has your attention, do not stop here. The real edge comes from regularly refreshing your watchlist with fresh, data driven ideas that others overlook.
- Target potential mispricings by scanning a curated pool of quality candidates through the 32 high quality undervalued stocks.
- Prioritize resilience by filtering for companies with strong finances using the list of solid balance sheet and fundamentals (23 results).
- Get in early on lesser known opportunities by searching across the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com