


EN
Digi International Stock In Focus After Earnings Beat And Disruptive Technologies Deal
- Digi International reported fiscal Q4 2026 sales of US$143.32 million and full year sales of US$535.19 million, alongside guidance for fiscal 2027 that includes expected revenue growth of 10% to 15% versus 2026 and first quarter revenue of US$140 million to US$144 million.
- Management paired this outlook with a pending US$130 million cash acquisition of Disruptive Technologies and the launch of the Digi EX61 5G extender, highlighting an effort to deepen sensor coverage and recurring connectivity services.
- We will monitor how Digi International's investment narrative develops as record results coincide with 2027 growth guidance supported by the Disruptive Technologies acquisition.
Scan beyond Digi International and compare what management is signaling here with other connectivity and sensor players screened as 53 AI infrastructure stocks.
Digi International Investment Narrative Recap
Digi International asks you to believe in a recurring-connectivity and sensor platform that can keep scaling without losing discipline on cash generation. According to LunaRodas, an investor in the Simply Wall St Community, the early arrival of the US$200 million ARR target is central to that story. The fresh 2027 guide for 10% to 15% revenue growth plus at least 15% ARR growth keeps that recurring thesis in focus.
The near term catalyst is whether that guidance still feels achievable as supply chain planning stretches out and first quarter sales are only guided to US$140 million to US$144 million. The biggest operational risk right now is execution on Disruptive Technologies while hyperscaler wins, DANI monetization and AI tools stay quiet.
The most relevant update here is the fiscal 2027 outlook that explicitly assumes the US$130 million Disruptive Technologies deal closes on November 30. Management is effectively tying Digi International’s near term growth story to combining sensor hardware, subscription conversion and Digi Remote Manager into one operating stack.
For you as a shareholder, that makes integration a key catalyst and a clear risk. LunaRodas points out that Jolt and Particle were brought onto common systems successfully. The same integration playbook will now be tested at larger scale, in parallel with supply constraints and a first quarter guide that already looks tight against recent quarterly revenue.
The narrative from LunaRodas places fair value at US$60.68, grounded mainly in Digi International reaching its US$200 million ARR goal a year earlier than the original fiscal 2028 timeline, while still pointing to the same long term EBITDA target. This keeps the original multi year framework intact rather than rewritten.
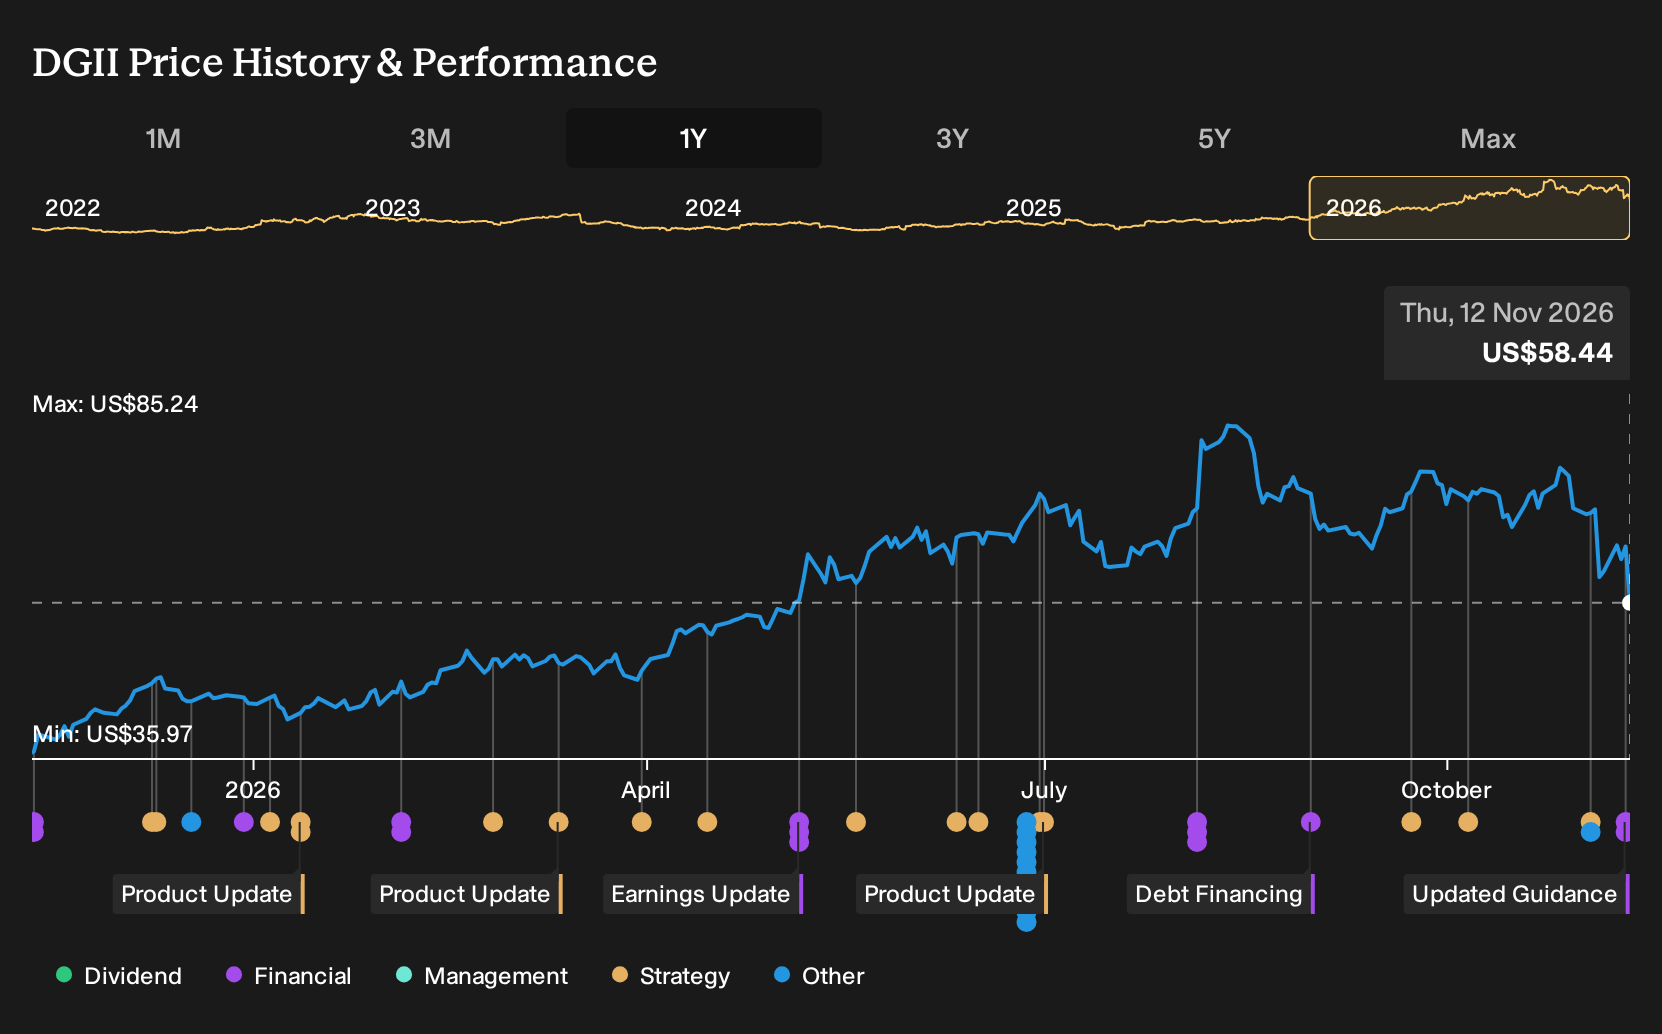
Uncover why Digi International's fair value indicates a 4% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Five Simply Wall St Community members place Digi International’s fair value between US$60.68 and about US$103.82, a wide span for one ticker. Those views were set before the 2027 guidance, Disruptive Technologies deal and EX61 launch, so you are seeing reactions to fresh information layered on top of older valuation anchors.
Explore 4 other Digi International fair value estimates, including one that suggests it could be worth just $60.68.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Digi International research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Digi International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Digi International's overall financial health at a glance.
Looking for more investment ideas beyond Digi International?
Use this update on Digi International as a reference point, then widen the lens and pressure test your thesis against other opportunities using the Simply Wall St Screener.
- If you want potential mispricings with quality traits, scan through a 32 high quality undervalued stocks that match strong fundamentals with attractive valuations.
- For income-focused portfolios, check companies that show consistent payouts inside a 6 dividend fortresses that targets higher yielding payers.
- If capital preservation sits high on your list, start with a 29 resilient stocks with low risk scores and see which businesses carry sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com