


EN
What Macerich Bulls Got Right
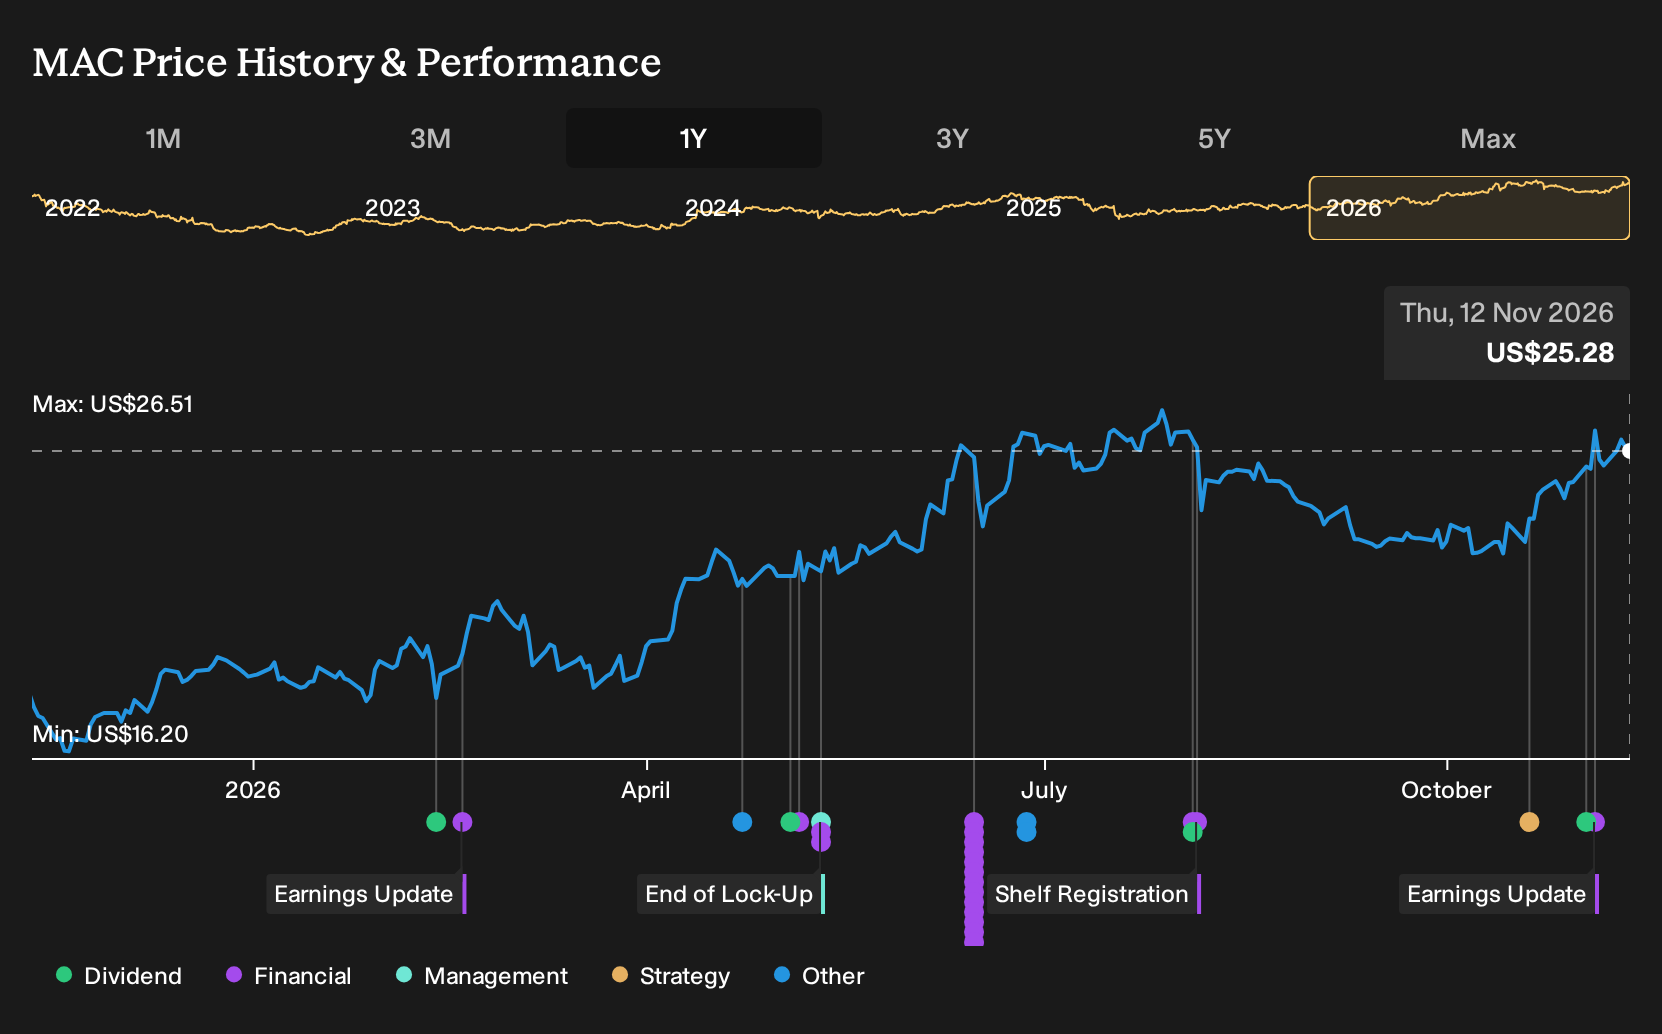
If Macerich sat on your watchlist instead of in your portfolio over the past year, the outcome may feel like a missed turn. Investors who held Macerich over the past year are up 51.2%, including dividends. That result invites a blunt question. What clues in late 2025, such as the push into experiential retail and high-barrier urban malls despite heavy leverage, could have helped you judge whether its leasing thesis was strong enough to outweigh balance sheet strain?
If the move has made Macerich harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Stories Macerich Investors Were Weighing
The shares cost US$17.54 at the start of the period, and the debate around Macerich hinged on which story you thought the malls were telling.
The bullish narrative saw experiential retail and urban assets as a repair job in progress. It treated a Fair Value of US$19.53, an implied price based on its own assumptions, as reasonable if revenue slipped about 1.1% a year while profit margins climbed toward 2.2% and high-barrier malls held their appeal.
The bearish script put more weight on e-commerce and leverage. It pointed to a Fair Value of US$15, again an implied number, and focused on the risk that a long shift to online shopping and high net debt near eight times EBITDA would keep pressuring mall cash flows.
What The Results Changed For The Macerich Debate
Macerich’s Q3 2026 report showed revenue of US$267.08 million and a loss of US$16.95 million, with net margin improving to a loss of 6.3% from a loss of 33.3% a year earlier. Stronger leasing and acquisitions, including Annapolis Mall, supported the optimistic story on occupancy and cash generation, while ongoing losses kept the profitability part of that thesis unproven. Overall, the evidence cut both ways.
The episode turned on whether better leasing would show up in margins. For a different REIT, this can be checked directly against changes in net operating income, absolute profit and the reported net margin trend after each quarter.
What Macerich’s Price Already Assumes Today
Macerich now trades at US$25.28, and the bearish analyst Narrative on Simply Wall St sees its Fair Value as sitting below that quote. The focus is not just the malls. The argument centers on how much of the leasing rebound and the recent equity raise is already embedded in the valuation.
For today’s price to hold up, a buyer would effectively be assuming that leasing momentum stays strong enough to offset e-commerce pressure. At the same time, high leverage and new shares from the forward equity raise would need to avoid placing a ceiling on future upside.
"Persistent shifts to e-commerce and changing consumer preferences threaten long-term leasing revenue and profitability, despite recent leasing gains and backfilling efforts. High leverage and exposure to underperforming malls increase refinancing risk, limit redevelopment capacity, and pressure future earnings and cash flow."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - run fee based consulting on technical safety, regulatory and litigation challenges.
- Company 2 - 36% below our estimate - handle air freight logistics, customs and compliance as AI linked cargo needs evolve.
- Company 3 - 47% below our estimate - sell accelerated computing systems that customers use to expand intensive AI workloads.
That is three of the list. See all 23 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com