


EN
How Half Year Earnings Growth Will Impact Nippn Stock Investors
- Nippn reported half year earnings for the period ended September 30, 2026, with sales of ¥213,509 million and net income of ¥10,226 million, alongside higher basic and diluted earnings per share from continuing operations compared with the prior year period.
- The earnings release stated that Nippn converted its higher sales into improved earnings per share, indicating that cost control and operational efficiency were important supports for profitability during the half year.
- This raises the question of how Nippn's investment narrative around efficiency and capital allocation is influenced by the latest uplift in earnings per share.
Nippn Investment Narrative Recap
To own Nippn, you need to believe in a simple story. The business is trying to turn steady flour and food demand into better efficiency, higher quality earnings and tighter capital allocation. According to AstrisCorporateAdvisory, an investor in the Simply Wall St Community, the key short term swing factor is how quickly new mills and projects translate into operating gains while depreciation costs step up.
The latest half year numbers, with higher sales, net income and earnings per share, broadly support that efficiency focus. The catalyst around production upgrades, including the Chita Mill, looks intact in the near term. The bigger risk still sits around execution on cost control and the impact of heavier depreciation on reported profitability.
AstrisCorporateAdvisory highlighted Nippn’s record pipeline of capital expenditure projects and the Chita Mill that began operating in February 2026. That backdrop sets the stage for the recent half year result, where higher earnings per share suggest the efficiency push is feeding through, even as the asset base grows and starts to carry more depreciation.
Capex in FY3/26 of ¥33.5b and the shift in funding structure, including redemption of the ¥25b convertible bond and new debt of ¥50.3b, frame today’s earnings within a bigger balance sheet story. For you as a shareholder, the operational question is whether incremental efficiency and cost discipline can offset higher non cash charges while keeping cash generation and dividends on a sustainable footing.
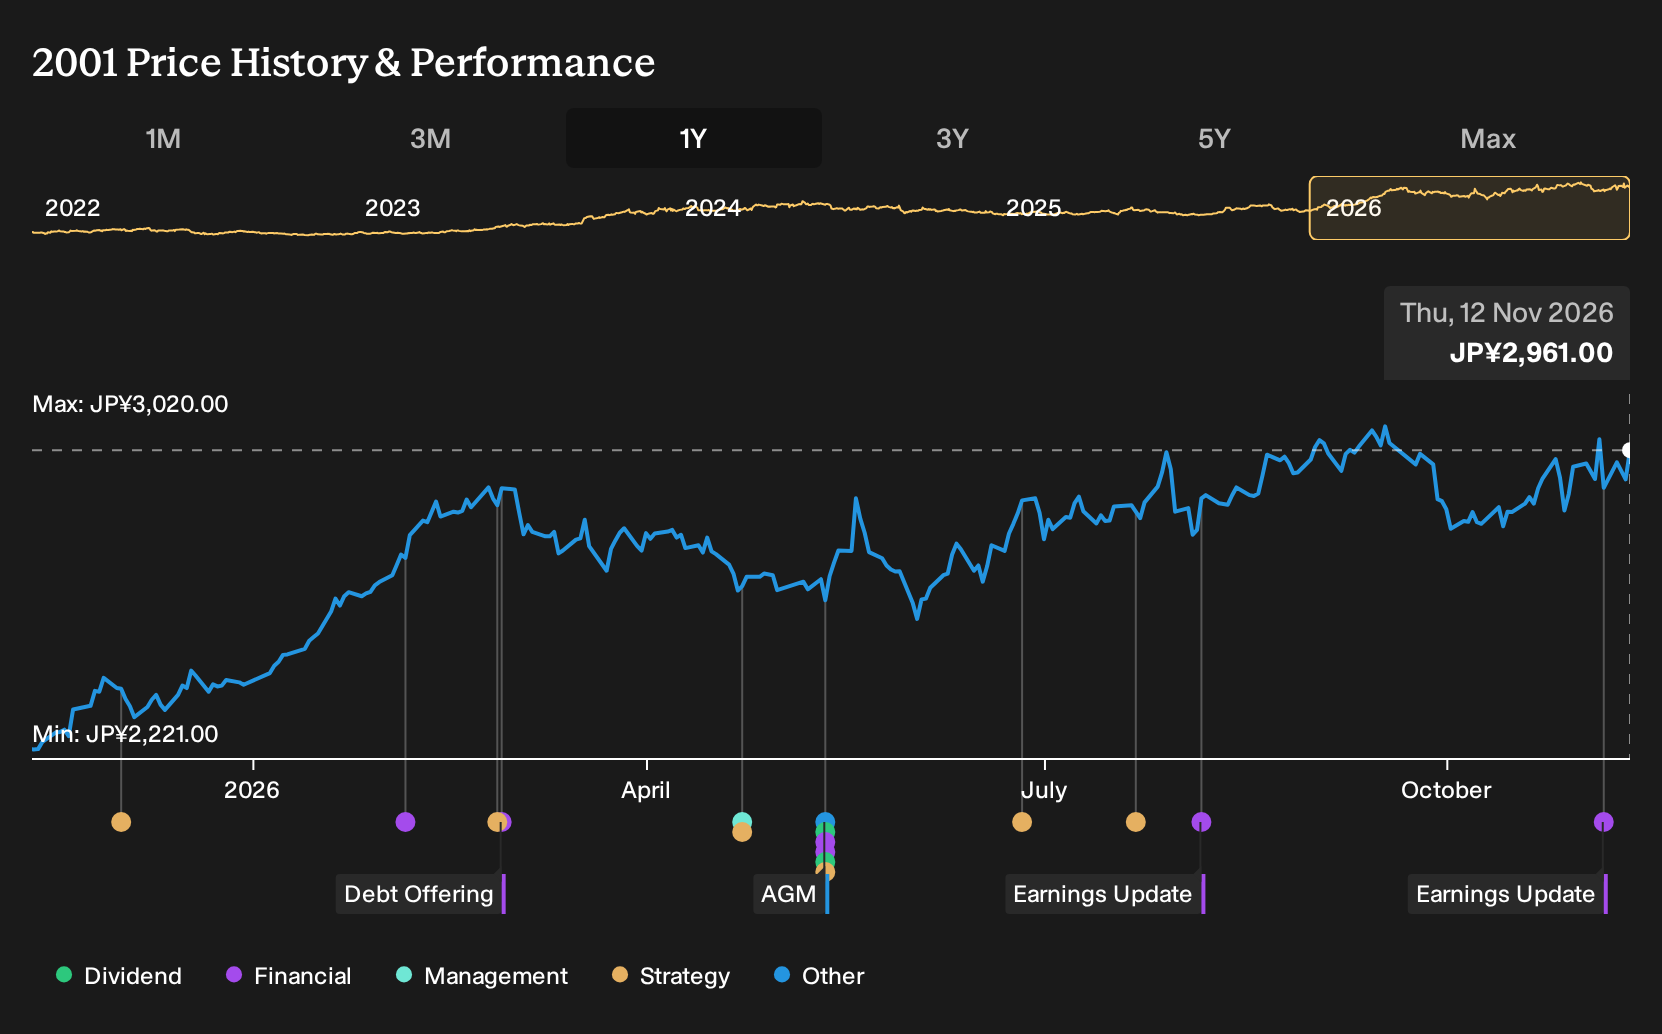
AstrisCorporateAdvisory anchors a fair value of ¥2,648 on Nippn by pairing assumed revenue growth of 3.4% a year with a future profit margin of 5.2%. Together, these figures frame what they see as a reasonable earnings power profile once current efficiency and capital structure moves settle in.
Uncover why Nippn's fair value indicates an 11% potential downside to its current price that leaves little room for error.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippn research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nippn. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippn's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nippn?
If Nippn helps you think more clearly about efficiency, balance sheets and cash generation, it can be useful to compare that story with other companies that score well on similar foundations using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan a curated set of companies through 18 high quality undervalued stocks that pair solid financial profiles with prices that may not fully reflect them.
- If income is your priority, focus on stability and yield by reviewing our 27 dividend fortresses that screens for companies with higher payouts supported by underlying fundamentals.
- If resilience matters most to you, narrow the field to businesses on our 20 resilient stocks with low risk scores that show stronger balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com