


EN
Home Depot (HD) Just Gave Investors Something To Think About
Home Depot (HD) is back in focus after reaffirming its fiscal 2026 outlook and flagging higher fuel, energy, and tariff costs, a combination that has sharpened attention on margins and cash generation.
Recent trading tells a mixed story. Home Depot’s 1 month share price return of 18.5% and 3 month gain of 2.8% point to building momentum after earlier weakness, even as the 1 year total shareholder return is down 2.7% and the 5 year total shareholder return is slightly negative.
Spot undervalued Home Depot peers facing similar housing and cost pressures by scanning our hand picked 32 high quality undervalued stocks in one place.Home Depot still looks like a powerhouse retailer, yet the share price has just sprinted almost 19% in a month. Is that strength now fairly reflected in the valuation, or has enthusiasm run ahead of the fundamentals?
Most Popular Narrative: 9.5% Undervalued
Home Depot closed at $348.26 while the leading community narrative anchors fair value at $385, which implies a valuation gap that puts the recent share price rebound under scrutiny.
According to Andrei_Niculescu, a Simply Wall St Community investor who wrote the narrative, the investment case now leans heavily on how well Home Depot executes on its Pro-focused shift and integrates recent acquisitions.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors, while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 18 investors see Home Depot as 10% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, higher fuel, energy and tariff costs could squeeze Home Depot margins, while any stumble integrating SRS and GMS could quickly chill that bullish narrative.
Find out about the key risks to this Home Depot narrative.
Another View: Home Depot Through A Cash Flow Lens
There is a different read on Home Depot when you switch from earnings multiples to our DCF model. On that view, HD at $348.26 sits above an estimated future cash flow value of $268.85, which points to an overvalued result rather than a 9.5% discount.
That gap highlights a simple question for investors: Does the earnings based fair value of $385 better capture Home Depot’s long term Pro thesis, or is the DCF signaling a concern about how much cash the retailer is realistically set to produce over time?
Look into how the SWS DCF model arrives at its fair value.
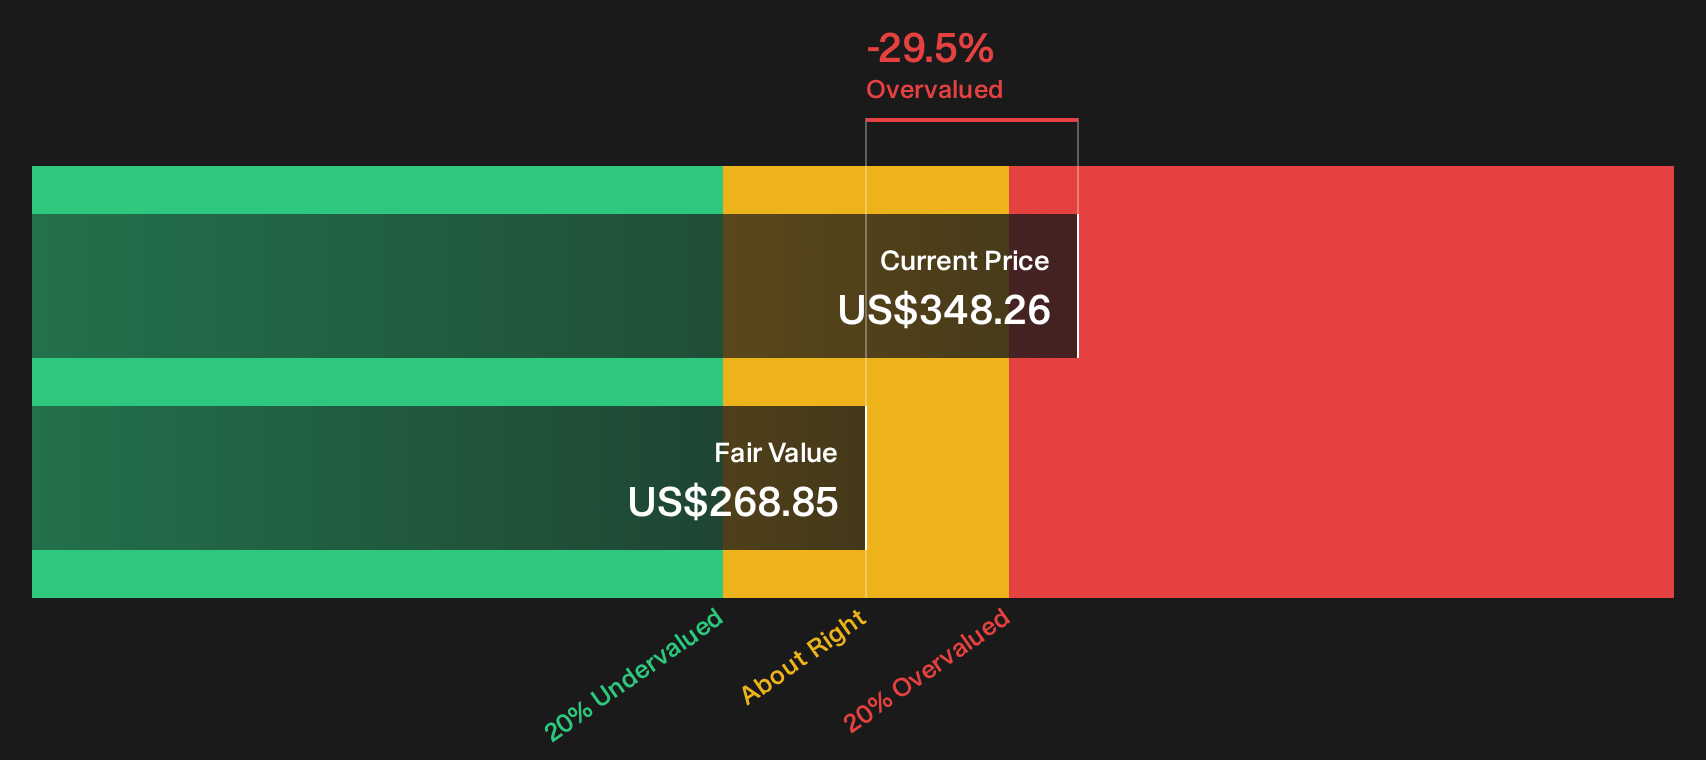
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Home Depot for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Home Depot can be confusing, so move quickly from headline takes to hard data and build your own view using our 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Home Depot?
If you stop with Home Depot, you might miss other opportunities that fit your style, so put a few minutes into scanning fresh ideas with the Simply Wall St screener.
- Target resilient income by checking companies in the 6 dividend fortresses that aim to combine higher yields with sturdier fundamentals.
- Hunt for potential mispriced opportunities through the 20 high quality undiscovered gems that highlight quality businesses the market may not be watching closely yet.
- Dial down portfolio stress by reviewing the 29 resilient stocks with low risk scores that flags stocks with lower risk scores and more robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com