


EN
Is Progress Software (PRGS) Trading At A Discount Or About Right?
Progress Software has had a mixed share price record in recent years, and the question now is whether the current US$43.44 level is properly supported by its earnings power. For anyone watching the stock, the issue is not just what the chart shows but also how the underlying profit stream lines up with that price tag.
- Over the past 3 years the stock has fallen 17.8%, which puts a spotlight on whether the earnings profile today really lines up with what shareholders are paying.
- The company’s model in infrastructure and application software leans heavily on recurring revenue and operational efficiency, which can matter a lot for how reliably profits convert into cash and how investors judge the earnings multiple.
- There is a second opinion on Progress Software worth weighing. See what analysts think Progress Software's shares could be worth.
The issue now is whether the earnings that Progress Software generates today are strong and reliable enough to justify the price investors are currently asked to pay.
If you are weighing whether Progress Software's earnings really support a US$43.44 share price, it can help to compare that question across 32 high quality undervalued stocks.
Where Does Progress Software Sit on Earnings?
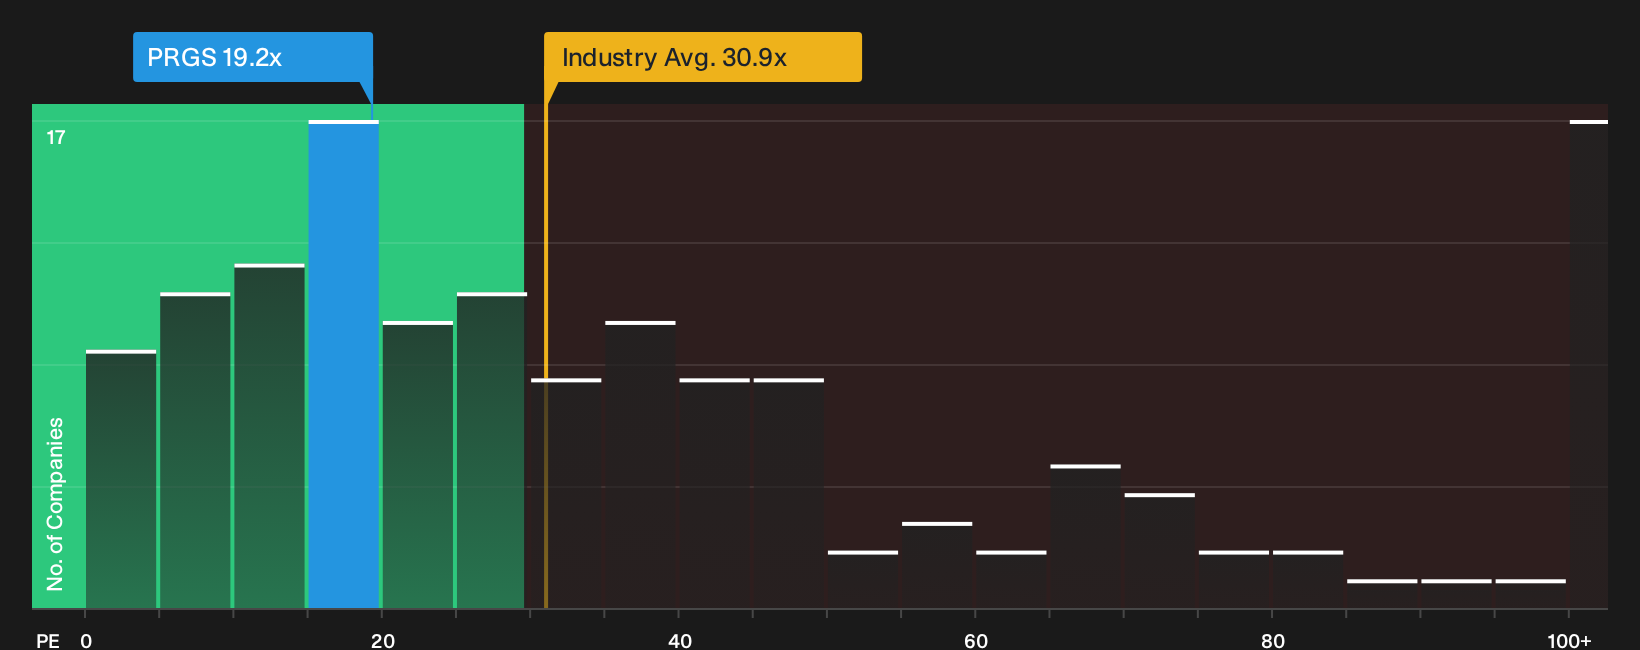
The P/E ratio suits Progress Software because earnings are a core lens investors use for recurring revenue models like this. At the current price, the stock trades on a P/E of 19.2x. The broader software industry sits closer to 30.9x, while a peer group average is much higher at about 57.5x. That gap tells you the market is attaching a lower earnings multiple to Progress Software than to many software peers.
A model that blends the company’s growth profile, margins, size and risk points to a P/E that is slightly above where the shares trade today. So the current 19.2x sits just under what that tailored yardstick would suggest for Progress Software. For anyone weighing the stock at US$43.44, the key question is whether the quality and durability of its profit stream justify the market keeping the multiple near or above that level over time. Explore the numbers behind Progress Software's P/E valuation.
The Progress Software Narrative: What Would Justify Today's Price?
Progress Software Narratives on Simply Wall St pick up where this valuation puzzle leaves off and describe which paths for growth, profitability and earnings would need to occur for the shares to appear meaningfully more expensive or cheaper than they do today. Each scenario links its figures to a specific view on how Progress Software's expansion prospects, margins and risk profile could change, giving you a reference point to return to as new information emerges about the business.
Bulls see Progress Software as underappreciated on AI and M&A execution, while bears focus on contract, margin and leverage risk around Domo.
Bull case: 23% undervalued
The analyst consensus Narrative on Simply Wall St argues that the potential upside depends on acquisitions contributing to a higher quality recurring stream.
"The main factor that has to go right is that Progress Software maintains disciplined execution on AI focused M&A and integrations so that earnings, margins and free cash flow stay aligned with its stated total growth strategy..."
Discover why this Narrative puts Progress Software at 23% undervalued.
Bear case: 9% overvalued
The bearish analyst Narrative on Simply Wall St leans on specific contract, Domo and debt risks to frame a more cautious stance.
"Although Progress Software highlights strong interest in its AI enabled data and application platforms, the seven figure termination of a government data retention contract after a court ruling shows that regulatory action can quickly remove recurring workloads from these platforms..."
Explore why this Narrative puts Progress Software at 9% overvalued.
Progress Software’s price tag is only one piece of the decision
Before you decide how Progress Software fits in your portfolio, it helps to know that our broader checks have flagged specific risk signals that deserve a closer look beside the valuation story. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com