


EN
Keurig Dr Pepper (KDP) Wraps Up $2 Billion Stock Offering Before 2027 Split
- Keurig Dr Pepper (NasdaqGS:KDP) completed a US$2b stock offering aimed at accelerating debt reduction ahead of its 2027 split.
- The equity raise is intended to support investment grade credit ratings as the group prepares to form Beverage Co. and Global Coffee Co.
- Management plans to use the new capital to lower leverage and increase financial flexibility for the two planned independent businesses.
- This US$2b equity raise for pre separation deleveraging fits into a wider picture that fresh research helps explain. Take a look at 3 warning signs (1 major) we have identified for Keurig Dr Pepper.
For readers interested in how other businesses are positioning balance sheets for resilience, it is worth scanning 29 resilient stocks with low risk scores.
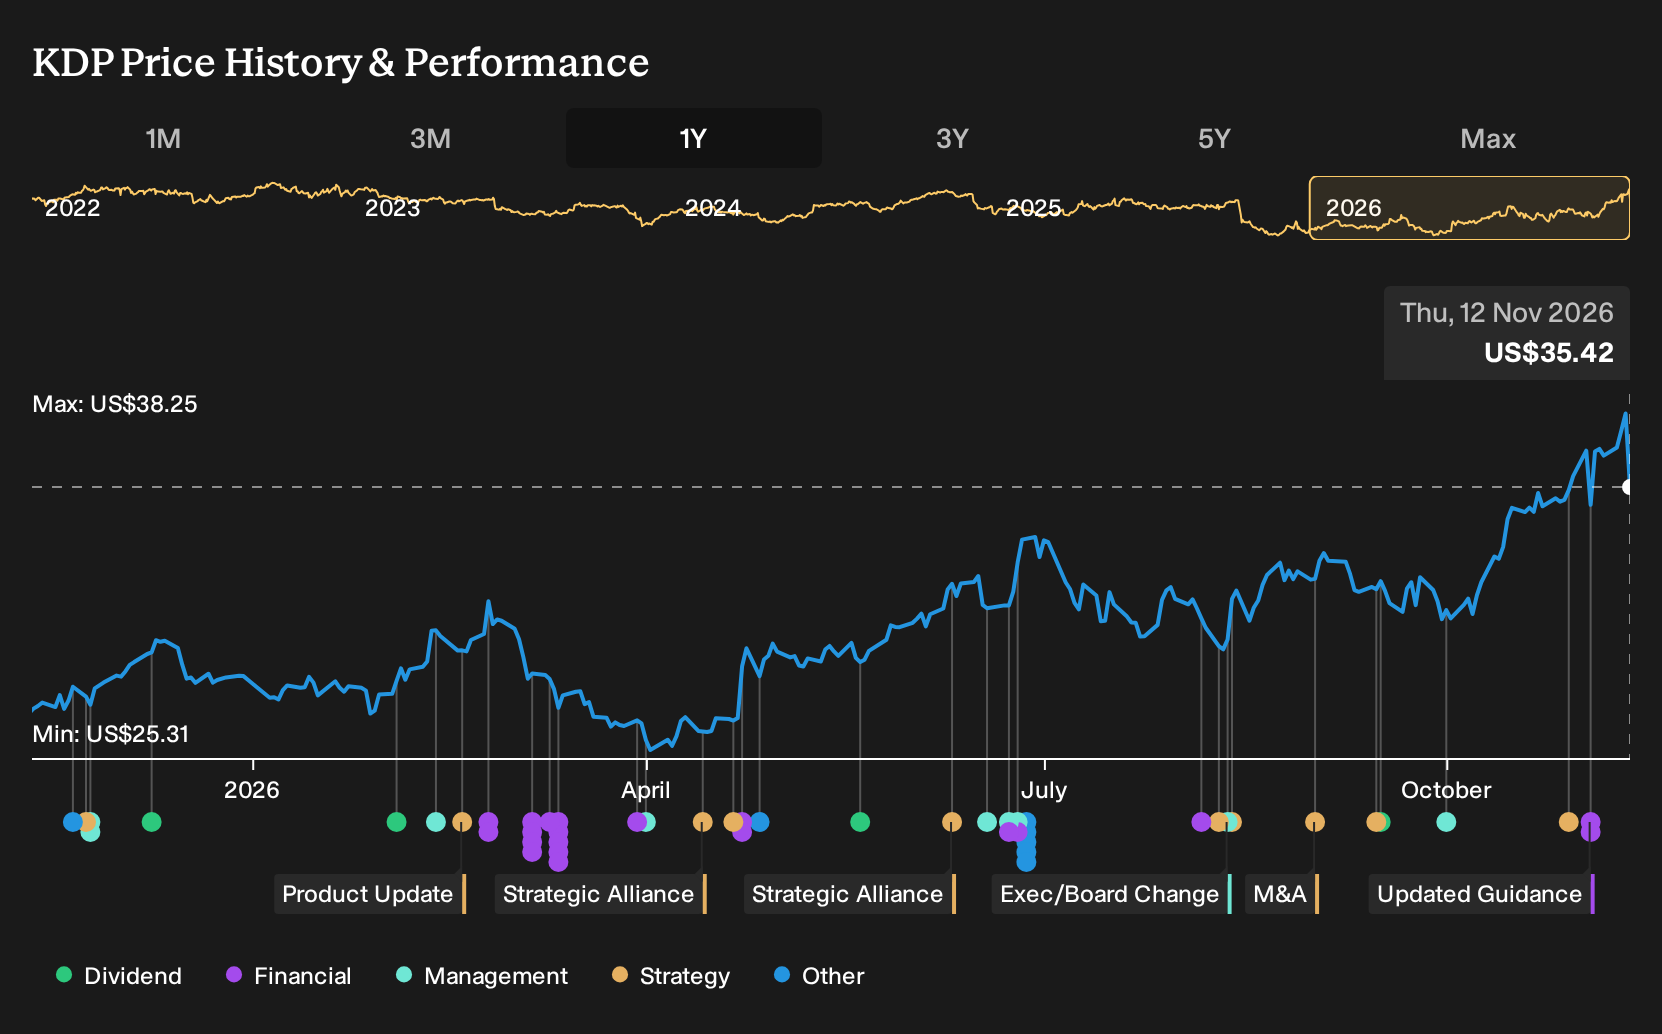
Keurig Dr Pepper runs a large beverage and single serve coffee platform, with a US$52.1b market cap that gives it scale alongside global drink producers. That size and its mix of packaged drinks and brewing systems help explain why balance sheet structure now takes center stage for the planned separation.
See which insiders are buying and selling Keurig Dr Pepper following this latest news.
What Keurig Dr Pepper’s equity raise signals about the 2027 split
The US$2b stock sale indicates Keurig Dr Pepper is prioritising balance sheet repair before the 2027 break up into Beverage Co and Global Coffee Co. That aligns directly with the Narrative catalyst that hinges on leverage coming down and debt being better supported by cash generation. Equity funding spreads that burden across shareholders rather than relying only on operating cash flow, which had been flagged as a risk area. The move therefore supports the separation story, but it also undercuts any assumption that the existing capital structure could carry both businesses into the split without fresh equity.
See how these catalysts shape Keurig Dr Pepper's path to a $36.97 fair value.
The clearest test of whether this is working will be reported leverage and debt coverage over the next few results, in particular how quickly management moves toward its targeted leverage levels in 2026 as the separation timetable for early 2027 gets closer.
One question Keurig Dr Pepper has not answered yet
Balance sheets tell only part of the story for Keurig Dr Pepper. The missing piece is who is actually calling the shots and what incentives shape their decisions. See who is actually steering Keurig Dr Pepper, and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com