


EN
YETI (YETI) Stock Seems Reasonable On A 63% Five Year Slide
YETI Holdings has seen a sharp share pullback over multiple time frames, which puts fresh focus on whether the current US$38.30 price still lines up with what its earnings can reasonably support. With the stock down over several years but roughly flat over the past year, the key issue for you is how much of the business’s earnings power is already baked into that valuation.
- Over the past 5 years the share price has fallen 63.1%, which raises the question of whether the market is reassessing what YETI’s earnings are worth.
- The business model leans heavily on branded premium products and margin quality, so any shift in pricing power or cost discipline can directly reshape how investors value each dollar of profit.
- Your read on YETI Holdings is one view; the desks covering it have another. See what analysts think YETI Holdings's shares could be worth.
The issue now is whether YETI Holdings’ current share price is appropriately anchored to the earnings the business is generating today.
If you want to stress test whether YETI Holdings’ earnings-based valuation question applies elsewhere, compare it with 32 high quality undervalued stocks for broader context.
Where Does YETI Holdings Sit on Earnings?
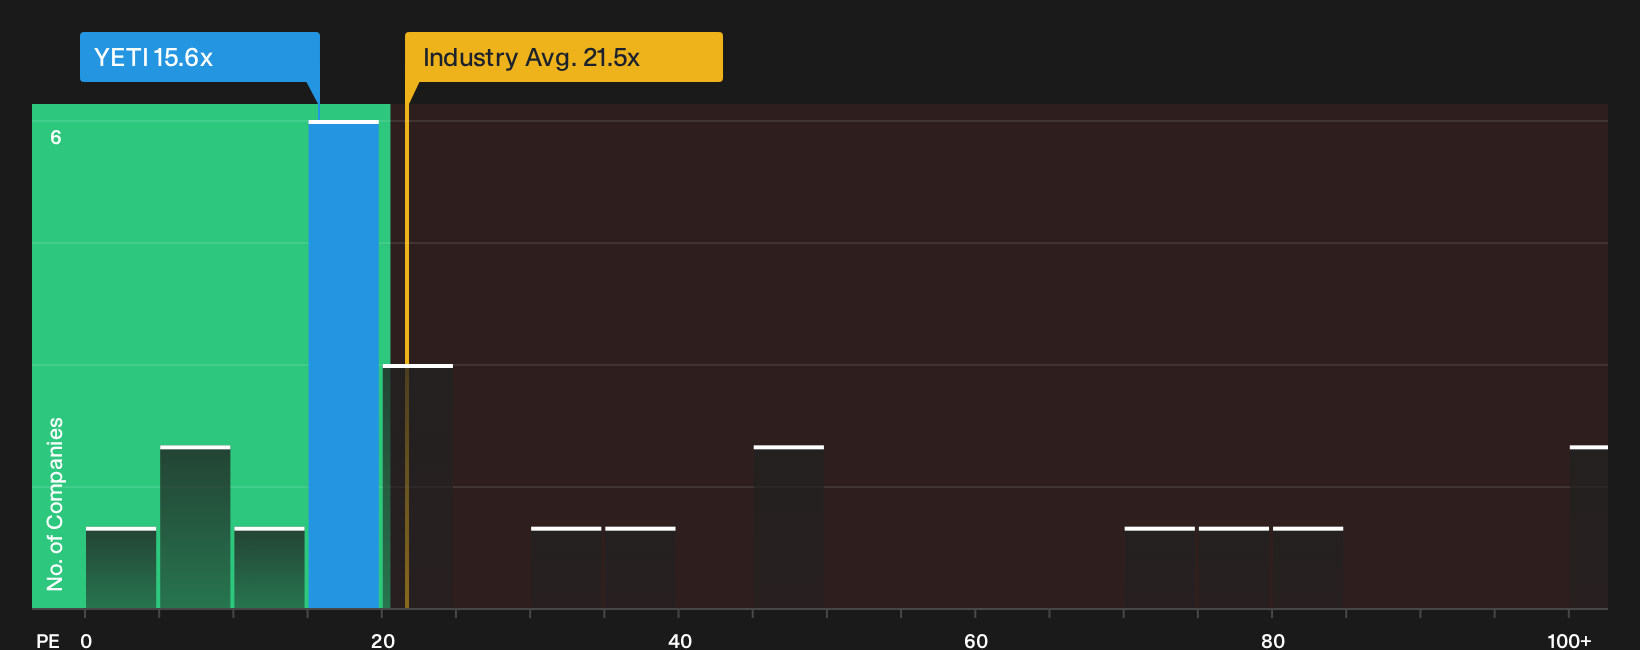
The P/E ratio fits YETI Holdings well because investors watch closely how much they are paying for each dollar of branded consumer earnings. Right now the stock trades on roughly 15.6x earnings, which sits below the Leisure industry average of about 17.6x and also under the peer group near 17.5x. That indicates the market is applying a lighter earnings tag to YETI than to many comparable consumer leisure stocks.
A fair multiple for YETI Holdings based on its own profile of growth prospects, profitability and risk appears close to where the shares trade today, so the market price is broadly aligned with what this tailored yardstick implies. Rather than a clear bargain or obvious premium, the current P/E invites investors to consider how durable YETI’s brand strength and margins may be over time and how comfortable they are with paying a mid-teens earnings tag for that profile. Explore the numbers behind YETI Holdings's P/E valuation.
The YETI Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for YETI Holdings leaves off and explain which expectations on growth, profitability and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than today’s price. Each narrative links its figures to a clear view on how YETI Holdings' growth, profitability and risk profile might evolve, which you can revisit as fresh information is released.
One of the top narratives on YETI Holdings: 30% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Project Upcycle, which is pursuing US$100 million of productivity savings across cost of goods and SG&A through dozens of active projects, together with raised 2026 gross and operating margin guidance..."
Discover why this Narrative puts YETI Holdings at 30% undervalued.
Before acting on YETI Holdings' valuation, there is one more piece to check
Price tags on earnings only tell part of the story, because the people directing YETI Holdings and how they are rewarded can strongly influence how that profit story unfolds over time. See who runs YETI Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com