


EN
Kraft Heinz (KHC) Moves To NYSE And Sets Out 2029 Growth Roadmap
- Kraft Heinz (NYSE:KHC) has shifted its primary stock listing from Nasdaq to the New York Stock Exchange.
- At a recent Investor Day, management outlined a multi-year business plan and financial roadmap running through 2029.
- The updated outlook included new long term growth targets and operational milestones intended to guide investors over the coming years.
- The listing transfer to the NYSE and the 2029 roadmap are only part of the Kraft Heinz story investors now need to weigh. Take a look at 2 warning signs we have identified for Kraft Heinz.
This consumer staples giant is not the only player tied to steady cash flows and income-focused portfolios, so it is worth comparing it with 6 dividend fortresses.
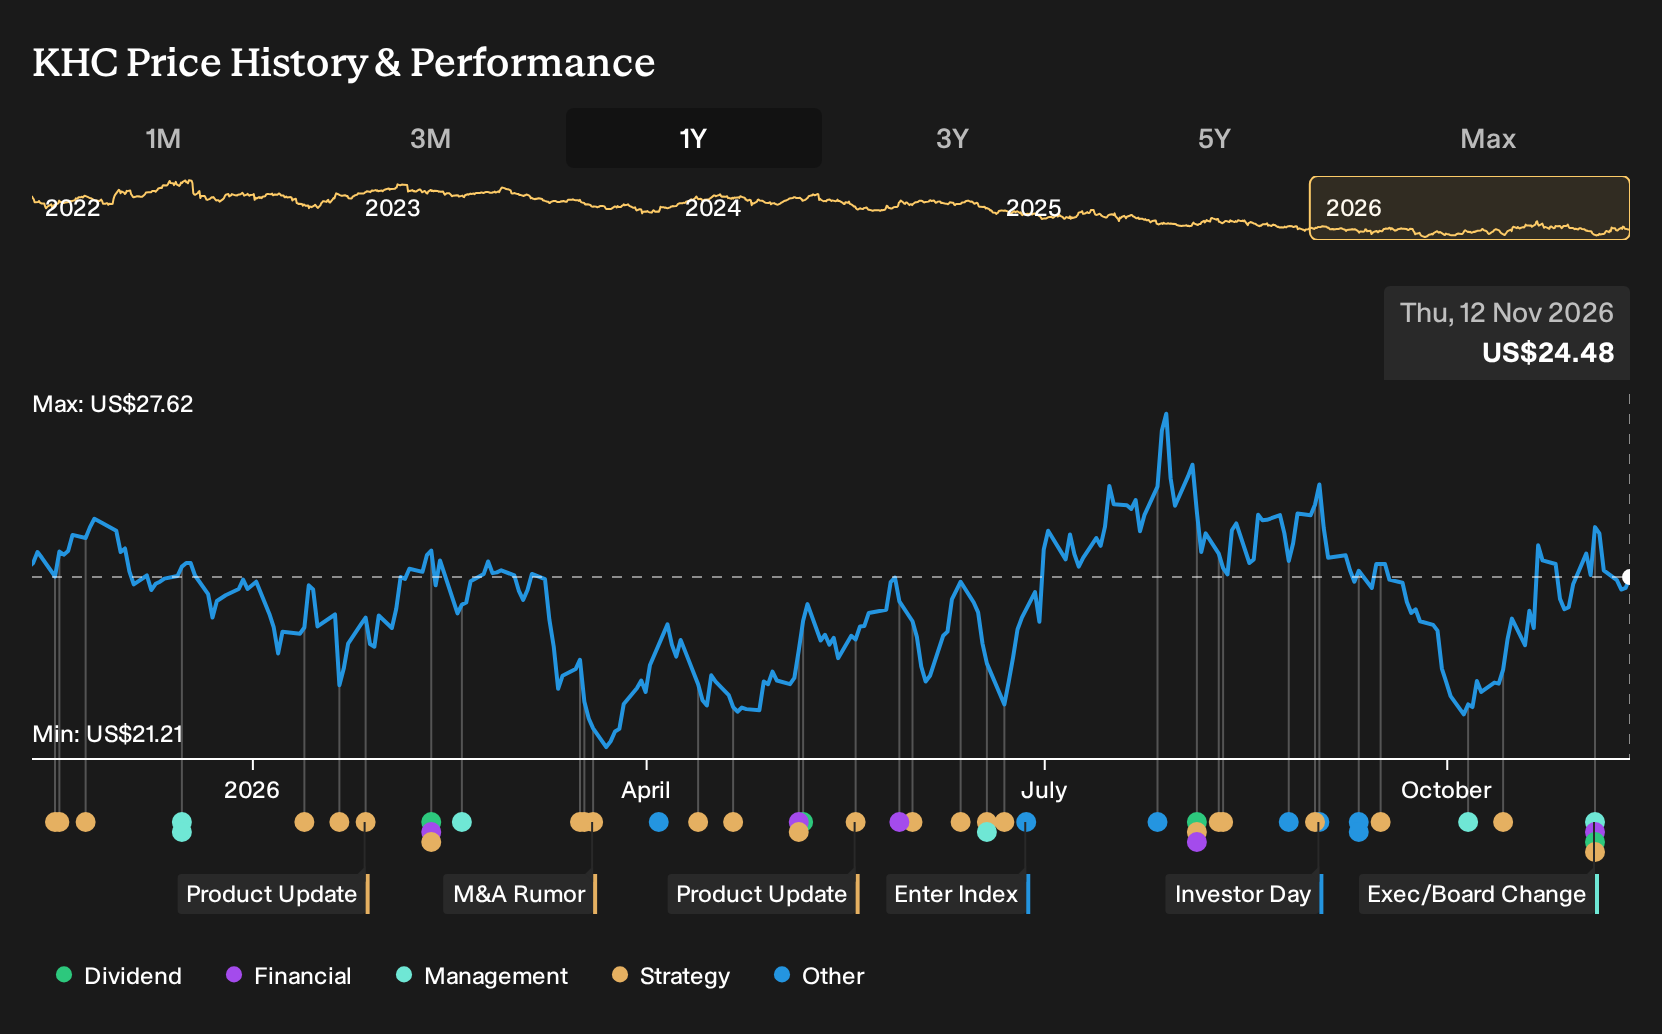
Kraft Heinz, a US based food manufacturer with a market value of about $28.7b, sells packaged meals and beverages across North America and international markets, so any long range plan or listing shift affects a wide mix of pantry staples that many households already buy regularly.
What Kraft Heinz’s NYSE move and long-term plan really test
For Kraft Heinz investors, the listing shift to the NYSE and the detailed 2029 roadmap both lean on the same core catalyst from the current Narrative. Management is doubling down on its plan to turn US$700 million of extra brand spending and ongoing productivity savings into steadier, volume led growth while keeping margins resilient. Hosting Investor Day at the NYSE and spelling out multi year milestones signals confidence in that reinvestment playbook rather than a change in direction. It also raises the bar on execution risk around flat near term organic sales and GLP 1 related volume pressure.
See how these catalysts shape Kraft Heinz's path to a $24.81 fair value.
The cleanest early read on whether this is working sits in the next couple of years of organic net sales trends and operating margin progress against guidance, especially in North America retail, where analysts already expect revenue to stay relatively flat and margin improvement to carry the story into 2029.
One more Kraft Heinz question that could matter more than today’s headlines
Short term storylines only go so far. Analyst models already sketch out where Kraft Heinz could be a few years from now, and those projections point to an outcome that today’s updates barely hint at. See where analysts expect Kraft Heinz to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com