


EN
Camden National (CAC) Stock Looks Fully Priced After A 94% Run
Camden National has delivered a strong multi year share price run, and the question now is whether the current valuation is properly anchored to what the bank is earning today. With the stock near recent highs, the key issue is how much of its earnings power is already reflected in that US$59.31 share price.
- Over the past 3 years the stock has returned about 94.5%, which puts real pressure on the earnings story to justify how far the price has come.
- Recent profit margins have improved alongside growing loan pipelines and investment in digital and AI platforms, which can support expectations that Camden National may sustain or build on its current earnings base.
- There is a second opinion on Camden National worth weighing. See what analysts think Camden National's shares could be worth.
The issue now is whether Camden National's present share price is aligned with what its current earnings suggest it should be worth.
If you want to test the same earnings based valuation question you are asking of Camden National across a wider field, scan through 32 high quality undervalued stocks.
Where Does Camden National Sit on Earnings?
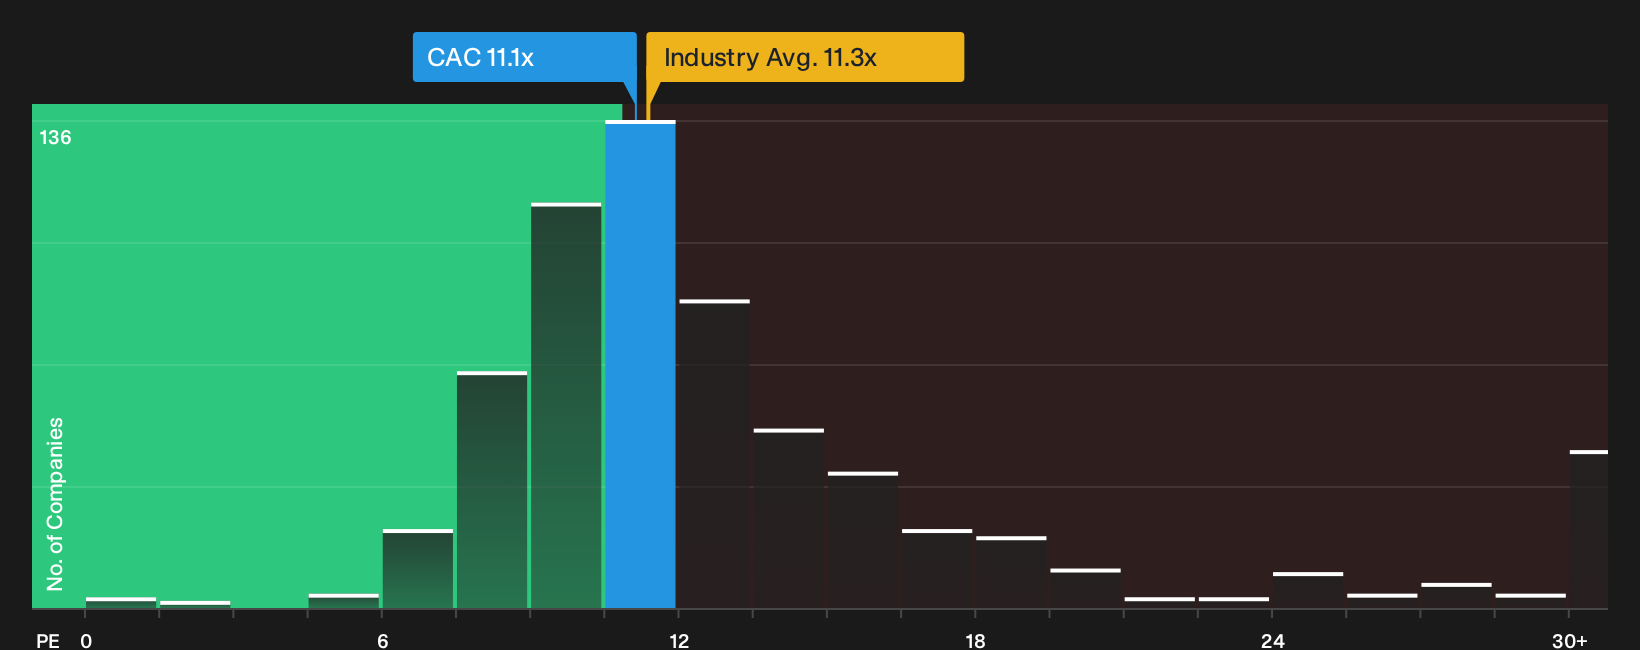
P/E fits Camden National because earnings are a key value anchor for a profitable regional bank. On this lens, the stock trades on a P/E of 11.1x. That sits slightly below the Banks sector average of 11.3x and just under the peer group on 11.5x, so the share price does not look stretched against straightforward benchmarks.
The valuation model that blends Camden National’s growth profile, margins, size and risk points to a P/E that is very close to where the shares change hands today. Because Q3 2026 results highlighted stronger net interest income and firmer profitability, the current multiple suggests investors are pricing in that progress but not assigning a large premium to it. On this framework, the earnings multiple leaves Camden National looking broadly in line with what its fundamentals support. Explore the numbers behind Camden National's P/E valuation.
The Camden National Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Camden National leaves off and explain which paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Each scenario connects its figures to a clear view on how Camden National's future expansion, margin profile and risk picture might evolve, which you can then test against new information over time.
One of the top narratives on Camden National: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Camden National continues to grow fee-based wealth and brokerage income while maintaining disciplined credit and capital management..."
Discover why this Narrative puts Camden National at roughly fairly valued.
One more check for Camden National sits with who is steering it
Price and earnings only tell part of the story, because the people setting priorities at Camden National and how they are rewarded can heavily shape what happens next for shareholders. See who runs Camden National and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com