


EN
What Korn Ferry (KFY)'s Leadership Training Boom Means For Shareholders
- Korn Ferry has been cited as a key provider in a global leadership development services market that researchers expect to expand through 2030, supported by investment in AI guided coaching, hybrid leadership models, and continuous upskilling.
- The attention on Korn Ferry within this growing training and development arena highlights how its mix of consulting, assessments, and workforce tools aligns with clients seeking ongoing leadership pipelines rather than one off programs.
- This article examines how Korn Ferry's investment narrative is affected by its role in the expanding leadership development services market.
Scan beyond Korn Ferry to compare how other leadership and training specialists are positioned in this theme using our curated list of list of solid balance sheet and fundamentals (23 results).
Korn Ferry Investment Narrative Recap
Korn Ferry investors need to believe the move toward consulting, digital tools, and workforce solutions can turn its US$3.5b contracted backlog, including AMS, into steadier earnings. The recent focus on global leadership development aligns with that pitch, but it does not change the near term story on its own.
The closest short term swing factor is still execution on large Workforce Solutions and AMS engagements, and how quickly those contracts convert into recognized revenue and cash. The biggest risk remains integration and debt from the AMS deal, including whether the targeted US$140m adjusted EBITDA run rate is achieved on schedule.
The analyst consensus narrative on Simply Wall St leans heavily on AMS and Workforce Solutions as the operational hinge. That view highlights Korn Ferry’s guidance for AMS adjusted EBITDA to lift from roughly US$100m to US$140m within about a year of closing, alongside expectations for higher consolidated EBITDA margins.
For this leadership development news to matter financially, it needs to show up in that Workforce Solutions engine through new contracts, better pricing on assessments, or further uptake of the Talent Suite and AI enabled tools. Any sign that backlog tied to these offerings is taking longer to implement or margin uplift is slower than expected would cut against those catalysts.
Korn Ferry's narrative projects US$4.4b revenue and US$388.9m earnings by 2029. This assumes 14.6% yearly revenue growth and an earnings increase of roughly US$112.7m from US$276.2m today.
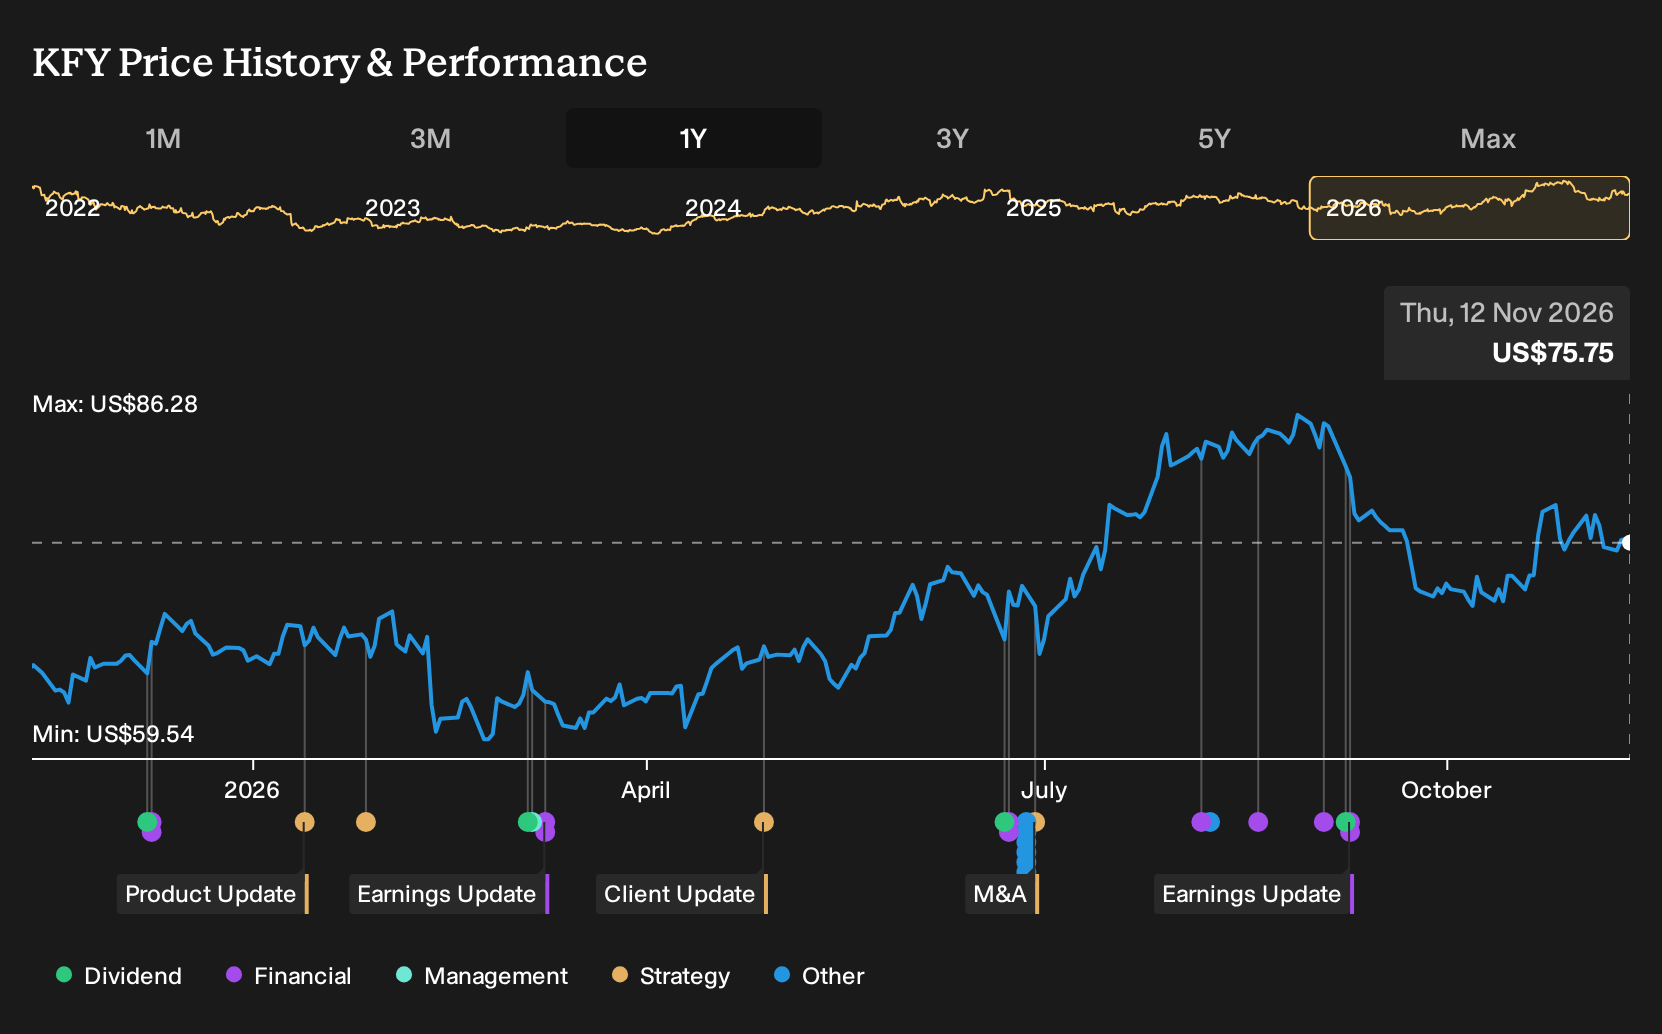
Uncover why Korn Ferry's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$62 to almost US$188 per share, which is a wide gap for the same Korn Ferry stock. That spread reflects how differently private investors treat AMS integration risk, consulting demand, and the leadership development tailwind. Use it as a cue to compare several viewpoints before deciding your own stance.
Explore 3 other Korn Ferry fair value estimates, including one that suggests as much as 148% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Korn Ferry research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Korn Ferry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Korn Ferry's overall financial health at a glance.
Looking For More Investment Ideas Beyond Korn Ferry?
Once you have formed a view on Korn Ferry, widen the field. Comparing it with other opportunities can help you stress test your thesis and spot alternatives that better match your risk tolerance and income needs.
- For investors who want quality and value together, scan a curated pool of financially disciplined businesses through the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, review companies flagged as having more resilient characteristics using the 29 resilient stocks with low risk scores.
- When the goal is income plus robustness, focus on dependable payers with stronger fundamentals by checking the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com