


EN
ADT (ADT) Pulled 2026 Guidance, Is The Stock Now Too Pricey?
Why ADT stock is back in focus
ADT (ADT) pulled its 2026 earnings guidance on November 3, the same day it released third quarter results and updated investors on buybacks. This has put fresh attention on what the stock’s current price reflects.
ADT’s recent news has driven a sharp rise in its share price, with a 30 day share price return of 49.9% building on a 23.5% year to date gain and a 3 year total shareholder return of 75.7%. This suggests that investors are rapidly repricing both its prospects and its risks.
Scan how other companies with momentum are being priced by running the curated 32 high quality undervalued stocks alongside ADT’s recent move.
ADT just pulled its 2026 earnings targets while the share price raced toward the pending US$10.00 offer. Is this surge about the underlying business, or a mood swing in how the market values it?
Most Popular Narrative: 20% Overvalued
ADT last closed at $9.89, while the most followed narrative on Simply Wall St assigns it a fair value of $8.21. This frames the recent surge as pricing in more optimism than that view supports. According to AndrewHabib, a Simply Wall St Community investor who wrote the narrative, the key question is whether the market is overpaying for dependable cash flows in a heavily leveraged business.
Valuation Margin of Safety: At ~7.5x forward earnings and a TEV/EBITDA under 5x, the terminal decline narrative is already fully priced in. The downside risk is cushioned by the ~3.3% dividend yield and management's willingness to execute concurrent share repurchases.
See why 1 investors see ADT as 20% overvalued.
Result: Fair Value of $8.21 (OVERVALUED)
Still, the narrative hinges on two pressure points: ADT's heavy debt load in a higher rate world, and the risk that its DIY pivot fails to gain traction.
Find out about the key risks to this ADT narrative.
Another View: ADT Through A P/E Lens
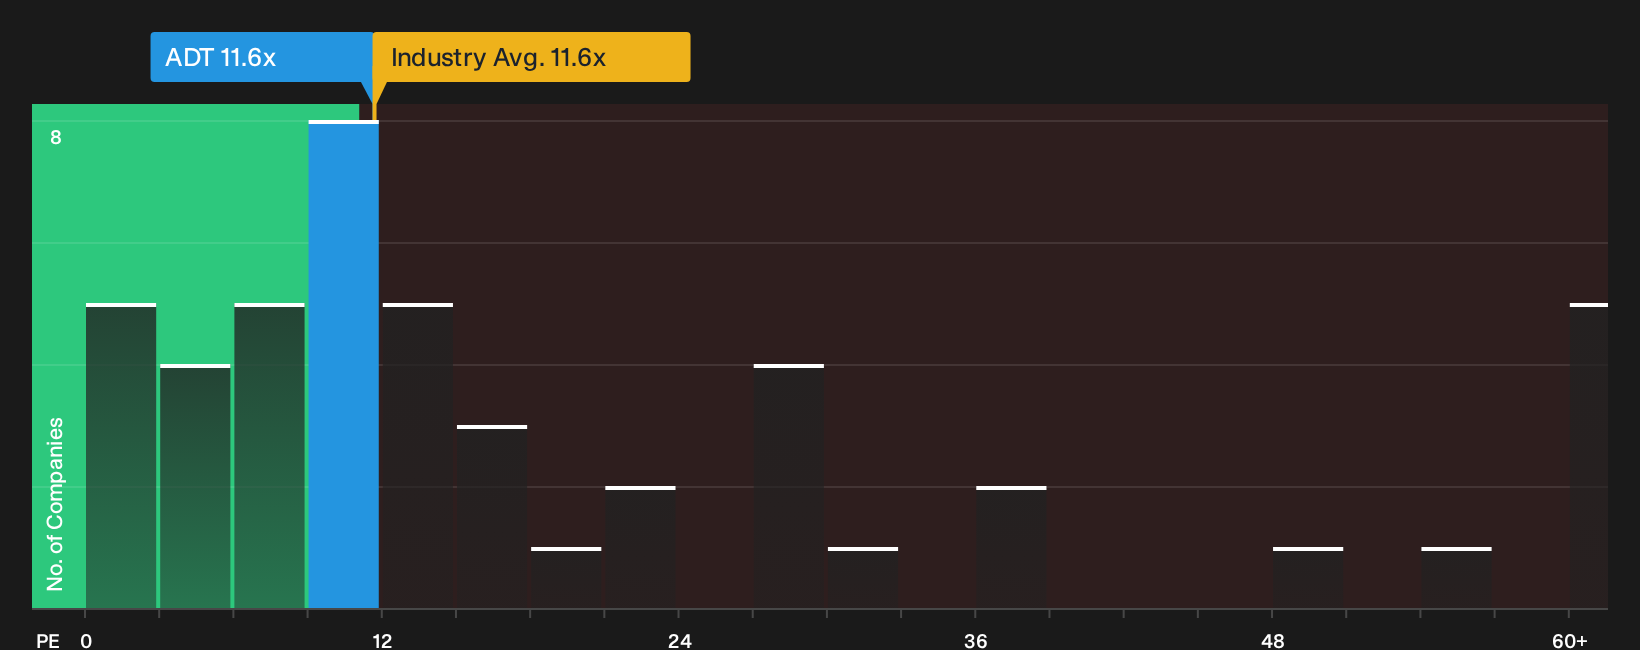
That fair value of $8.21 paints ADT as 20% overvalued, yet the share price tells a different story when you look at earnings multiples. At $9.89, ADT trades on a P/E of 11.6x, which sits below both peers at 21.4x and the US Consumer Services industry at 11.8x. The fair ratio points to 18.2x, raising the question of whether the market might eventually price the stock closer to that level. For an investor trying to reconcile these signals, the key issue is whether the current discount reflects hidden problems or a potential opportunity that would require a clear catalyst.
To stress test that P/E view against the underlying business drivers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the cross currents in sentiment around ADT feel strong, treat that as a cue to move quickly and test the data yourself. One streamlined way to weigh both the upside arguments and the concerns is to review the 2 key rewards and 1 important warning sign.
Looking for more ADT-sized investment ideas?
Do not stop your research with ADT. Broaden your watchlist using focused stock lists so you can spot opportunities before they become crowded trades.
- Hunt for mispriced potential by scanning a curated pool of 32 high quality undervalued stocks that pair solid fundamentals with appealing valuations.
- Strengthen the income side of your portfolio by reviewing 6 dividend fortresses that aim to combine higher yields with resilience.
- Dial down portfolio stress by filtering for 29 resilient stocks with low risk scores that our models flag with more robust risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com