


EN
What Stadler Rail Buyers Were Betting On
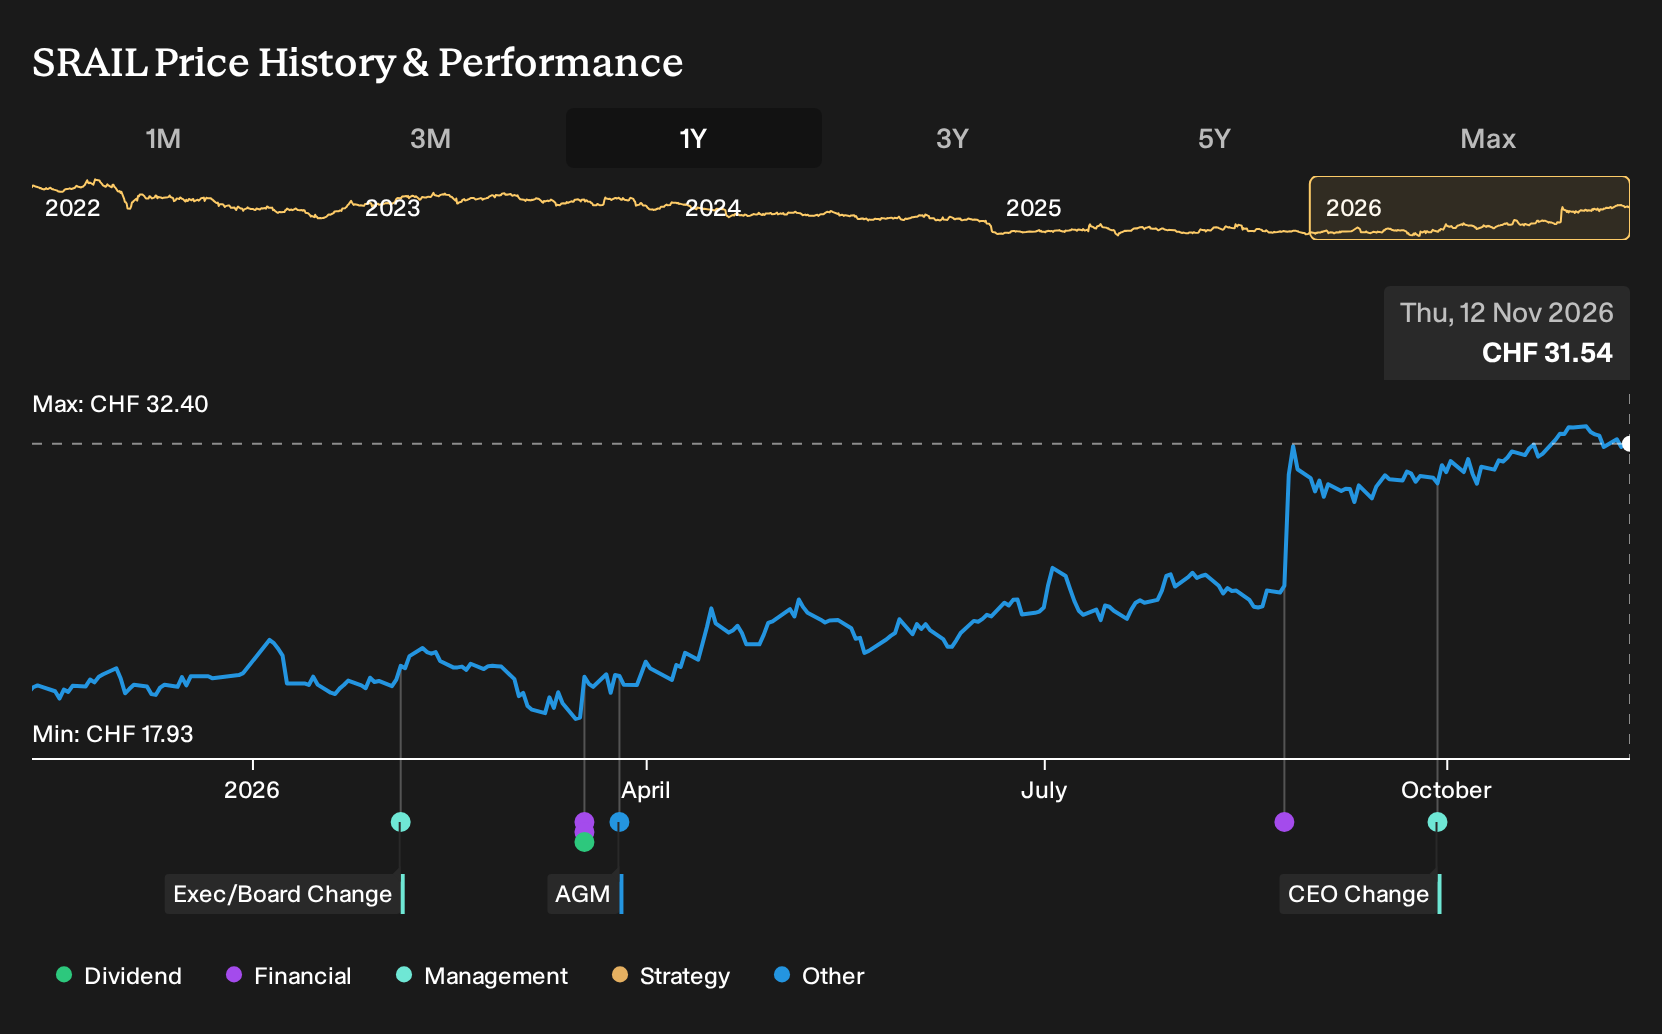
If Stadler Rail sat on your watchlist instead of in your portfolio, this past year may feel like a missed shot. Holding Stadler Rail over the past year would have returned 64.4%, including dividends. At first glance that result seems far removed from dry debates in late 2025 about order backlogs, green propulsion and how fast margins might scale. If revenue growth and profit margin expansion were the key assumptions on record, what exactly should have stood out?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Stadler Rail. Zero in on 193 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Stadler Rail Investors Were Weighing
The shares cost CHF19.5 at the start of the period, and anyone looking at Stadler Rail then had two very different stories on the table.
On the optimistic side, one narrative saw Fair Value at CHF26.7, or 37% above the start price, built on revenue growth assumptions of 22.4% and profit margins reaching 5.8% within three years.
The more cautious view put Fair Value at CHF18.0, or 8% below the start price, and rested on lower 15.0% revenue growth assumptions and margins rising to 3.9%, with protectionism and public budget pressure as key risks.
What The Results Changed For Stadler Rail
The clearest fresh fact was Stadler Rail’s H1 2026 performance. Revenue reached CHF1,965.3m and net income came in at CHF34.4m, with net margin at 1.7% versus 1.2% in H1 2025. That shift in profitability supported the optimistic case on margins, while the still low margin level kept the cautious view alive. The evidence cut both ways.
The lesson is to watch which lever a thesis really hangs on. If the story is about margin uplift, track net income and net margin in each report and check whether they are moving toward the narrative’s target or stalling.
What Stadler Rail's Current Price Already Assumes
Stadler Rail now trades at CHF31.54, well above the CHF19.5 start price over the past year. The bearish analyst narrative on Simply Wall St still places its fair value below that market level, framing today’s tag as one that already assumes clean execution.
A buyer at this price is effectively assuming the CHF32.3b backlog turns into higher quality revenue and EBIT. The key question is how the flagged supplier disruptions and German productivity work influence that conversion.
"The main requirement is that Stadler Rail executes its large CHF 32.3b order backlog according to plan, while restoring margins at the flood-affected Spanish plants and improving productivity in Germany without relying on unusually high down payments. The numbers imply that the share price already reflects successful delivery of revenue significantly above CHF 5b with an EBIT margin above 5% in 2026, as well as progress toward the medium-term 6% to 8% target, which leaves limited room for disappointment."
The price and this Narrative do not agree. → Uncover what this Narrative says Stadler Rail is actually worth
Looking One Step Beyond Stadler Rail
Stadler Rail turns major transport orders into working fleets across busy routes. When you see that kind of backlog, your thoughts shift to the systems underneath.
Rail cars and stations increasingly share challenges with planes and satellites in service. They all need trusted control systems, secure communication links and resilient electronics.
Another industrial heavyweight concentrates on those layers for defence, aviation, space and digital security needs. It helps customers protect data, guide assets and keep critical hardware talking reliably.
As rail and public transport rely more on connected technology, that kind of specialist seems less like a side player and more like essential infrastructure in its own right.
One Narrative has put that dependency into a written case. → See the robotics company one Narrative values 28% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com