


EN
SiTime (SITM), What Is Behind The Fresh Attention?
SiTime earnings spark fresh interest in the stock
SiTime (SITM) is back in focus after third quarter results showed US$298.67 million in sales and a return to positive net income, reversing losses from the same period last year.
Recent trading tells a mixed story. After a sharp 32.6% 7 day share price gain, SiTime remains down 18.8% on a 30 day share price basis and 33.9% over 90 days. At the same time, the 1 year total shareholder return of 63% and 3 year total shareholder return above 3x signal that long term holders have seen substantial value creation.
Scan similar semiconductor stories breaking out on earnings strength by reviewing the hand picked 20 high quality undiscovered gems that share SiTime style fundamentals and momentum triggers.
SiTime now trades well below the average analyst target even after that sharp rebound, which leaves one issue on the table: Is this a discount that misjudges the earnings turn, or a warning the market has right?
Most Popular Narrative: 43% Undervalued
Against SiTime’s last close at $470.55, the analyst consensus Narrative on Simply Wall St anchors fair value at $832.27. This frames today’s price as a steep discount before you even factor in the growth assumptions behind it.
The numbers imply that the current valuation prices SiTime as if its timing TAM nearly doubles by 2030, its run-rate moves toward around US$1.2b of annual revenue, and elevated profitability levels are maintained, which this narrative views as supportive of a bullish stance on the shares.
See why 16 investors see SiTime as 43% undervalued.
Result: Fair Value of $832.27 (UNDERVALUED)
Still, the bullish SiTime story leans heavily on AI data center demand and smooth integration of the Renesas timing assets, and either pressure point could upset that script.
Find out about the key risks to this SiTime narrative.
Another View on SiTime’s valuation
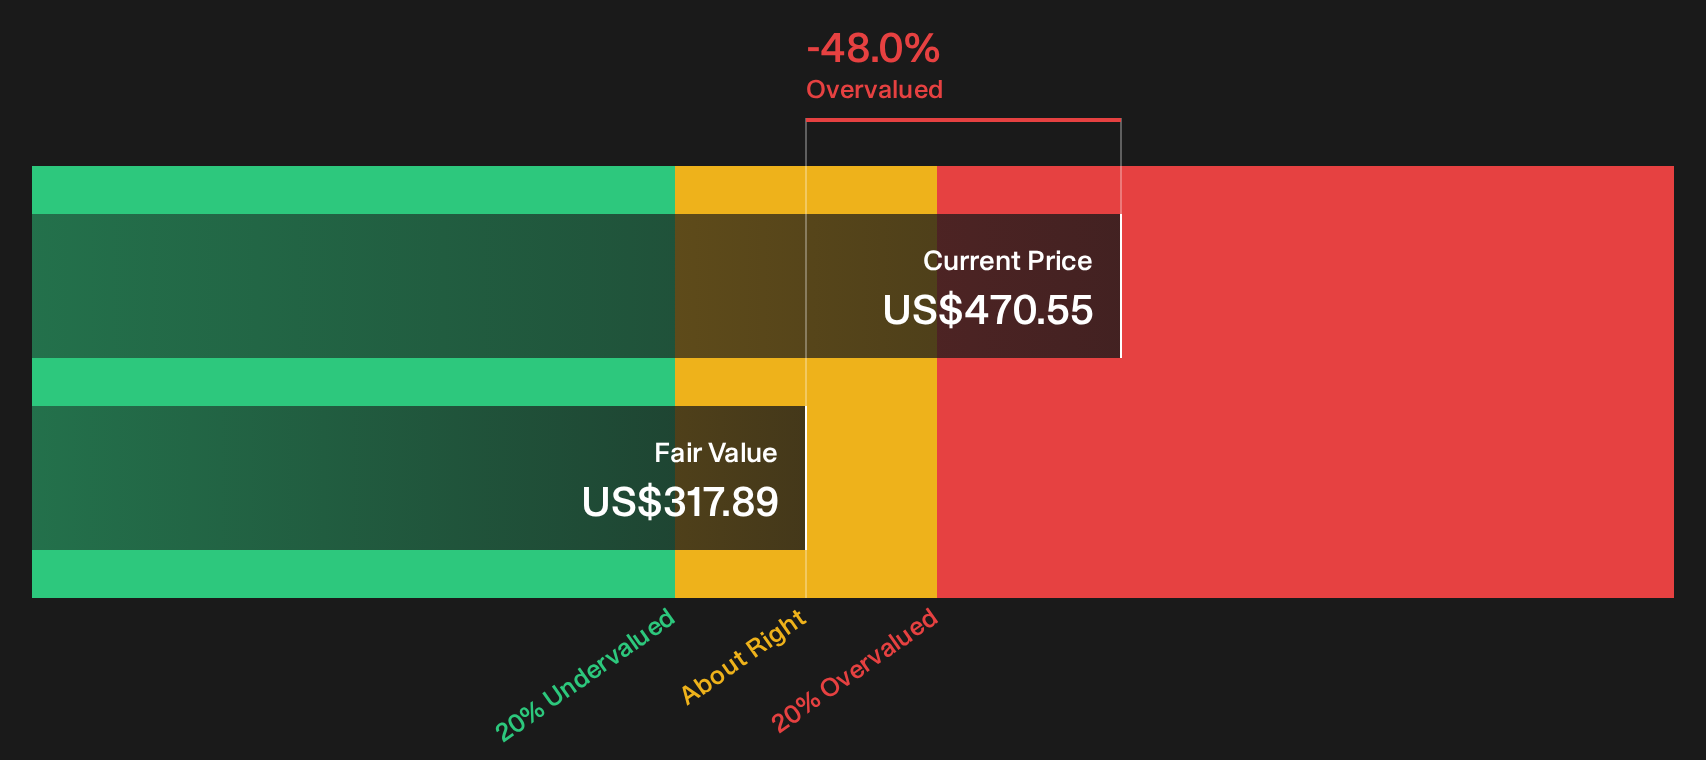
The Simply Wall St DCF model tells a very different story for SiTime. On that framework, the estimated future cash flow value sits at $317.89, compared with the current share price of $470.55. That points to SiTime trading at a premium on cash flow terms, so which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of enthusiasm and caution around SiTime feels familiar, that is exactly why it helps to move fast and interrogate the numbers yourself. Put the recent earnings, valuation gap, and shifting sentiment in context by weighing 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SiTime?
SiTime might be your starting point, but widening the opportunity set with a few targeted screens can reveal stocks that better match your preferred mix of risk and quality.
- Target resilient compounding potential by scanning a curated 29 resilient stocks with low risk scores that keeps volatility and financial red flags firmly in check.
- Prioritise balance sheet strength by reviewing a focused list of solid balance sheet and fundamentals (23 results) that surfaces businesses with room to absorb shocks and keep investing.
- Hunt for overlooked potential by working through a hand picked 11 elite penny stocks with strong financials where financials already stack up more robustly than the share prices suggest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com