


EN
Computacenter And 2 British Owner Operator Stocks To Watch
Rising bond yields linked to persistent US inflation have pushed investors to rethink how they handle interest rate risk. Central banks can move quickly, but corporate decision makers often move earlier, committing capital long before policy shifts are obvious. Founder-led UK companies sit in that gap, where personal ownership and long-term vision can matter most. This article highlights three founder-driven stocks from this universe that may merit closer examination.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally tied to long term outcomes. However, if you want the absolute best, these 9 top founder-led companies are the cream of the crop.
Computacenter (LSE:CCC)
Overview: Computacenter provides IT procurement, managed services, and support to large corporate and public sector clients across the UK, Europe, and North America, under long-serving leadership with meaningful insider ownership.
Operations: Computacenter generates about £12.1b from Computer Services, with major revenue coming from the United States, the UK, Germany, and Western Europe.
Market Cap: £5.2b
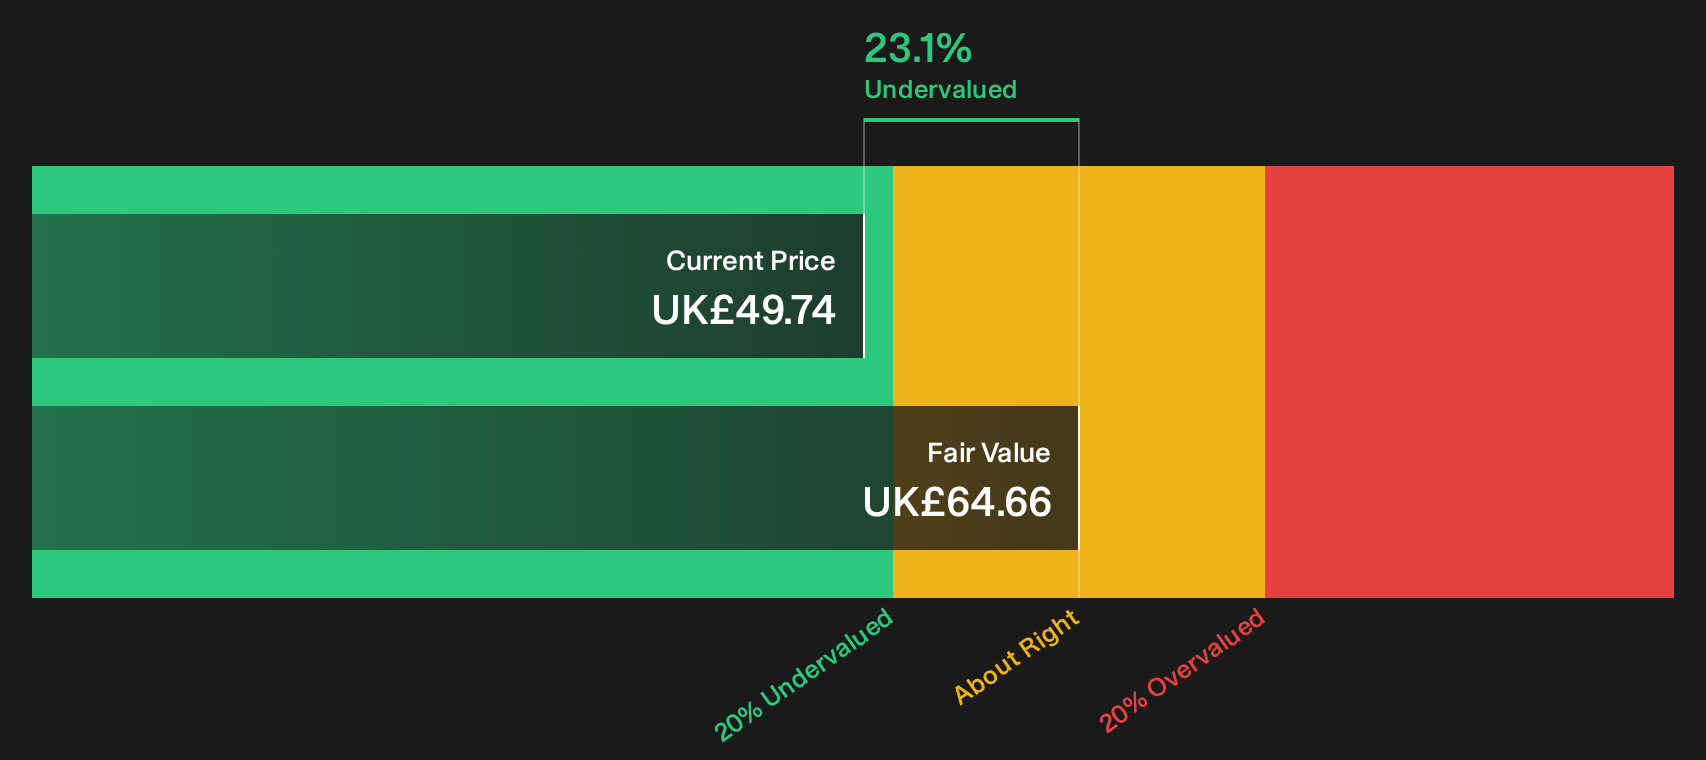
Investors looking at founder-led traits get something slightly different with Computacenter. Leadership tenure averages more than a decade, the board blends continuity with independence, and insiders still hold a significant stake. That long-term orientation aligns with a large multi-year order backlog and record product pipeline, but the key question is how one less visible pressure will influence future margins and capital allocation decisions.
Those quieter pressures sit in the background while you weigh the DCF valuation analysis for Computacenter, where long contracts and insider skin in the game may be telling a different story.
Applied Nutrition (LSE:APN)
Overview: Applied Nutrition manufactures and sells founder-led sports nutrition and wellness products under its own brands to consumers in the UK and internationally.
Operations: Applied Nutrition generates about £134 million from manufacturing and selling sports nutrition products, with roughly equal revenue from the UK and overseas markets.
Market Cap: £760 million
Applied Nutrition fits the Founder-Led Companies theme because the same executives who built the Applied Nutrition, ABE, BodyFuel and Endurance brands still shape product development, marketing and distribution. The analyst Narrative on Simply Wall St references that hands-on leadership to explain why its growth potential and cash profile could matter for long term holders.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk."
What happens to that founder-led edge will likely depend on how one capacity and distribution decision filters through to future margins and demand.
That trade off is exactly what the full narrative for Applied Nutrition unpacks, as it tests whether Applied Nutrition’s growth engine is accelerating or masking brewing pressure.

Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages infrastructure and founder-focused private equity funds, providing growth capital and buyout financing while partnering closely with business leaders.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, largely sourced from UK clients.
Market Cap: £518 million
Foresight Group Holdings matters for this Founder-Led Companies screen because its whole model is built around backing owner-operators directly. The bullish analyst Narrative on Simply Wall St argues that this partnership approach is now colliding with a much clearer growth runway.
"Acceleration in real assets deployment into energy transition projects, supported by a near doubling of deployment in the most recent year and over £3.6b of identified future deployment rights in international mandates, gives Foresight Group Holdings room to turn existing pipelines into higher management fees and potentially stronger EBITDA growth as those commitments are drawn."
What happens if a single assumption about how quickly those fee-rich mandates convert into cash flow shifts even slightly will matter a lot.
Small shifts in that timing can matter a lot, and the full narrative for Foresight Group Holdings shows where Foresight Group Holdings could see fee growth accelerate or stall next.

Seeking Alternatives Before The Crowd?
Fresh ideas do not stay under the radar for long. Breakout stories build momentum while prices move. Use these curated shortlists before information gets stale and act now.
- Spot income workhorses built on sturdy cash generation with the 5 dividend fortresses and see which high-yield payers may help keep portfolios from getting caught flat-footed.
- Ride structural demand in electrification by scanning the 16 top copper producer stocks where producers tied to critical infrastructure upgrades could move well before headlines catch up.
- Track early winners supplying AI’s plumbing through the 53 AI infrastructure stocks so potential breakout enablers of data centers and chips are on your radar while it matters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com