


EN
How Half Year Earnings Will Impact JustSystems Stock (TSE:4686)
- JustSystems Corporation reported half year earnings for the period ended September 30, 2026, with sales of ¥25,481 million, net income of ¥8,793 million, and basic earnings per share from continuing operations of ¥136.92.
- The combination of sizeable sales and net income in this half year update provides investors with a clearer view of JustSystems' current earnings power and business scale.
- Next, the focus shifts to how JustSystems' reported half year net income fits into the broader investment narrative that investors are building around the company.
What Is JustSystems' Investment Narrative?
To own JustSystems, you need to be comfortable with a fairly simple earnings story. This is a software group selling language input tools, e learning services and data platforms, and the latest half year numbers show it can turn ¥25,481 million of sales into ¥8,793 million of profit. That level of profitability, together with net margins previously reported at 30.5%, suggests an operation that does not look especially capital heavy. The fresh figures fit into a longer record of earnings growth of 4.4% a year over 5 years and 11.4% in the latest year.
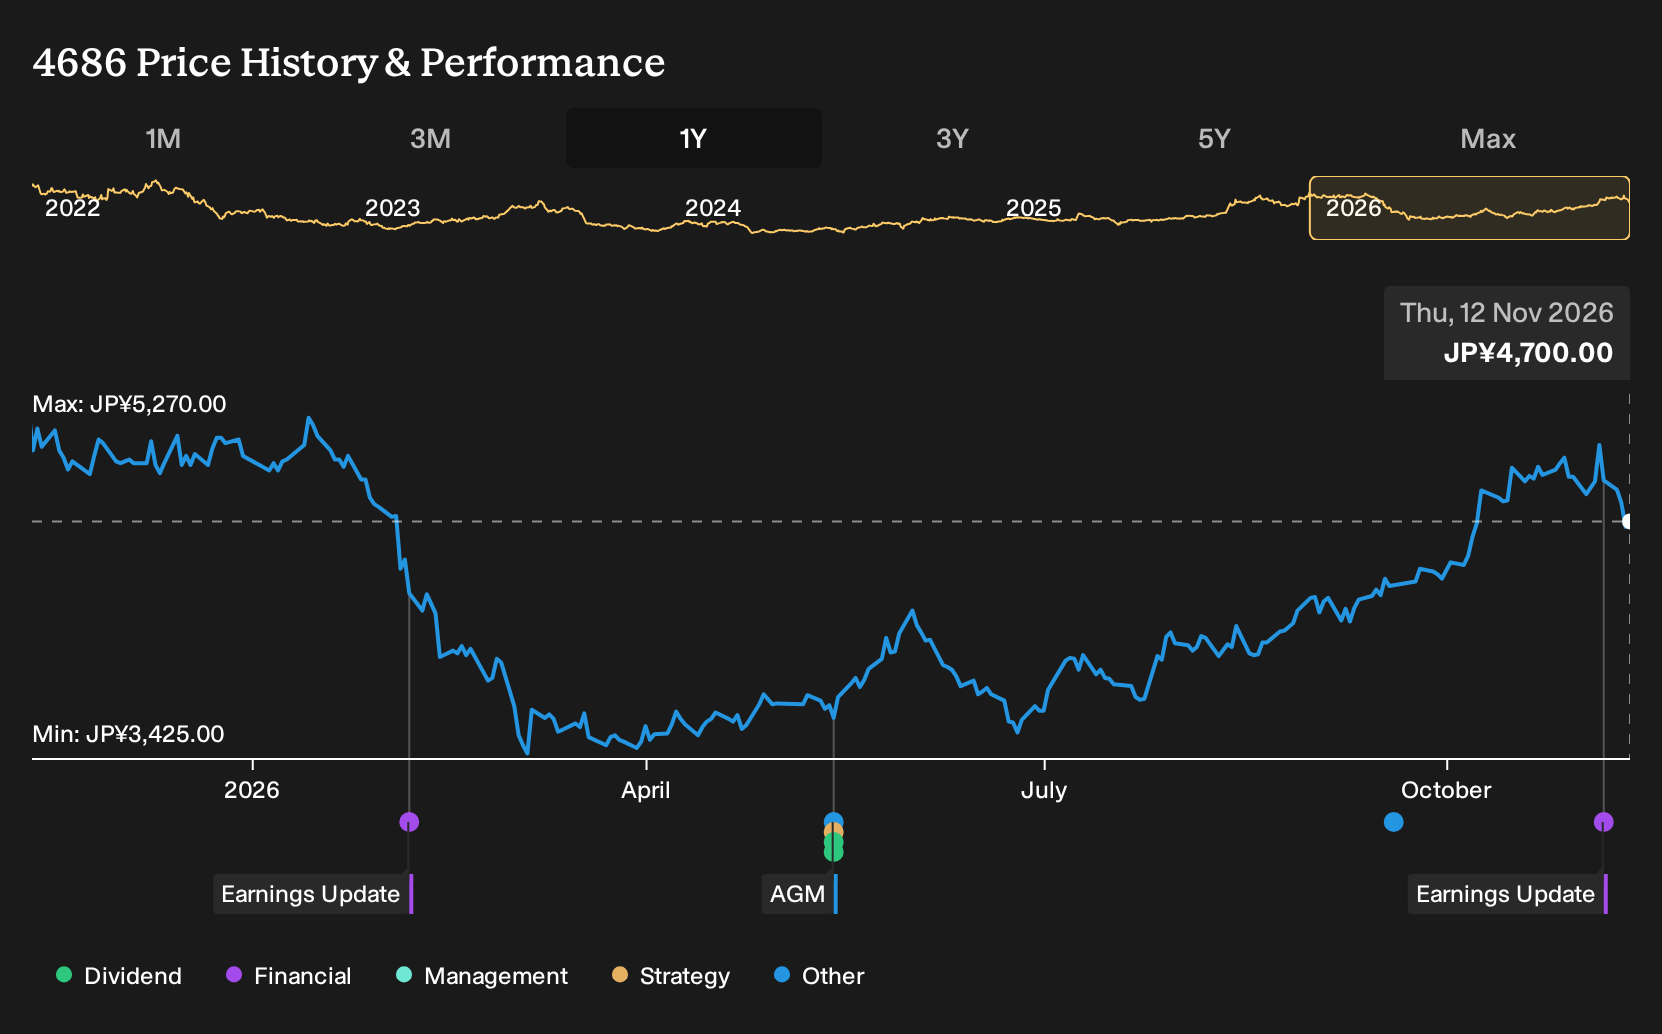
In the short term, the key swing factors are likely to be demand for its education and enterprise products, pricing discipline and how much of that profit converts into cash, given the flagged high level of non cash earnings. The stock recently traded at ¥4,700, which is 0.6% below one estimate of future cash flow value, and on a P/E of 19.4x that appears cheaper than some peers but more expensive than the broader JP software group. Returns have been mixed, with the share price falling 9.1% over 1 year and trailing both the market and sector, so this earnings update may not remove the main overhang that has kept enthusiasm in check.
Even so, there is a structural issue inside JustSystems' profit profile that deserves closer attention before leaning too hard into this story.
There's only one way to know the right time to buy, sell or hold JustSystems. Head to Simply Wall St's company report for the latest analysis of JustSystems's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JustSystems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JustSystems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JustSystems' overall financial health at a glance.
Looking For More Investment Ideas Beyond JustSystems?
If you want to put JustSystems in context, it helps to compare it with other listed businesses that share some of its financial traits. The Simply Wall St Screener lets you do exactly that in a structured way, so you can quickly line up alternatives that fit the type of risk and return profile you are aiming for.
- If you care most about quality at a reasonable price, line up companies that currently look mispriced on fundamentals by reviewing our 18 high quality undervalued stocks.
- If resilience matters more to you than rapid gains, focus on businesses with stronger balance sheets and lower financial risk by checking the list of solid balance sheet and fundamentals (25 results).
- If you are trying to keep volatility in check, narrow your search to companies that our models flag with steadier risk profiles through the 20 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com