


EN
Learn Why The Bull Case For Salzgitter Stock Could Change Following Earnings Recovery
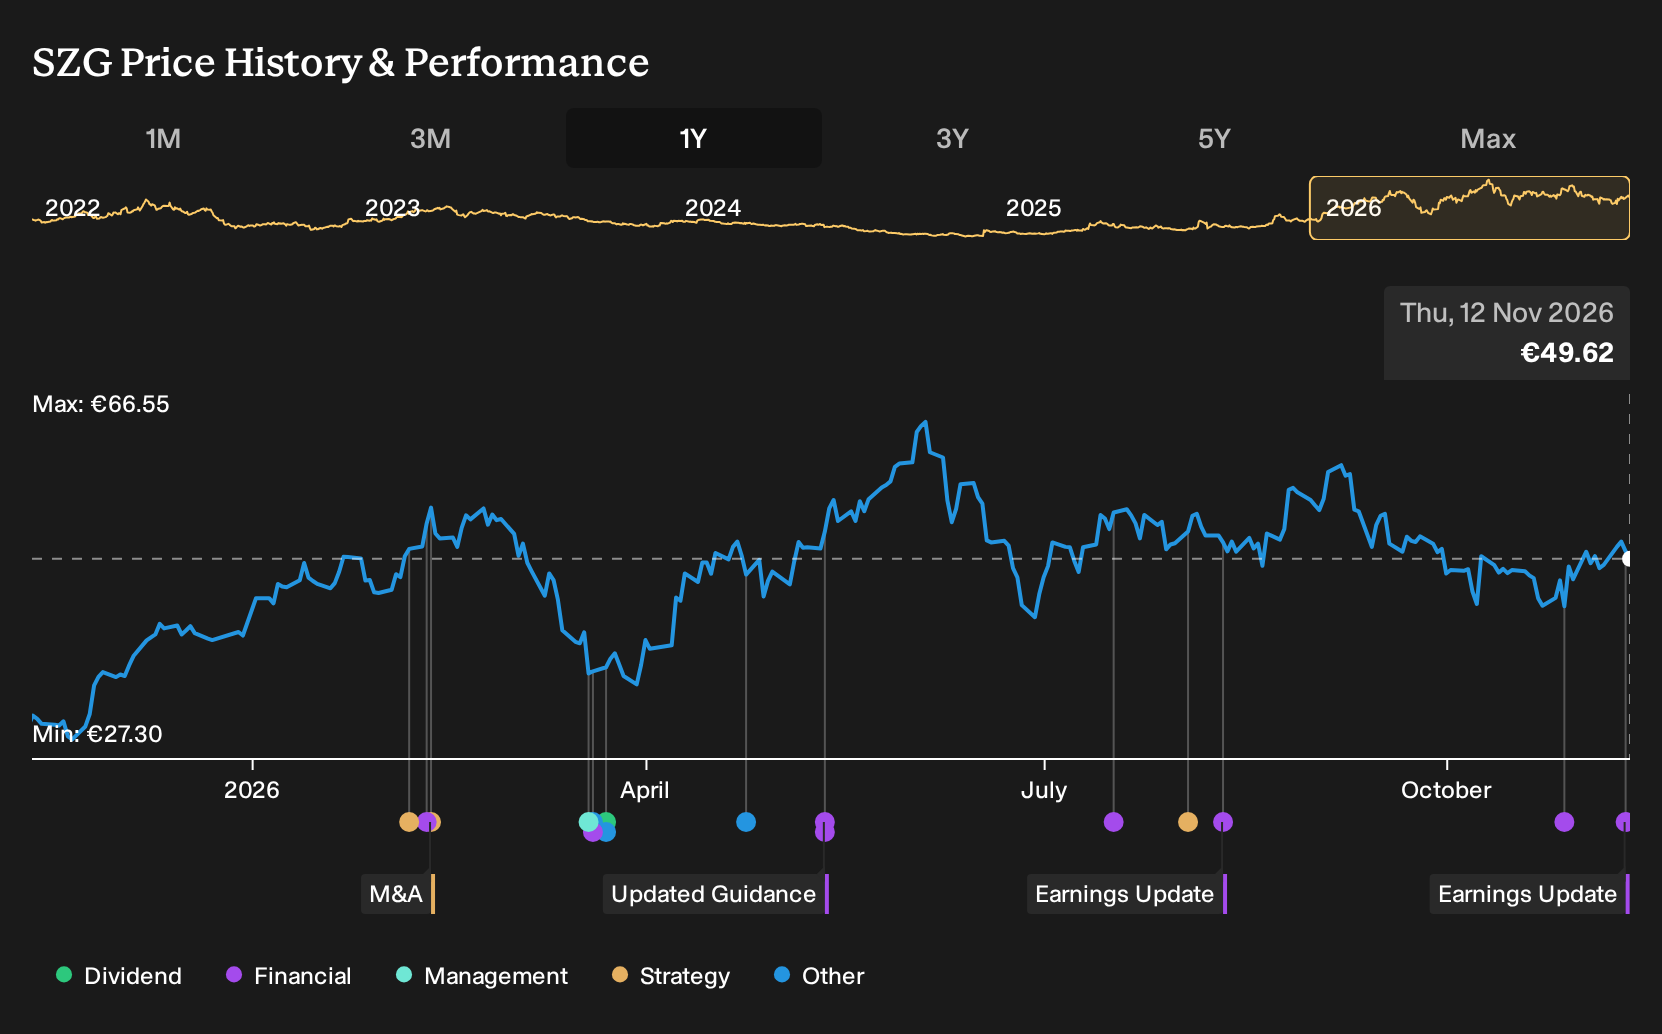
- Salzgitter AG reported third quarter 2026 sales of €2,741.8 million and net income of €131.4 million, with basic earnings per share from continuing operations at €2.35, compared with €0.75 for the same period in 2025.
- Over the first nine months of 2026, the group moved from a net loss to net income of €171.7 million, which gives investors fresh context for Salzgitter’s decarbonisation projects, cost program and broader transformation agenda.
- We will now look at how Salzgitter's stronger nine month net income reshapes the investment narrative built around its transformation plan.
Salzgitter Investment Narrative Recap
To own Salzgitter, you need to believe the earnings recovery can coexist with heavy decarbonisation spending and a still muted European steel cycle. The latest quarter shows the group producing positive net income again, which supports that idea, but it does not remove demand risk from weak German GDP forecasts or subdued project business.
In the short term, the key swing factor remains whether the P28 savings, SALCOS build out and HKM integration can keep cash generation healthy as transformation capex rises toward the expected 2027 peak. The main threat is that funding support or cash inflows lag those commitments and squeeze free cash flow and net debt.
The analyst consensus narrative on Simply Wall St hinges on decarbonisation projects, P28 efficiencies and EU trade tools such as CBAM supporting earnings over time. The latest quarterly report, with €171.7 million of net income over nine months after a loss a year earlier, provides more operating evidence for that storyline without resolving the structural demand question.
For you as a shareholder, this update ties directly into the SALCOS Phase 1 build and HKM transformation that are expected to require net capex likely above €800 million around 2027. Stronger profitability improves flexibility to fund that program, but the risk remains that weaker steel demand or any softening of EU safeguards could still pressure pricing and future margins.
Salzgitter's current analyst storyline points to €11.2b in revenue and €436.5 million in earnings by 2029, based on forecasts that the top line will expand by 8.0% a year and that profit will rise from €57.0 million today to the projected level, which is an earnings increase of about 7.7x from the current base.
Uncover why Salzgitter's fair value indicates a 37% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
Some of the most optimistic analysts frame SALCOS and HKM execution as the real catalyst, rather than short term earnings timing. Before this Q3 update, they were modelling revenue of about €13.7b and earnings of roughly €915.7 million by 2029. That is far above consensus, and it shows how sharply views on Salzgitter can differ. Use this result as a prompt to compare those pre news assumptions with your own expectations and explore where you sit on that spectrum.
Explore 2 other Salzgitter fair value estimates, including one that suggests as much as 55% above the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Salzgitter research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Salzgitter. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Salzgitter's overall financial health at a glance.
Looking For More Investment Ideas Beyond Salzgitter?
Once you have formed a view on Salzgitter, it can help to compare that thesis with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a structured way to do that, using the same data driven framework you have just applied here.
- If you want steadier businesses with conservative risk profiles, take a look at 205 resilient stocks with low risk scores that may suit a more defensive approach.
- For investors who like to back quality at a discount, scan through 193 high quality undervalued stocks that align strong fundamentals with more modest pricing.
- If your focus is on fast growing small caps with potential for bigger swings, review 126 elite penny stocks with strong financials that match your risk tolerance and time horizon.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com