


EN
EverCommerce (EVCM), What Is Behind The Fresh Attention?
EverCommerce (EVCM) just put fresh numbers on the table, with third quarter and nine month 2026 earnings out alongside full year revenue guidance that could reshape how investors think about the stock.
The fresh earnings release lands against a weak share price backdrop, with EverCommerce’s stock down 39.57% on a year to date share price basis and the 1 year total shareholder return declining 19.95%, even after a 1 day share price gain of 1.45% to US$6.98. Recent 7 day and 30 day share price returns, down 16.41% and 26.29% respectively, suggest momentum has been fading. At the same time, the 3 year total shareholder return falling 13.08% and 5 year total shareholder return declining 60.92% point to a longer reset in how investors are pricing the business, which this new 2026 revenue guidance is now helping to test.
Scan beyond EverCommerce and compare this reset in sentiment with our hand-picked 32 high quality undervalued stocks, which also pair subdued share prices with solid fundamentals.
EverCommerce now trades at a discount to both analyst targets and one intrinsic value estimate after that sharp slide. Is the market correctly pricing in risk, or has sentiment pushed the stock too far down relative to the fundamentals on show?
Most Popular Narrative: 15% Undervalued
EverCommerce closed at $6.98, while the analyst consensus Narrative on Simply Wall St anchors fair value at $8.25, implying a meaningful gap that this latest 2026 guidance now sits inside and helps investors reassess.
The divestiture of the lower-growth Marketing Technology segment and subsequent focus on core verticals (EverPro, EverHealth, EverWell) has increased operational clarity and reduced seasonality, setting the stage for improved profitability and more predictable, linear revenue patterns.
Strong free cash flow generation, expanding gross margins through payments mix shift, and active share repurchases ($20.6M in Q2) improve balance sheet flexibility and EPS outlook, increasing the likelihood of rerating as secular tailwinds persist.
See why 0 investors see EverCommerce as 15% undervalued.
Result: Fair Value of $8.25 (UNDERVALUED)
Still, the narrative could crack if EverCommerce underinvests in product while chasing efficiency, or if its tightly focused vertical mix encounters unexpected regulatory or demand headwinds.
Find out about the key risks to this EverCommerce narrative.
Another View: EverCommerce Looks Expensive On Earnings
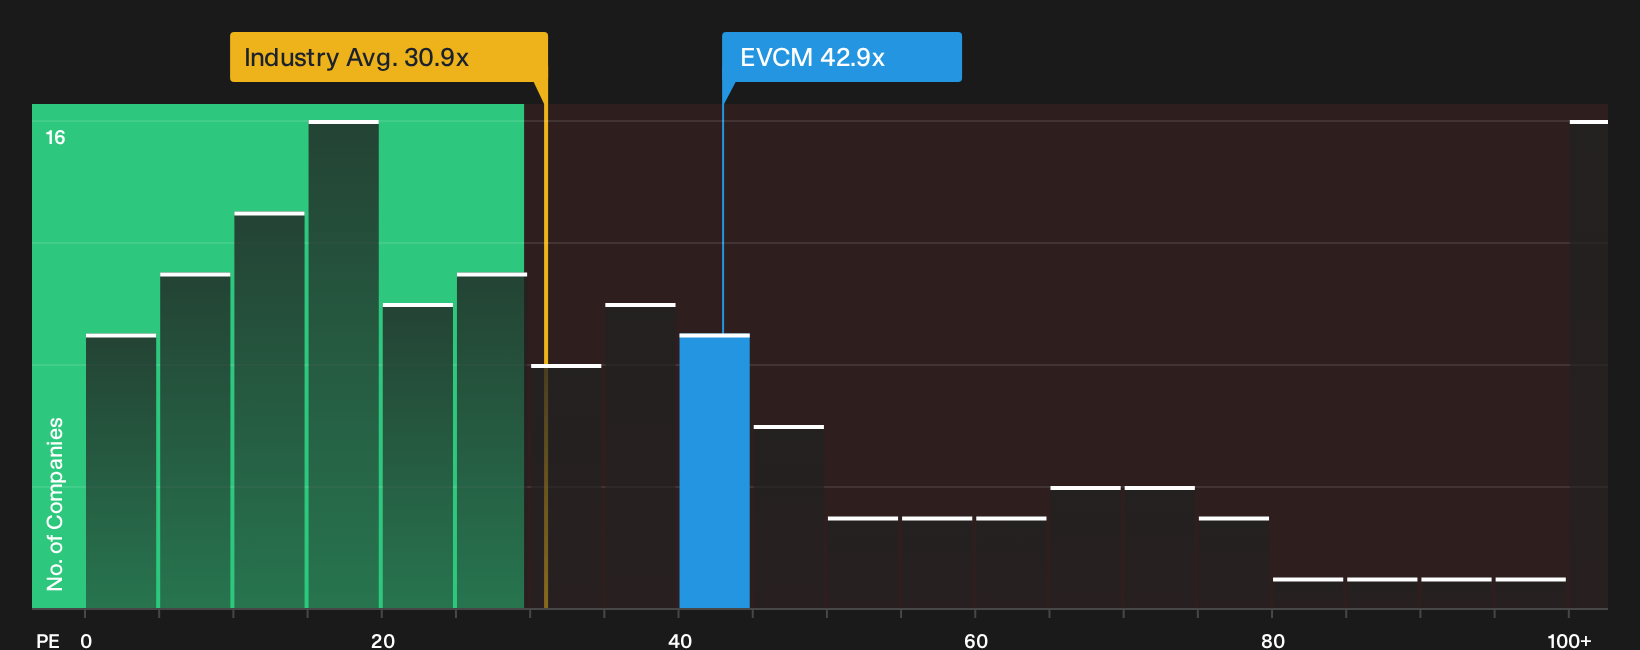
Story one says EverCommerce is undervalued on cash flows. Story two tells something different. At a P/E of 42.9x versus a fair ratio of 30.2x, the stock trades at a hefty premium to the level the market could move toward if expectations cool.
That gap is even wider when stacked against the US Software industry at 31.2x and peers at 33x. If sentiment shifts toward those benchmarks, the current pricing leaves less room for error than the DCF framing suggests. So which signal do you trust more right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views are clear around EverCommerce, so move quickly and test the story against your own risk and reward tolerance using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond EverCommerce?
If EverCommerce has sharpened your thinking, do not stop here. Broaden your watchlist now, or you risk missing setups that better fit your goals.
- Target higher yield potential and stress test your income plan with a curated group of 6 dividend fortresses built for staying power.
- Hunt for resilient businesses and pressure test your downside protection using our 29 resilient stocks with low risk scores tailored to lower volatility profiles.
- Spot tomorrow’s quiet winners early by scanning a focused 20 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com