


EN
Is It Smart To Buy Altron Limited (JSE:AEL) Before It Goes Ex-Dividend?
Some investors rely on dividends for growing their wealth, and if you're one of those dividend sleuths, you might be intrigued to know that Altron Limited (JSE:AEL) is about to go ex-dividend in just 4 days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. It is important to be aware of the ex-dividend date because any trade on the stock needs to have been settled on or before the record date. Therefore, if you purchase Altron's shares on or after the 18th of November, you won't be eligible to receive the dividend, when it is paid on the 23rd of November.
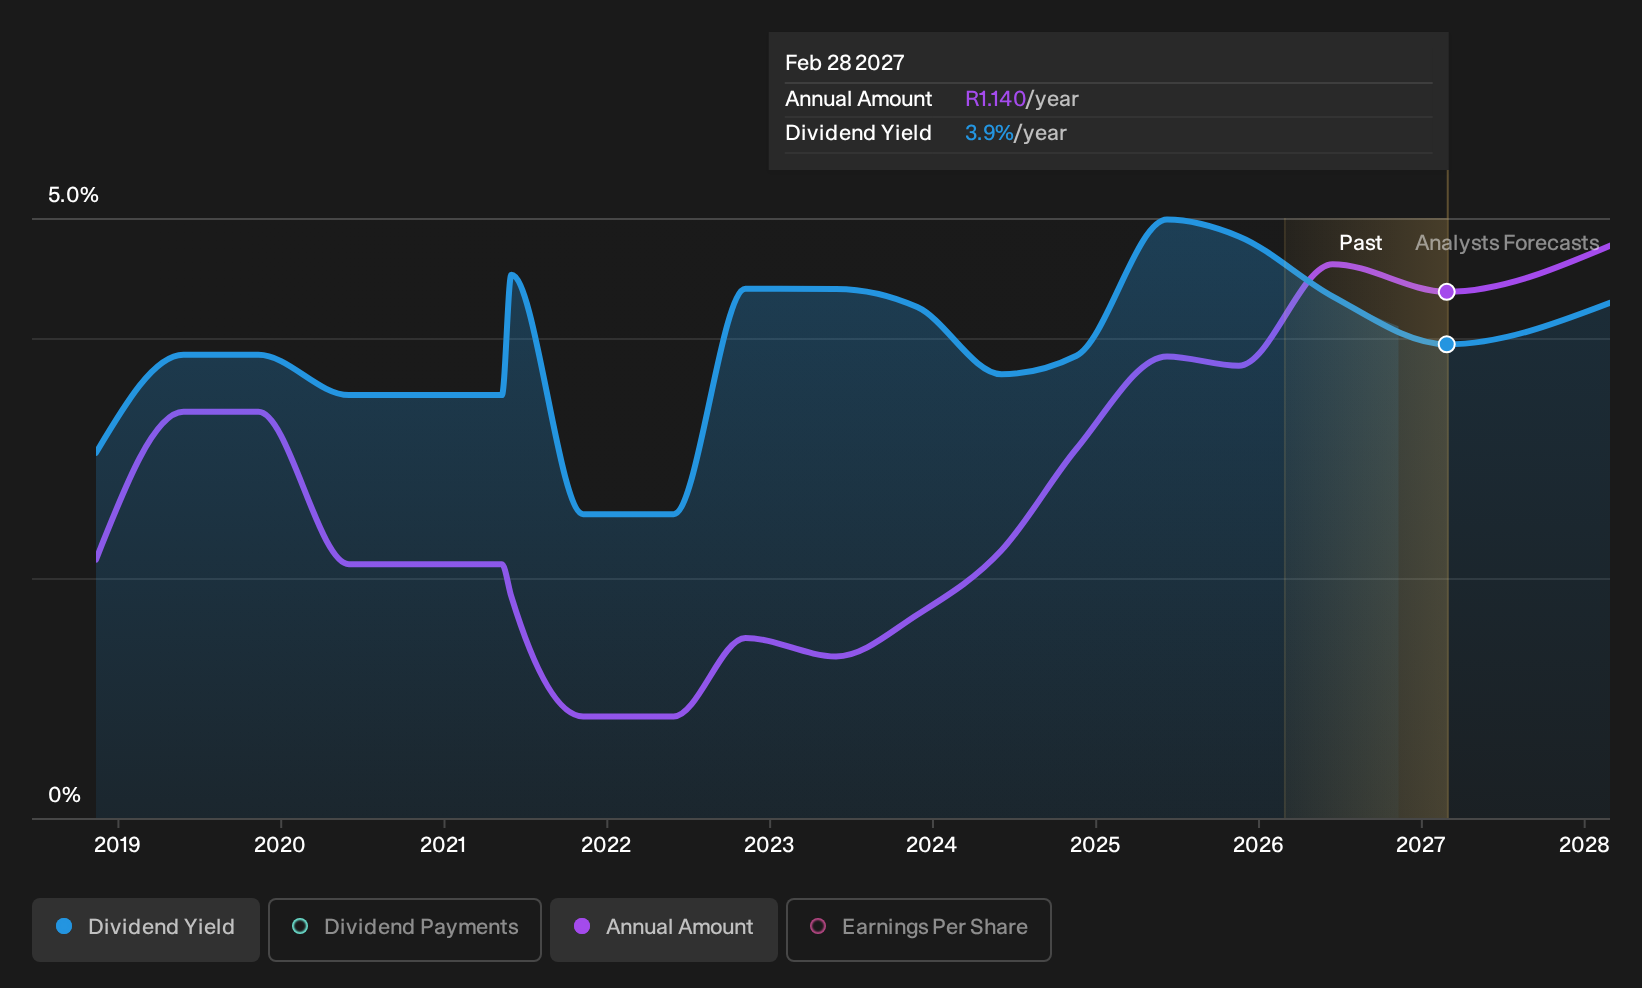
The company's upcoming dividend is R00.55 a share, following on from the last 12 months, when the company distributed a total of R1.20 per share to shareholders. Calculating the last year's worth of payments shows that Altron has a trailing yield of 4.2% on the current share price of R028.88. If you buy this business for its dividend, you should have an idea of whether Altron's dividend is reliable and sustainable. So we need to investigate whether Altron can afford its dividend, and if the dividend could grow.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Altron paid out more than half (57%) of its earnings last year, which is a regular payout ratio for most companies. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. It paid out 86% of its free cash flow as dividends, which is within usual limits but will limit the company's ability to lift the dividend if there's no growth.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
Check out our latest analysis for Altron
Click here to see how much of its profit Altron paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. That's why it's comforting to see Altron's earnings have been skyrocketing, up 50% per annum for the past five years.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. Since the start of our data, eight years ago, Altron has lifted its dividend by approximately 10.0% a year on average. We're glad to see dividends rising alongside earnings over a number of years, which may be a sign the company intends to share the growth with shareholders.
To Sum It Up
Has Altron got what it takes to maintain its dividend payments? Higher earnings per share generally lead to higher dividends from dividend-paying stocks over the long run. That's why we're glad to see Altron's earnings per share growing, although as we saw, the company is paying out more than half of its earnings and cashflow - 57% and 86% respectively. Overall, it's not a bad combination, but we feel that there are likely more attractive dividend prospects out there.
So while Altron looks good from a dividend perspective, it's always worthwhile being up to date with the risks involved in this stock. For example, we've found 1 warning sign for Altron that we recommend you consider before investing in the business.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.