


EN
3 Bank Stocks That Could Benefit From Higher Short Term Interest Rates
Short-term interest rates are back in the spotlight as traders brace for the chance of a larger Federal Reserve hike, a stronger US dollar and choppy moves in global currencies and oil. That mix can reshuffle winners and losers across the financial sector in a hurry, creating both potential openings and traps. This article first unpacks the backdrop and then walks through three stocks from our screener that appear closely tied to this rate story.
The three stocks highlighted below are just a small sample from this rate-sensitive theme, and the full screen surfaced 34 more large-cap banks and insurers with equally detailed stories that are not covered here. To go straight to the source, analyze and filter potential high-conviction ideas for yourself with the U.S. Large-Cap Banks and Insurers Benefiting from Higher Short-Term Interest Rates screener.
Heritage Financial (HFWA)
Heritage Financial fits this higher short term rate theme neatly, since it leans on commercial and retail deposits to support net interest income. The analyst consensus Narrative on Simply Wall St frames the current story around how efficiently that funding base is put to work.
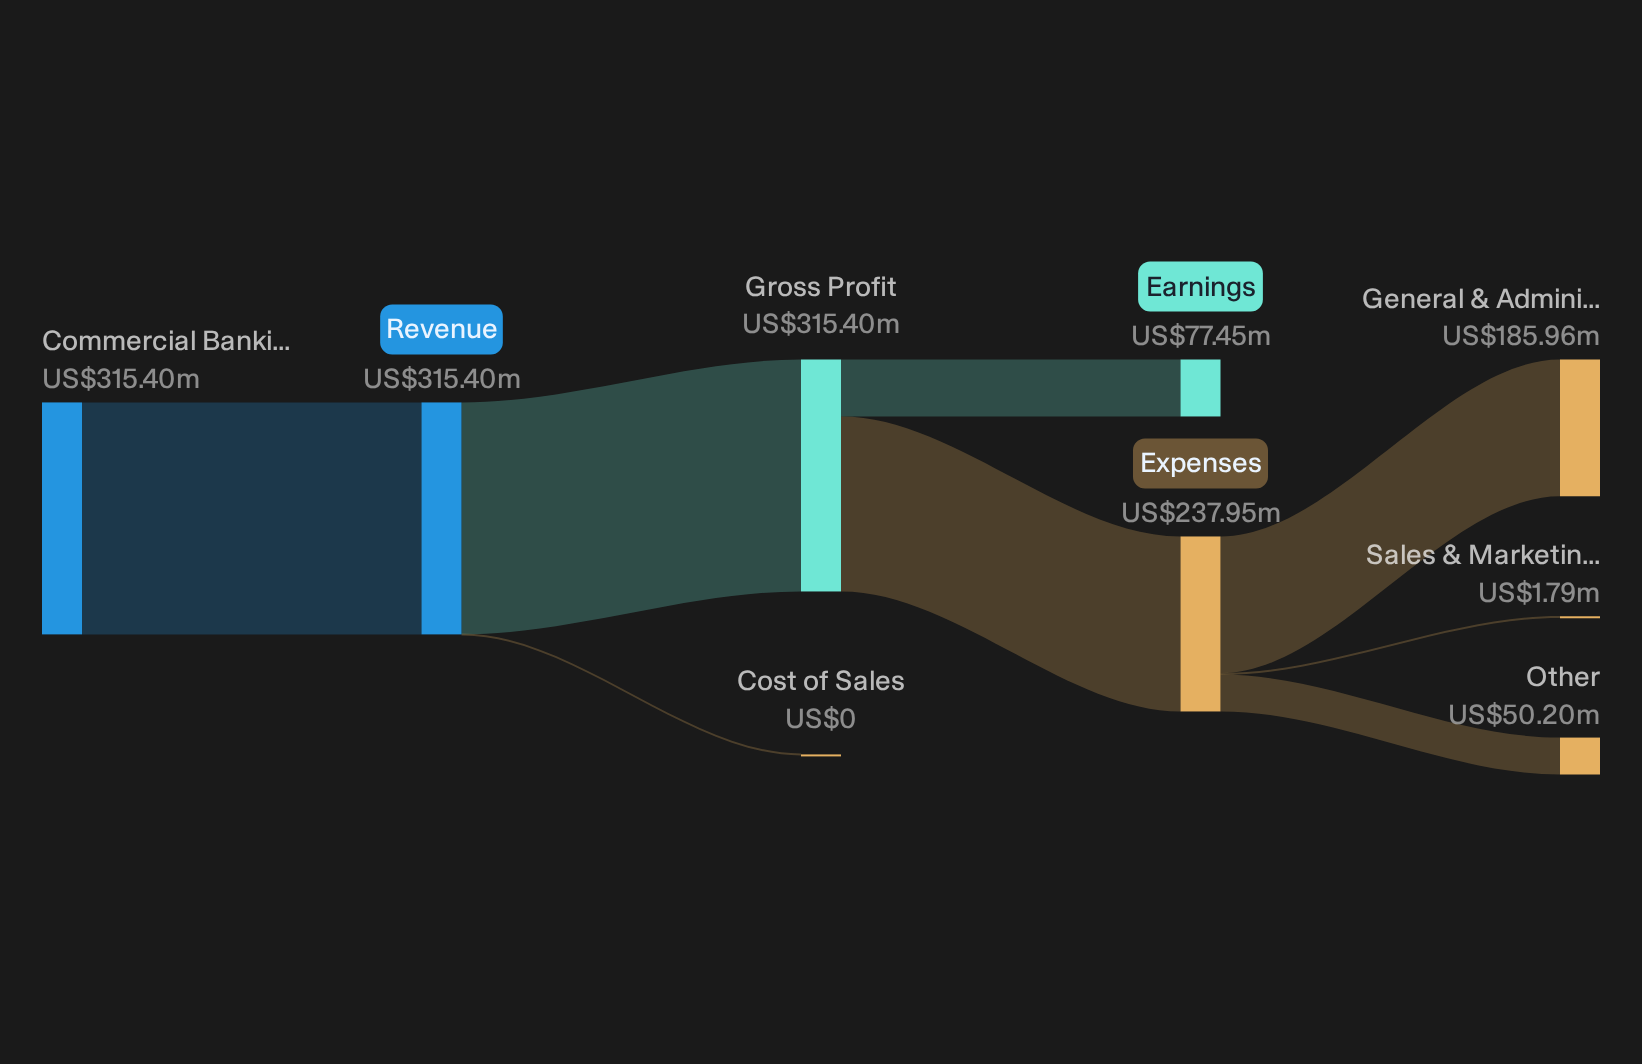
Heritage Financial is a regional bank holding company that serves small and medium sized businesses through lending, deposits and digital services, generating about US$315 million from commercial banking in the United States, with a market cap of roughly US$1.1b.
"Completion of the Olympic and Kitsap integrations, including the late September systems conversion and the expected step down in quarterly noninterest expense from roughly $64 million to about $56 million to $57 million in Q4, could reveal a lower operating cost base and support higher net margins and earnings."
What happens if one quiet shift in its funding mix or loan pricing slows that margin story is what will really matter for investors.
If that funding shift is what you are watching, read the full narrative for Heritage Financial to see how deposit mix, pricing power and credit trends could be decoupling.
OceanFirst Financial (OCFC)
OceanFirst Financial links neatly to this higher short term rate theme because its traditional lending and deposit franchise helps transmit changes in front end yields into net interest income. The analyst consensus Narrative on Simply Wall St frames the current story around scale, funding mix and earnings power.
OceanFirst Financial runs a community banking platform that gathers deposits and makes a wide range of real estate, commercial and consumer loans, with all US$510 million of revenue coming from community banking services in the United States. The bank’s market value sits around US$1.8b.
"The June 2026 acquisition of Flushing Financial added about US$7.4b of deposits and 30 branches across New York City and Long Island, which creates more scope to grow relationship based deposits and fee income over time and could support higher revenue and earnings as the combined franchise matures. Ongoing balance sheet optimization, including the sale of around US$1.3b to US$1.4b of rent regulated multifamily loans, the credit risk transfer on US$1.5b of mortgages and the recycling of proceeds into liquid investment grade securities, is reshaping OceanFirst Financial’s risk profile in ways that can support credit quality, funding flexibility and net margins."
One unseen pressure on how those new deposits are priced against future loan demand could end up doing most of the work on returns.
That pricing pressure is exactly what the full narrative for OceanFirst Financial unpacks, revealing where OceanFirst Financial’s deposit costs, loan demand and fee income could be quietly accelerating or stalling.

First Hawaiian (FHB)
First Hawaiian ties closely to this higher short term rate theme because it runs a broad, deposit-funded commercial and consumer banking platform that tends to be sensitive to moves at the front end of the yield curve.
First Hawaiian, Inc. operates a full-service bank across retail and commercial customers in the U.S., generating about US$633 million from Retail Banking and roughly US$238 million from Commercial Banking, and the stock carries a market value around US$3.0b.
"The all-stock acquisition of TriCo Bancshares, which is expected to close near the end of 2026, is planned to create a combined First Hawaiian platform with about US$34b of assets, US$29b of deposits and 117 branches."
What happens if one key assumption about how those larger deposits reprice against future loan demand breaks is what could really move the needle for investors.
Those repricing assumptions are exactly what the full narrative for First Hawaiian lays bare, highlighting where First Hawaiian’s funding costs and earning power could be quietly accelerating or stalling.

Seeking Fresh Alternatives Before They Fly
Fresh breakouts and new momentum often get caught by data before headlines catch up. Scan under the radar for now, act before the crowd moves, get in early.
- Pinpoint companies where resilient balance sheets meet real cash flow strength by running the list of solid balance sheet and fundamentals (23 results) before prices reflect that stability, then decide whether to act while it matters.
- Consider structural trends in automation and industrial efficiency by checking the curated set of 85 robotics and automation stocks before capital chases the same theme and entry points start dropping.
- Track early leadership in crypto infrastructure and payment rails by scanning the hand picked pool of 24 cryptocurrency and blockchain stocks while it is still mostly under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com