


EN
How Investors May Respond To Shimizu (TSE:1803) Strong Half Year Earnings
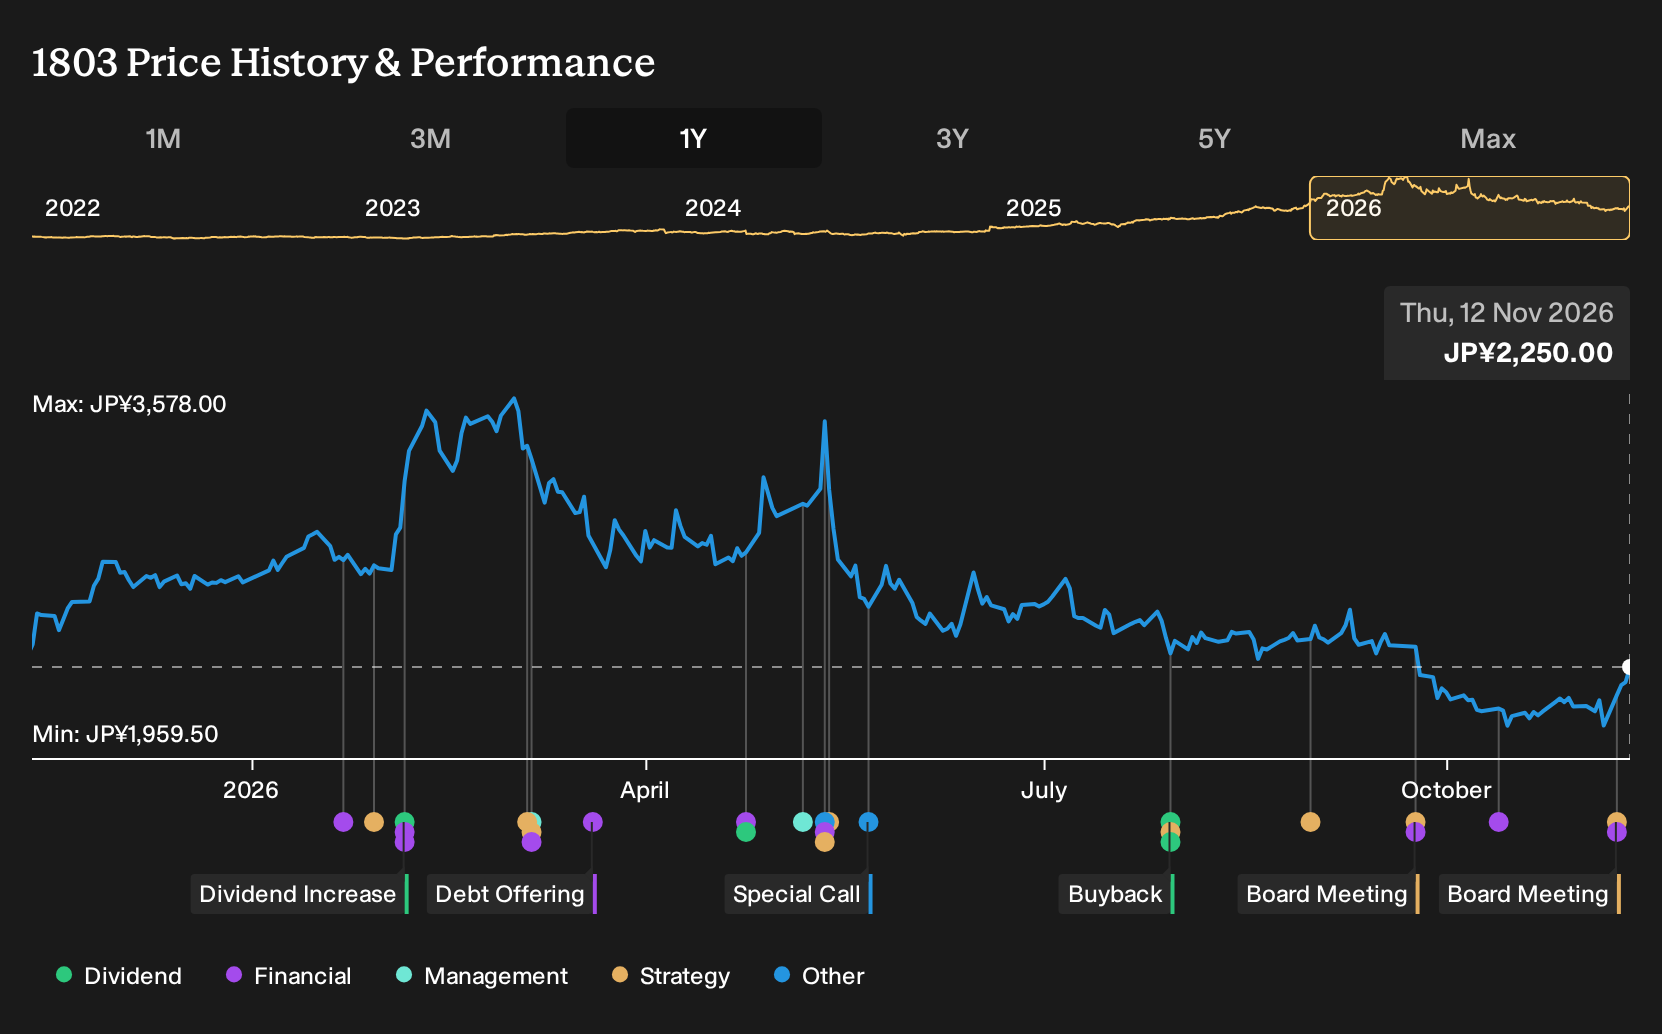
- Shimizu reported half year results for the period ended September 30, 2026, with sales of ¥967,121 million, revenue of ¥1,061,632 million and net income of ¥107,938 million, alongside a board meeting on November 9, 2026 to consider adjusting conversion prices on its zero coupon convertible bonds due 2031 and 2033.
- Basic earnings per share from continuing operations reached ¥159.19 compared with ¥67.93 a year earlier, which highlights a sharp shift in profitability. This puts Shimizu's operating execution and capital structure decisions under closer investor scrutiny.
- Attention now turns to how Shimizu's stronger half year net income reshapes the investment narrative that readers use to assess the company.
What Is Shimizu's Investment Narrative?
To own Shimizu, you need to believe the construction cycle still supports a large order book, that the group can keep turning complex infrastructure and building work into consistent profit, and that heavy project spending does not erode returns. The half year figures, with ¥1,061,632 million in revenue and ¥107,938 million in net income, speak to solid execution despite capital intensive operations. In the short term, the key swing factors are project mix, construction costs, and how much of the recent 85.6% earnings growth came from underlying demand rather than one off gains.
The board discussion on resetting conversion prices for the 2031 and 2033 zero coupon convertible bonds sits squarely in that story. Any change to conversion terms affects how future upside is shared between existing shareholders and bondholders, and it feeds into how investors see balance sheet risk. Forecasts currently point to earnings declining on average over the next three years. As a result, potential catalysts from here look more about disciplined bidding, cash generation to support the 3.96% dividend, and evidence that profit margins can be kept near current levels without leaning on unusual items.
Even so, there is one structural weak point in the Shimizu equity story that only becomes obvious when you look closely at ...
There's only one way to know the right time to buy, sell or hold Shimizu. Head to Simply Wall St's company report for the latest analysis of Shimizu's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit at roughly ¥2,169 and an extreme ¥60,795,194, which shows just how far apart views on Shimizu can be. These are retail investors, not professionals, and their models do not yet reflect the latest half year earnings or the pending bond conversion decision. Readers who care about how different investors frame risk and opportunity may want to compare several of these viewpoints before deciding how Shimizu fits in a broader construction portfolio.
Explore another Shimizu fair value estimate, including one that suggests it could be worth just ¥2169.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Shimizu research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Shimizu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shimizu's overall financial health at a glance.
Looking For More Ideas Beyond Shimizu?
If Shimizu's results have sharpened your focus on construction and infrastructure, use that same mindset to widen your watchlist. The Simply Wall St Screener lets you move from a single stock to a curated set of opportunities that match the balance sheet strength, income profile, or valuation angle you care about most.
- If you want stability at the core of your portfolio, start with businesses that pair robust finances with measured risk by scanning our 20 resilient stocks with low risk scores.
- For investors who prioritize income, look at companies aiming to combine higher yields with resilience by reviewing the 27 dividend fortresses.
- If you are hunting for underappreciated potential, broaden your search to strong operators that the market may be overlooking through the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com