


EN
Southwest Gas Holdings (SWX) Reports Weaker Earnings On A Valuation That Still Looks Modestly Cheap
Q3 Earnings Put Southwest Gas Holdings Under The Microscope
Southwest Gas Holdings (SWX) just posted third quarter and nine month results that showed lower sales, weaker net income, and a sharp drop in earnings per share compared with the same periods last year.
Despite weaker earnings, Southwest Gas Holdings has seen momentum build in its shares, with a 30 day share price return of 8.35% and a year to date share price gain of 16.13%. The 3 year total shareholder return of 69.69% points to investors rewarding the longer term story.
See how Southwest Gas Holdings compares with other regulated utilities by reviewing our curated picks in the 29 resilient stocks with low risk scores.
That mix is unusual. Southwest Gas Holdings just reported weaker earnings, yet the share price has moved higher. Are investors repricing the underlying business, or is this a sentiment swing that the valuation now needs to justify?
Most Popular Narrative: 7% Undervalued
Against the last close of $93.08, the analyst consensus Narrative on Simply Wall St anchors Southwest Gas Holdings at a fair value of $100.63, which points to a modest discount that investors now need to weigh against execution and regulatory risks.
Accelerated infrastructure investment opportunities are now anchored by a larger US$2.3b capital plan for the Great Basin 2028 Expansion Project and a broader US$6.3b 5 year utility capital program. These are expected to expand regulated rate base and in turn support higher future regulated revenue and earnings.
See why 4 investors see Southwest Gas Holdings as 7% undervalued.
Result: Fair Value of $100.63 (UNDERVALUED)
Still, the Southwest Gas Holdings story can be knocked off course if regulators grant weaker rate outcomes than expected, or if the US$2.3b Great Basin project encounters cost or timing setbacks.
Find out about the key risks to this Southwest Gas Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Southwest Gas Holdings
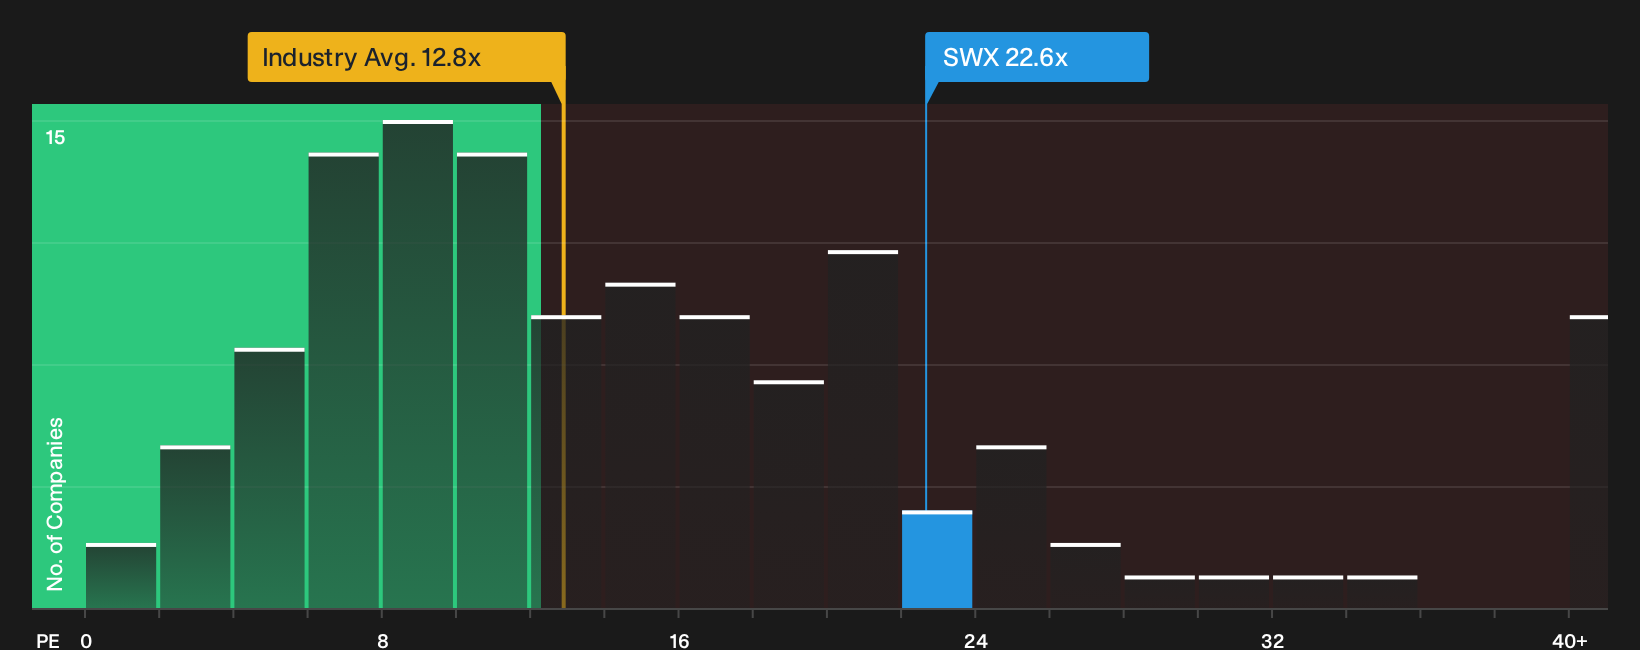
The headline narrative says Southwest Gas Holdings looks about 7% undervalued on a fair value of $100.63, yet the simple P/E check tells a tougher story. SWX trades on 22.6x earnings compared with a fair ratio of 21x, peers at 16.1x and the global gas utilities group at 12.8x.
That kind of premium can be a cushion if the story plays out, or a problem if expectations reset and the valuation drifts toward the fair ratio instead. It leaves a practical question for you as a shareholder or prospect: how much of that gap are you comfortable owning?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of upbeat pricing and softer earnings leaves you on the fence, move quickly and walk through the data yourself before opinions harden. To weigh both the potential upside and the pressure points in one place, start with our summary of 2 key rewards and 2 important warning signs
Ready To Hunt For More Ideas Beyond Southwest Gas Holdings?
If Southwest Gas Holdings has your attention, broaden your watchlist now with other clear, data driven ideas that could sharpen your portfolio decisions this year.
- Target income resilience by scanning for 6 dividend fortresses that can help anchor your returns with substantial cash payouts.
- Spot potential upside by reviewing a 20 high quality undiscovered gems that the market may not be fully focused on yet.
- Dial down portfolio stress by building around a list of solid balance sheet and fundamentals (23 results) that leans on strong finances instead of fragile optimism.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com