


EN
Capital Clean Energy Carriers (CCEC) Could Be 22% Undervalued Following Q3 Results
Capital Clean Energy Carriers (CCEC) just released third quarter and nine month 2026 results, providing updated figures that show how its LNG focused shipping and energy distribution business is currently performing.
The recent earnings update lands after a softer run in the stock, with the 30 day share price return down 3.36% and the 90 day move down 11.01%. Yet Capital Clean Energy Carriers still shows a 1 year total shareholder return of 4.42% and a 3 year total shareholder return of 59.18%, which points to longer term momentum that has cooled in recent months as investors reset expectations around risk and future growth potential.
Scan beyond Capital Clean Energy Carriers and compare it with 43 power grid technology and infrastructure stocks, which could also be linked to the build out of global energy transport and infrastructure.
Capital Clean Energy Carriers now looks like a solid LNG operator, and its share price has cooled in recent months. The key issue for investors is whether that combination still adds up to a fair valuation today.
Most Popular Narrative: 22.1% Undervalued
At a last close of $20.12, the analyst consensus Narrative on Simply Wall St points to a fair value of about $25.83 for Capital Clean Energy Carriers, implying a material discount based on its long term cash flow potential using a 15.26% discount rate.
The build out of CCEC’s gas focused fleet, including new LNG, LPG and LCO₂ carriers that increased total assets to about US$4.7b and fixed assets to about US$4.3b by mid 2026, adds contracted days backed by a charter backlog of roughly US$2.8b to US$2.9b. This can support future revenue and cash flow that investors may not fully price in today.
See why 1 investors see Capital Clean Energy Carriers as 22% undervalued.
Result: Fair Value of $25.83 (UNDERVALUED)
Still, the story around Capital Clean Energy Carriers can change quickly if floating rate debt lifts financing costs or if funding the vessel orderbook tightens cash flow.
Find out about the key risks to this Capital Clean Energy Carriers narrative.
Another Take On Capital Clean Energy Carriers’ Valuation
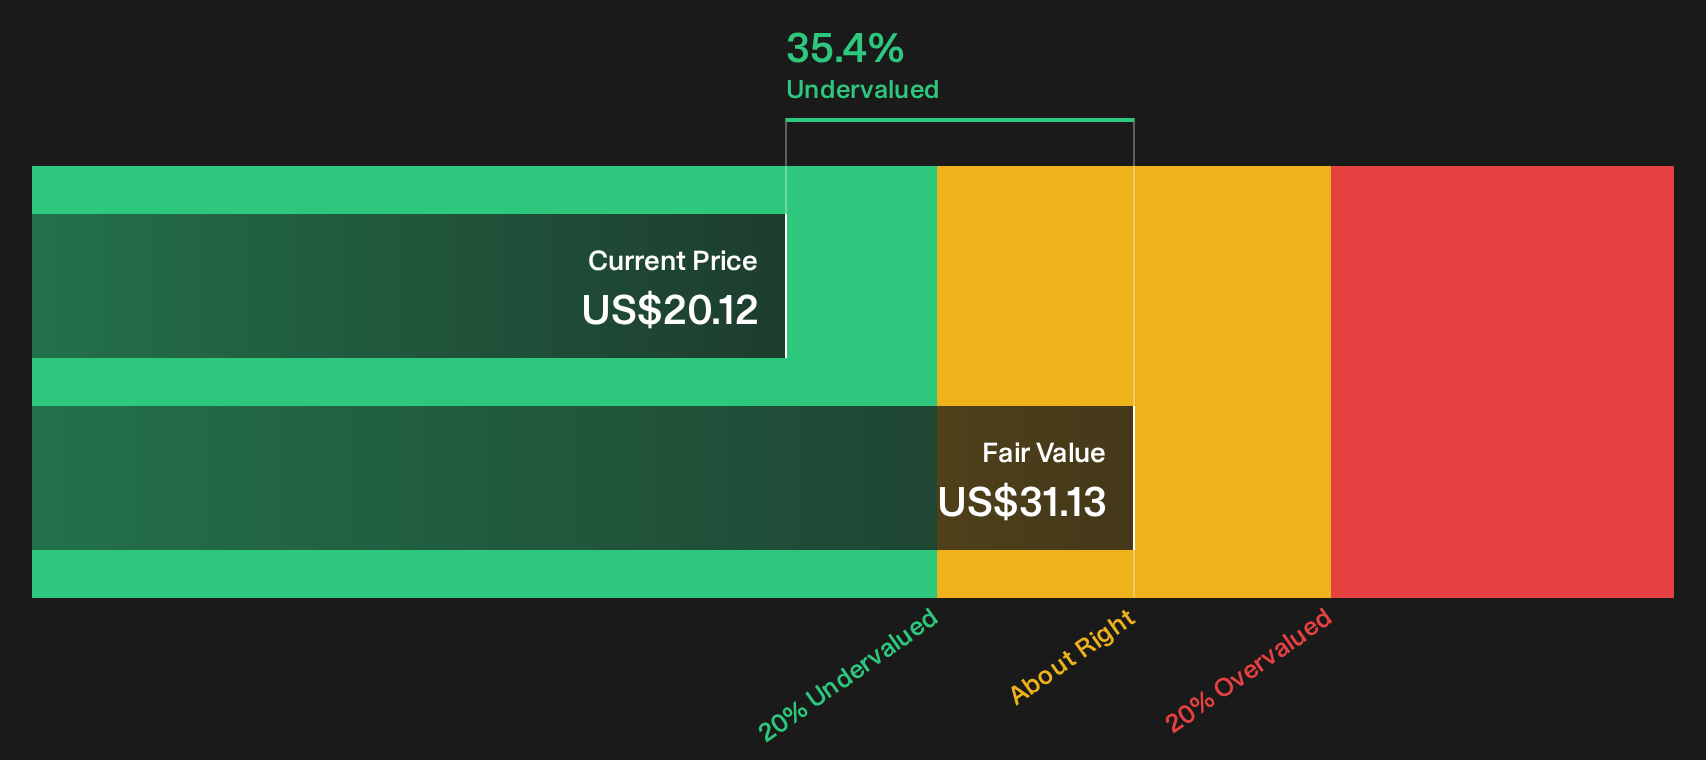
The discounted cash flow work suggests Capital Clean Energy Carriers trades at a meaningful gap to an estimated future cash flow value of $31.13 per share, compared with the recent $20.12 price. That points to an undervalued stock on this framework. The question is how comfortable you are with the long term cash flow assumptions baked into that model.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Capital Clean Energy Carriers in this update has been mixed. This is exactly why you should move quickly and test the numbers for yourself. To see how the balance of concerns and upside potential looks when you put all the data together, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Capital Clean Energy Carriers?
If Capital Clean Energy Carriers has your attention, do not stop there. Broaden your watchlist with other focused ideas that sharpen your next move.
- Target potential mispricings by scanning a curated pool of companies screened as 31 high quality undervalued stocks.
- Strengthen income potential by focusing on businesses that appear in our list of 6 dividend fortresses.
- Dial down portfolio risk by concentrating on financially robust operators sourced from our list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com