


EN
STERIS (STE) Files Fresh Funding Shelf, Is The Stock Already Pricey?
STERIS (NYSE:STE) has put a fresh funding toolkit in place by filing an omnibus shelf registration that covers debt, ordinary and preferred equity, warrants, units and securities from key financing subsidiaries.
STERIS now trades at US$253.44, with a 30-day share price return of 16.38% and a 90-day move of 8.64%. The 1-year total shareholder return is slightly down 1.61%, indicating that recent momentum has firmed even as longer term gains remain more moderate.
Scan other healthcare equipment players with similar funding flexibility and balance sheet strength using our curated list of solid balance sheet and fundamentals (23 results) as a comparison set to STERIS.
Bulls point to STERIS’s fresh funding lines and recent 30 day surge as proof this rerating has room to run, while bears see overreach. Which view fits the valuation math that follows?
Most Popular Narrative: 6% Undervalued
STERIS is priced at $253.44 against an analyst consensus fair value of about $270.71. The analyst consensus Narrative on Simply Wall St ties this directly to medium single digit revenue growth and margin expansion assumptions built off current operations.
Continued mix shift toward recurring chemistries and services, which now account for roughly 80% of STERIS revenue versus about 20% a decade ago, can add stability to organic revenue and support operating leverage into earnings.
Customer moves to localize medical device and pharmaceutical manufacturing and maintain resilient supply chains are increasing the need for sterilization capacity and aseptic equipment. This can lift revenue and margins in Applied Sterilization Technologies and Life Sciences as new projects come online.
See why 8 investors see STERIS as 6% undervalued.
Result: Fair Value of $270.71 (UNDERVALUED)
Still, the rerating case for STERIS can crack if tariff costs stop being offset in pricing, or if the North Carolina chemistries project underdelivers.
Find out about the key risks to this STERIS narrative.
Another View: STERIS Looks Priced Rich On Earnings
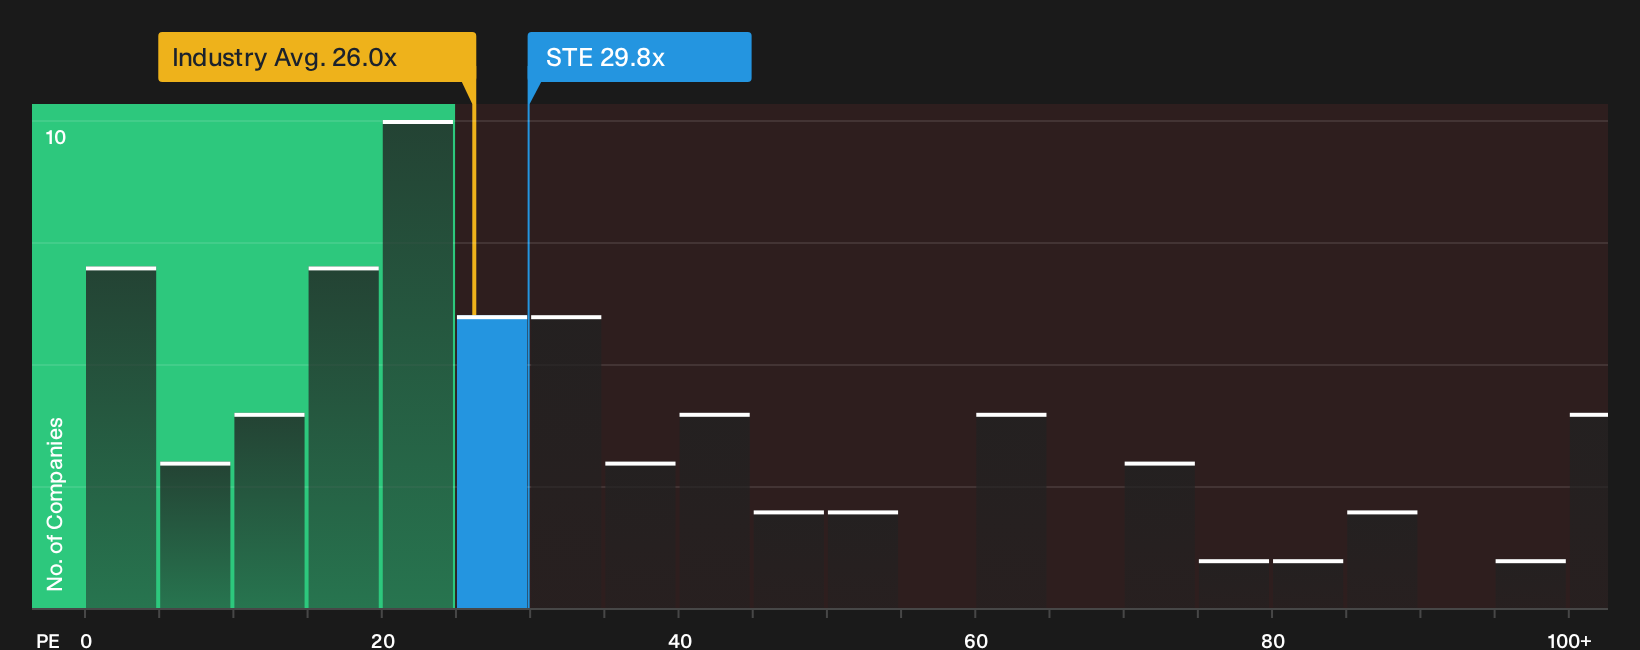
On the flip side of that 6% undervalued narrative, STERIS currently trades on a P/E of 29.8x, which screens as expensive versus the US Medical Equipment industry at 26x and a peer average of 23.7x. It also sits above a fair ratio of 27.7x, so where exactly is the cushion if sentiment cools?
To stress test that question against hard numbers, look at how this price compares to the earnings profile in our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on STERIS are clear in the data, so move quickly to test the numbers yourself and pressure test the bullish angle. To see what optimism in the market is built on, review the 2 key rewards
Looking for more investment ideas beyond STERIS?
If STERIS has sharpened your focus on quality, do not stop here. Broaden your watchlist now and give yourself more options when the market presents chances.
- Target resilient cash generators by scanning a 31 high quality undervalued stocks that combines quality fundamentals with prices that may leave room for upside.
- Strengthen your income stream by reviewing a curated set of yield opportunities through the 6 dividend fortresses that pairs payouts with business durability.
- Prioritise capital preservation by filtering for quieter performers via a 29 resilient stocks with low risk scores that focuses on steadier returns with fewer surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com