


EN
Should Third Quarter Earnings Require Action From SFL (SFL) Investors?
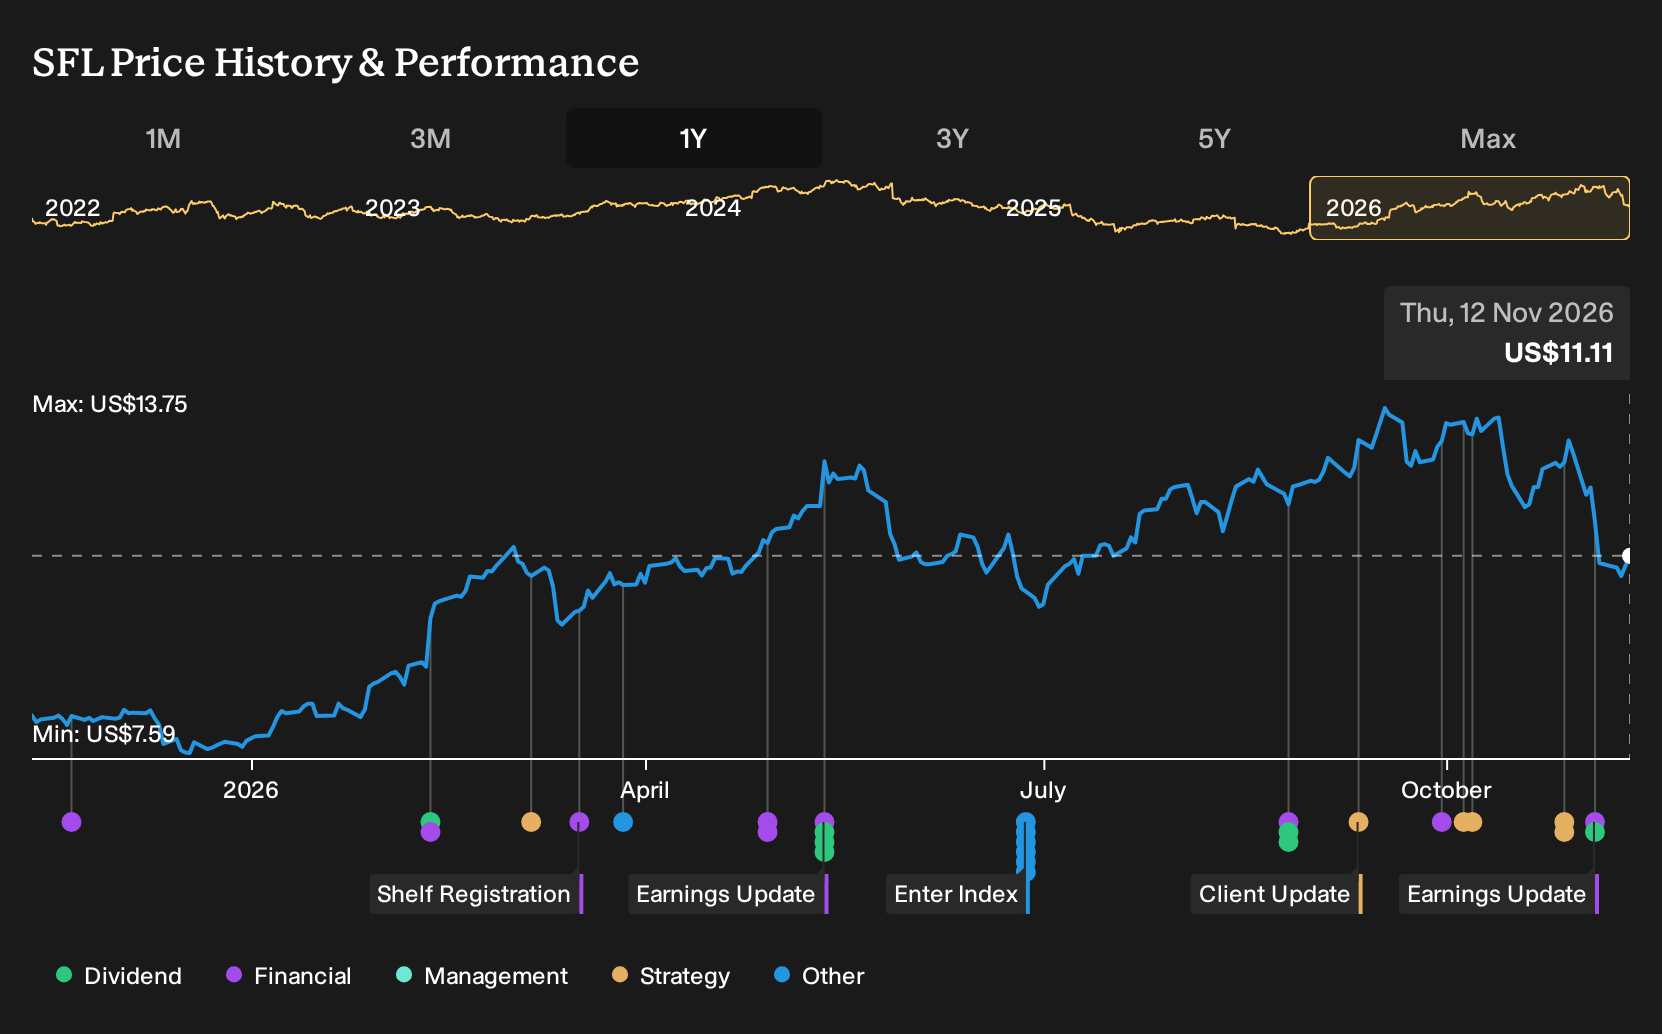
- SFL Corporation Ltd. reported third quarter 2026 revenue of US$201.58 million and net income of US$37.35 million, with basic earnings per share from continuing operations of US$0.26 and a quarterly cash dividend of US$0.22 per share declared for payment in late December.
- The combination of earnings and a maintained dividend highlights how SFL is currently converting its contract backlog into cash while continuing to return capital to shareholders through regular payouts.
- The next step is to see how SFL's affirmed dividend shapes the existing investment narrative built around its long term charter backlog.
Scan for opportunities that echo SFL's combination of earnings visibility and income potential by reviewing our hand picked list of 6 dividend fortresses.
SFL Investment Narrative Recap
SFL stock still hinges on one big idea. You need to believe that its multi sector charter book in containers, tankers, car carriers and rigs can keep ships employed and cash flows steady enough to service debt and fund the remaining US$1.2b growth capex. The latest quarter, with US$201.58 million in revenue and US$37.35 million in net income, broadly fits that story rather than changing it.
The nearer term swing factor remains execution on financing and deployment of new LNG capable vessels and rigs, while keeping utilization solid. The biggest risk stays the same. Concentration in energy linked assets and large container contracts leaves SFL exposed if drilling programs slow or container trade softens, which could pressure earnings and test the current payout approach.
The most relevant update for that thesis is the affirmed quarterly dividend of US$0.22 per share. It signals that SFL is still leaning on its long term charter backlog to support regular cash returns, even as analysts in the analyst consensus Narrative on Simply Wall St flag that the dividend and interest costs are not well covered by earnings.
For investors, the key issue is whether that dividend decision fits comfortably with the other moving parts. There is a long dated US$4.6b backlog, sizeable capex still to fund, and exposure to cyclical tanker, container and offshore markets. If utilization or day rates weaken, the combination of a high payout and tighter financial flexibility could become the main pressure point in the SFL story.
What The SFL Forecasts Are Asking You To Believe
Analysts are effectively asking you to buy into a version of SFL where revenue trends steadily higher, margins improve and earnings roughly double over the next few years. The current assumptions point to revenue growing at 6.6% a year and net income rising from US$63.9 million today to US$143.7 million by 2029, with the profit margin lifting from 9.0% to 16.6% if everything lines up.
Put simply, that is an earnings change of about US$79.8 million between today and the 2029 consensus. This is a little more than 2x the current profit base. For a business already carrying a long charter backlog and sizeable capex and dividend commitments, that kind of step up in earnings rests on two levers. One is the forecast revenue profile. The other is the expectation that more of each dollar of sales drops through to the bottom line as higher margin assets enter service and financing remains manageable.
SFL's narrative projects US$863.5 million revenue and US$143.7 million earnings by 2029. This implies 6.6% yearly revenue growth and an earnings increase of about US$79.8 million from US$63.9 million today.
Uncover how SFL's fair value indicates a 19% potential upside to its current price. This upside could narrow quickly if sentiment shifts.
Exploring Other Perspectives
For SFL, the most optimistic analysts focus on the dividend as a potential catalyst, not a constraint. Before this earnings and dividend update, that bullish group was already pencilling in revenue of about US$918.3 million and earnings of US$175.5 million by 2029. Opinions vary significantly, so treat this dividend affirmation as a fresh prompt to compare several viewpoints before deciding what you believe might change in those forecasts.
Explore 4 other SFL fair value estimates, including one that suggests there may be as much as 20% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and instincts.
- A great starting point for your SFL research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SFL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SFL's overall financial health at a glance.
Looking For More Investment Ideas Beyond SFL?
If the SFL story has you thinking about income, resilience and future upside together, it can help to scan a wider field of companies that share some of those traits. The Simply Wall St Screener lets you move from one stock to a full bench of candidates that match the kind of balance sheet strength, dividend profile or valuation setup you want to focus on next.
- For investors who want income potential paired with balance sheet backing, start with a list of solid balance sheet and fundamentals (23 results) that aims to sustain payouts through different cycles.
- If capital preservation is your first filter and upside is the second, narrow the field using a 29 resilient stocks with low risk scores that score well on financial strength and volatility.
- When you want to see what else might be hiding in plain sight, widen your search to a 20 high quality undiscovered gems that share strong fundamentals but attract less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com