


EN
Daiwa House Industry (TSE:1925) Lifts Outlook And Dividends On A Valuation That Still Looks Cheap
Daiwa House Industry (TSE:1925) just lifted its forecast for the year to March 2027, raising projected net sales, operating income and earnings per share, and paired that move with higher interim and full year dividend guidance.
The guidance revision has arrived alongside a sharp 1-day share price return of 5.75% and a 30-day share price return of 9.20%. However, Daiwa House Industry still shows a year to date share price decline of 8.53% and a 1-year total shareholder return fall of 7.28%, while the 3-year and 5-year total shareholder returns of 25.38% and 67.62% point to a much stronger longer run outcome for investors who have held on through recent volatility.
Spot fresh ideas by comparing Daiwa House Industry's upgraded guidance and dividend outlook with other companies on our hand picked 18 high quality undervalued stocks list.Daiwa House Industry just paired a guidance lift and richer dividend path with a strong one day rebound, so the real puzzle now is how much of that optimism the current valuation already reflects.
Preferred P/E of 8.2x: Is it justified?
On simple earnings terms, Daiwa House Industry trades on a P/E of 8.2x, which looks restrained relative to both the broader Japanese market and its direct real estate peers, even after the latest guidance lift and share price bounce toward ¥2,392.5.
The P/E ratio compares the current share price with earnings per share, so it effectively shows how much investors are paying today for each unit of profit. For a business like Daiwa House Industry that earns income from construction, development and related services, P/E is a practical shorthand for what the market is willing to pay for its existing earnings power.
There is a clear valuation gap. The stock trades at a P/E of 8.2x, while the JP market average is 13.2x and the JP Real Estate industry comes in at 9.6x. The estimated fair P/E for Daiwa House Industry is even higher at 17.4x. This points to a level that the valuation could migrate toward if investors eventually price its earnings more in line with that fair ratio.
Explore the SWS fair ratio for Daiwa House Industry.
Result: Price-to-earnings of 8.2x (UNDERVALUED)
Still, the updated story can break if earnings momentum stalls across core housing and logistics projects, or if higher dividends strain Daiwa House Industry’s cash needs.
Find out about the key risks to this Daiwa House Industry narrative.
Another view on Daiwa House Industry's value
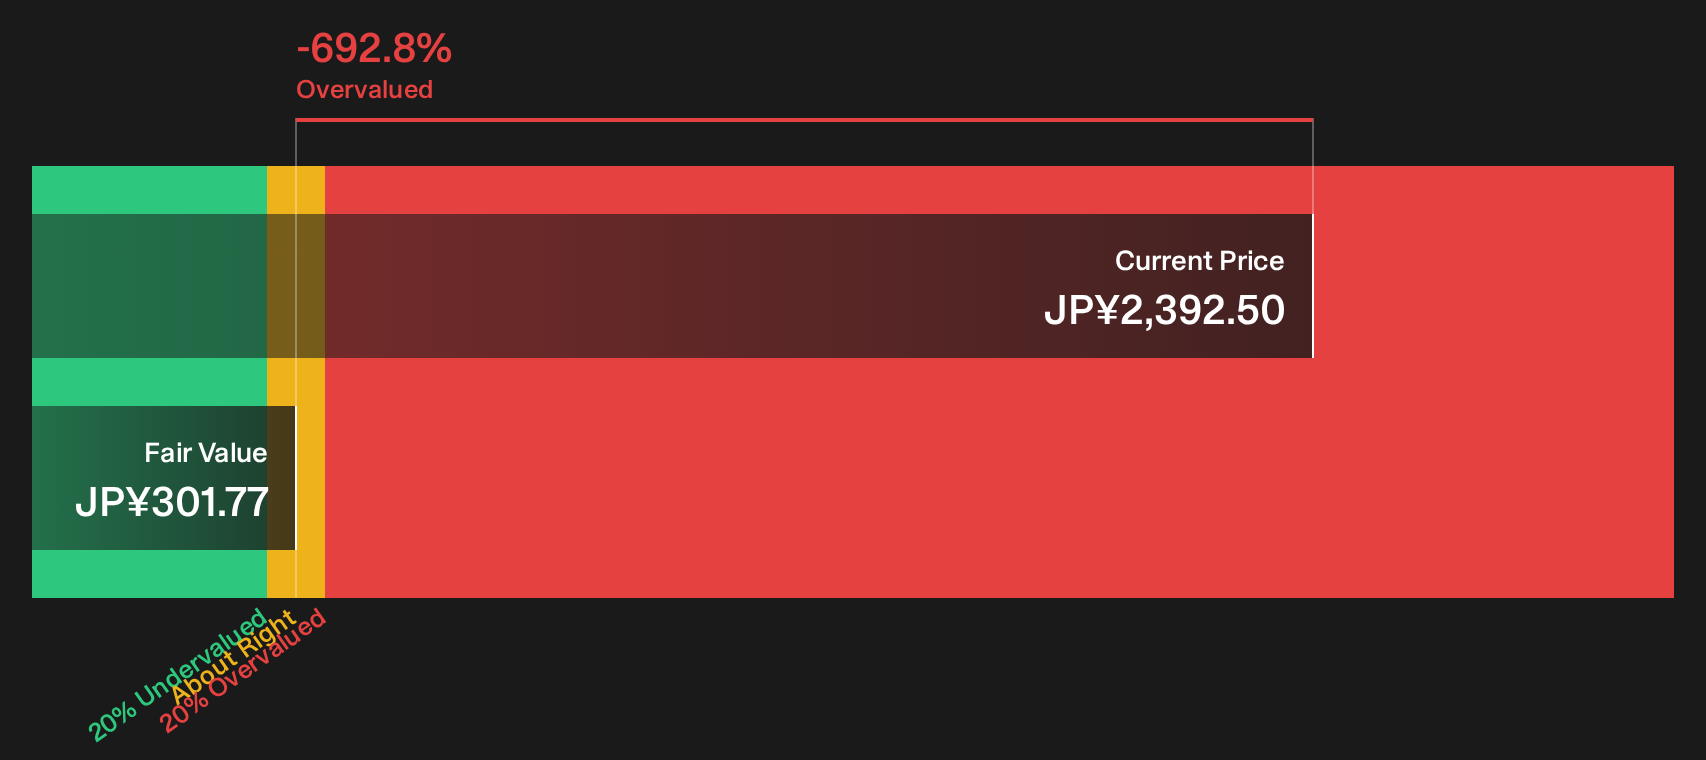
From a different perspective, the SWS DCF model suggests a contrasting view, with Daiwa House Industry trading at around ¥2,392.5 compared with an estimated future cash flow value near ¥301.77, which implies the shares could be priced generously. That sort of gap can matter for anyone who considers downside risk as carefully as potential upside.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Daiwa House Industry for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of upgraded guidance, valuation tension and income appeal around Daiwa House Industry leaves you on the fence, treat it as a prompt to move quickly. Review the underlying data and pressure test both the downside and upside drivers for yourself with the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Daiwa House Industry?
If Daiwa House Industry has sharpened your focus, use that momentum to scan broader opportunities and pressure test how your portfolio lines up against fresh ideas.
- Target higher potential income streams by reviewing companies on the 27 dividend fortresses that combine yield with robust underlying metrics.
- Hunt for mispriced quality by checking the 74 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
- Dial down portfolio risk by scanning the 20 resilient stocks with low risk scores and see which businesses score well on resilience when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com