


EN
Clover Health Investments (CLOV) On Raised Guidance And Profitability Still Looks Undervalued
Clover Health Investments: Why New Guidance And Leadership Matter For Investors
Clover Health Investments (CLOV) just paired higher 2026 guidance with a profitable third quarter, a combination that puts fresh attention on how the business is managing scale and medical costs.
The insurer now expects 2026 revenue between US$2.97b and US$3.00b, with GAAP net income projected in the US$25 million to US$35 million range. That update arrived alongside third quarter figures showing US$759.3 million of revenue and US$6.44 million of net income.
Over the first nine months of 2026, Clover Health Investments reported US$2,251.66 million in revenue and US$61.77 million in net income. Earnings per share from continuing operations for that period were US$0.12 on a basic basis and US$0.11 on a diluted basis.
Leadership at the finance desk is also shifting. Joseph Clay Thornton, previously interim Chief Financial Officer and principal financial officer, became permanent CFO on 4 November 2026, while Joseph Frank Oldakowski moved into the Chief Accounting Officer role on the same date.
Investors have reacted positively to the recent guidance increase and return to profitability at Clover Health Investments, with the share price up 102.9% year to date and a 1-year total shareholder return of 98%, even though the share price declined 1.61% in the latest trading session following the update.
Compare Clover Health Investments with a hand picked group of peers that also lean on strong fundamentals and balance sheets by scanning the list of solid balance sheet and fundamentals (23 results).
The question now is simple. After a very strong year and upgraded 2026 targets, does Clover Health Investments still offer a skewed payoff in favour of new buyers at this price, or has most of the upside already been used up?
Most Popular Narrative: 11% Undervalued
On the analyst consensus Narrative on Simply Wall St, Clover Health Investments screens as undervalued, with a fair value of $5.50 against the last close at $4.89. That gap frames how the story links membership, cost control, and technology into a single thesis.
The company's differentiated technology-driven care model, particularly the Clover Assistant platform, positions it to benefit from the healthcare industry's accelerated shift toward technology adoption and data-driven, value-based care, supporting lower medical costs and higher medical margins, with positive implications for both revenue and net margins.
See why 47 investors see Clover Health Investments as 11% undervalued.
Result: Fair Value of $5.50 (UNDERVALUED)
Still, the narrative around Clover Health Investments can be knocked off course if outpatient utilization stays elevated or if further adverse reserve adjustments hit reported earnings.
Find out about the key risks to this Clover Health Investments narrative.
Another View: DCF Puts Clover Health Investments In A Different Light
While the analyst narrative tags Clover Health Investments as undervalued around a US$5.50 fair value, the SWS DCF model points in the opposite direction. At a share price of US$4.89, the stock sits above an estimated future cash flow value of US$3.41, which flags less upside room and more downside risk if cash generation disappoints.
This kind of gap between a story built on earnings forecasts and one grounded in discounted cash flows raises a simple question for you: Which set of assumptions do you trust more when the two do not match?
Look into how the SWS DCF model arrives at its fair value.
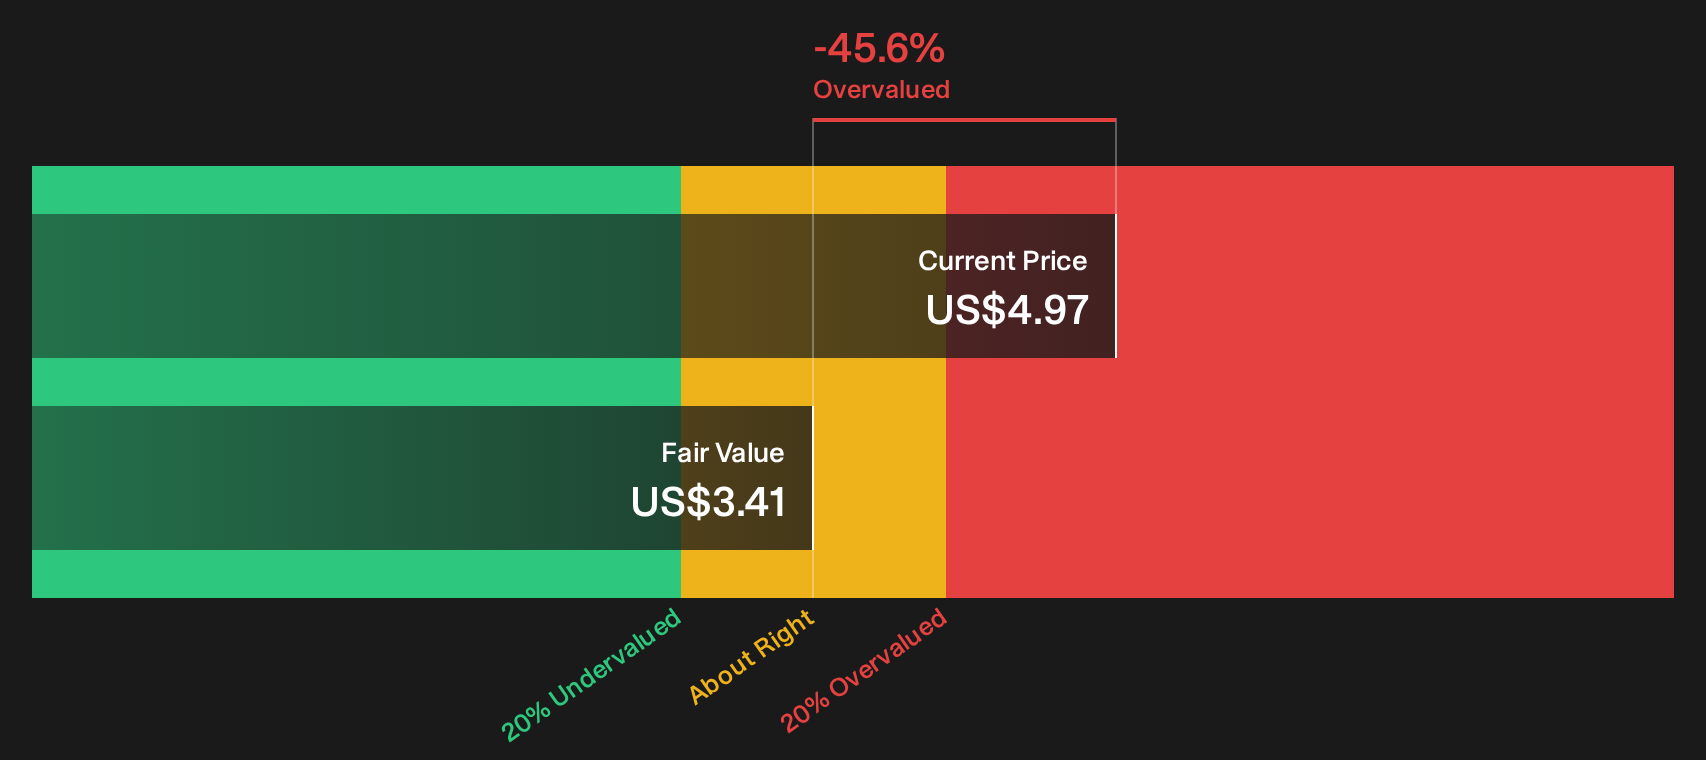
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Clover Health Investments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Clover Health Investments is mixed, with real risks and clear potential pulling in opposite directions. Move quickly, ground your view in the underlying numbers and disclosures, then weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Clover Health Investments?
If you stop with Clover Health Investments, you risk missing other opportunities that fit your style. Let the data do the heavy lifting and upgrade your shortlist.
- Target potential bargains early by scanning companies that look mispriced on quality and valuation using the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer robust yields through the 6 dividend fortresses.
- Reduce portfolio shocks by filtering for sturdier businesses with the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com