


EN
Did Share Buyback Approval Just Shift Nippon Gas' (TSE:8174) Investment Narrative?
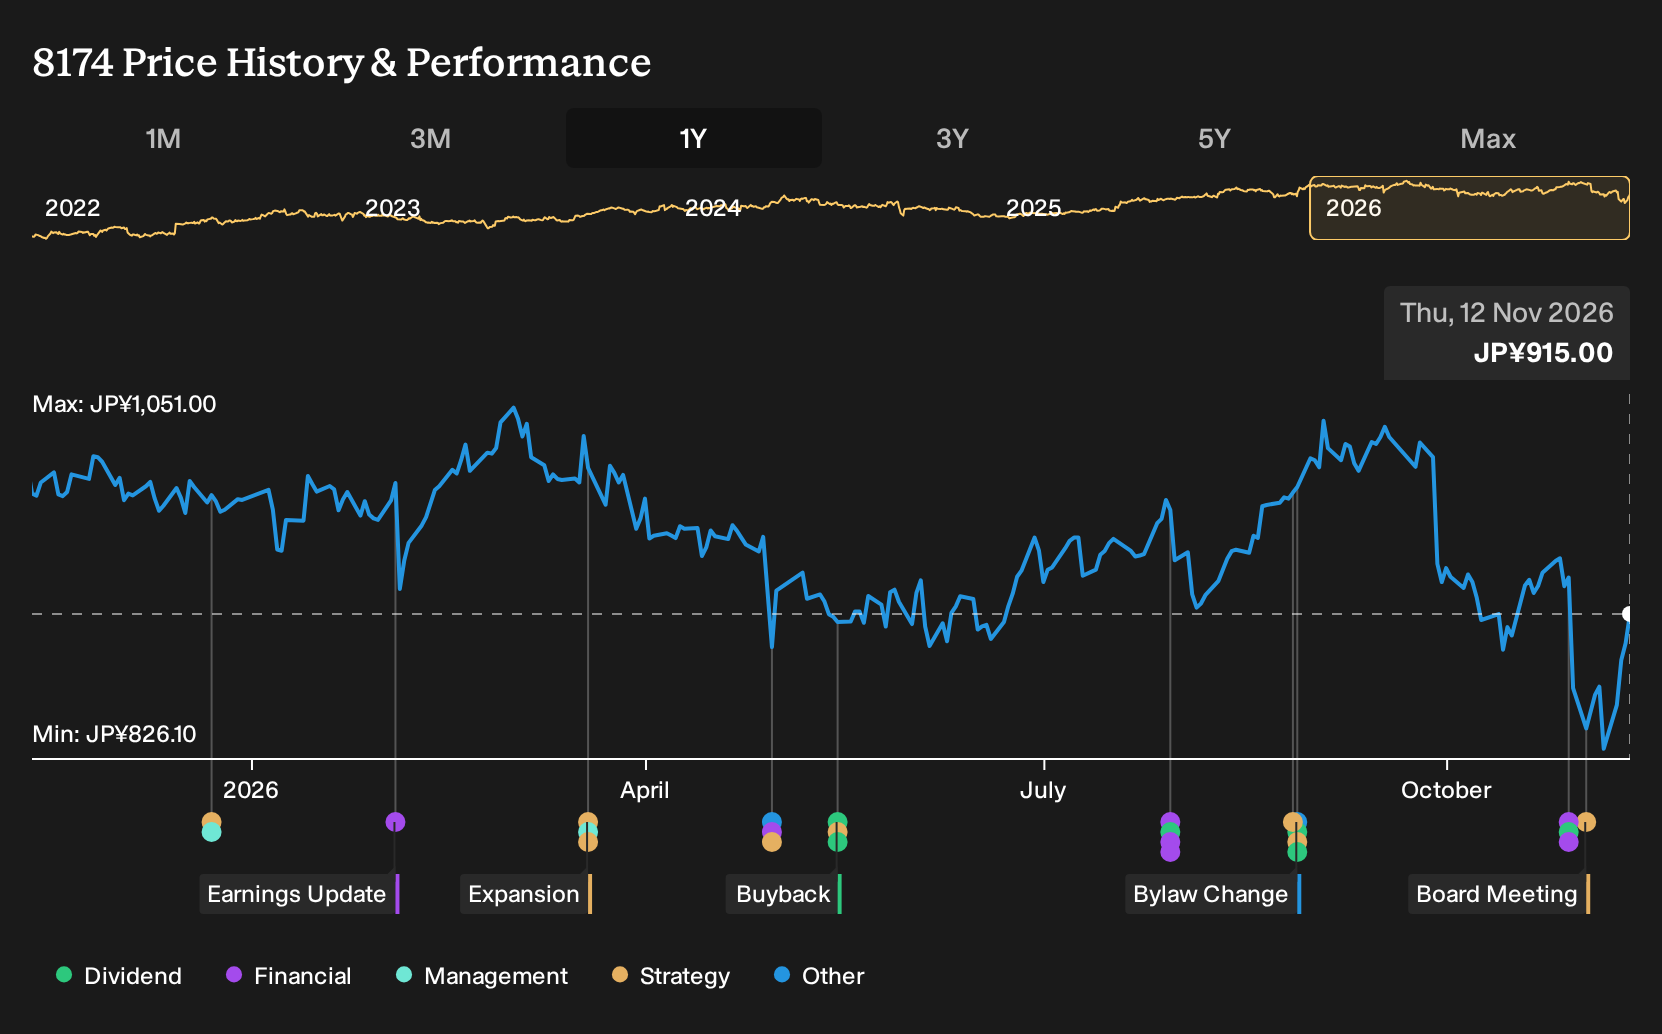
- Nippon Gas held a board meeting on 31 October 2026 that approved a share repurchase plan, signaling a concrete capital allocation decision by management.
- The buyback approval highlights that Nippon Gas is prioritizing balance sheet flexibility and shareholder returns rather than committing funds to new external expansion.
- This article will examine how Nippon Gas's investment narrative is shaped by this newly approved share repurchase and what that may mean for investors.
Compare Nippon Gas' renewed focus on shareholder returns with other companies using aggressive capital return policies by scanning our curated list of 27 dividend fortresses.
What Is Nippon Gas' Investment Narrative?
Nippon Gas is essentially an execution story. You are betting that a regulated, capital intensive utility can keep earning solid returns on its LP gas and city gas infrastructure while slowly widening its earnings base. The recent board approval for a share repurchase points to management choosing to recycle cash back to shareholders rather than leaning hard into new external projects. In the near term, that leans into the existing setup of steady gas demand, measured revenue growth of 2.6% a year, and a business that already runs at a high 21.9% return on equity.
The repurchase plan also interacts with two sensitive areas. Debt is already meaningful and all liabilities come from higher risk funding sources, so extra buybacks tighten the margin for error if conditions turn. On the flip side, Nippon Gas is trading at ¥915, well below an internal future cash flow value estimate of ¥1,523.42. That sort of gap often underpins these capital return decisions. Earnings have been growing, although at 6.7% over the past year they run below the 5 year average, so the real test is whether management can keep that trajectory intact while shrinking the equity base.
Yet there is an awkward detail in this otherwise tidy capital return story that could matter far more than it first appears...
There's only one way to know the right time to buy, sell or hold Nippon Gas. Head to Simply Wall St's company report for the latest analysis of Nippon Gas's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippon Gas research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nippon Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Gas' overall financial health at a glance.
Looking For More Ideas Beyond Nippon Gas?
If you want to stress test your thesis on Nippon Gas against other opportunities, it helps to scan a broader field of companies with clear financial traits and different risk profiles.
- For potential mispriced opportunities with quality fundamentals, run your filters across 18 high quality undervalued stocks that might warrant a closer look.
- If capital preservation and steadier profiles matter most to you, focus on companies in our 20 resilient stocks with low risk scores to see which ones fit your comfort level.
- When you want resilient balance sheets and cleaner fundamentals, compare Nippon Gas with the companies in our list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com