


EN
British Growth Stocks To Watch In November 2026
With global regulators pushing for clearer climate and risk disclosure, investors are getting more transparent information about balance sheet strength and future earnings potential. That gives well funded high growth British companies a chance to stand out as capital looks for cleaner stories and fewer surprises. This article highlights three stocks from our healthy high growth screener that analysts currently cover and for which they publish earnings forecasts for the next 3 years.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthier, high growth potential businesses that combine earnings ambitions with relatively solid finances. However, if you want the top choices within this theme, these 8 best high growth potential stocks are the best of the best.
Burberry Group (LSE:BRBY)
Overview: Burberry Group is a British luxury house that designs, manufactures and sells higher margin apparel, accessories and leather goods through its own stores, digital channels and wholesale partners.
Operations: Burberry generates about £2.4b in revenue mainly from Retail/Wholesale at £2.36b, with £62 million from Licensing across global regions.
Market Cap: £4.2b
Burberry Group taps the Healthy high growth potential theme through its focus on higher margin, brand led luxury retail, and the analyst consensus Narrative on Simply Wall St captures how that story currently links to its earnings outlook.
"The Burberry Forward focus on brand elevation and a Timeless British Luxury positioning is now linked with double digit growth in hero categories such as outerwear and scarves, along with higher full price sell through, which can support further revenue growth and gross margin improvement."
What really shapes Burberry Group’s potential is how one unseen pressure either protects that margin rebuild or quietly chips away at it.
That pressure is exactly what the full narrative for Burberry Group unpacks, showing where margin repair could accelerate, stall or be quietly masked by headline revenue trends.

Man Group (LSE:EMG)
Overview: Man Group is a global investment manager that runs quantitative, long only and alternative funds aiming to grow fee based earnings.
Operations: Man Group generates about $1.7b in revenue from its Investment Management Business, which is tied to fees on client assets.
Market Cap: £3.5b
Man Group matters for this Healthy high growth potential theme because its AHL, GLG and liquid alternatives platforms turn growing client assets into scalable fee income, and the analyst consensus Narrative on Simply Wall St frames how that earnings engine could build from here.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026, plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
The key question is how one unresolved shift in where new money flows, and on what terms, shapes that future profit pool.
That shift in fresh capital is exactly what the full narrative for Man Group unpacks. It reveals where Man Group’s fee engine could accelerate or quietly stall next.

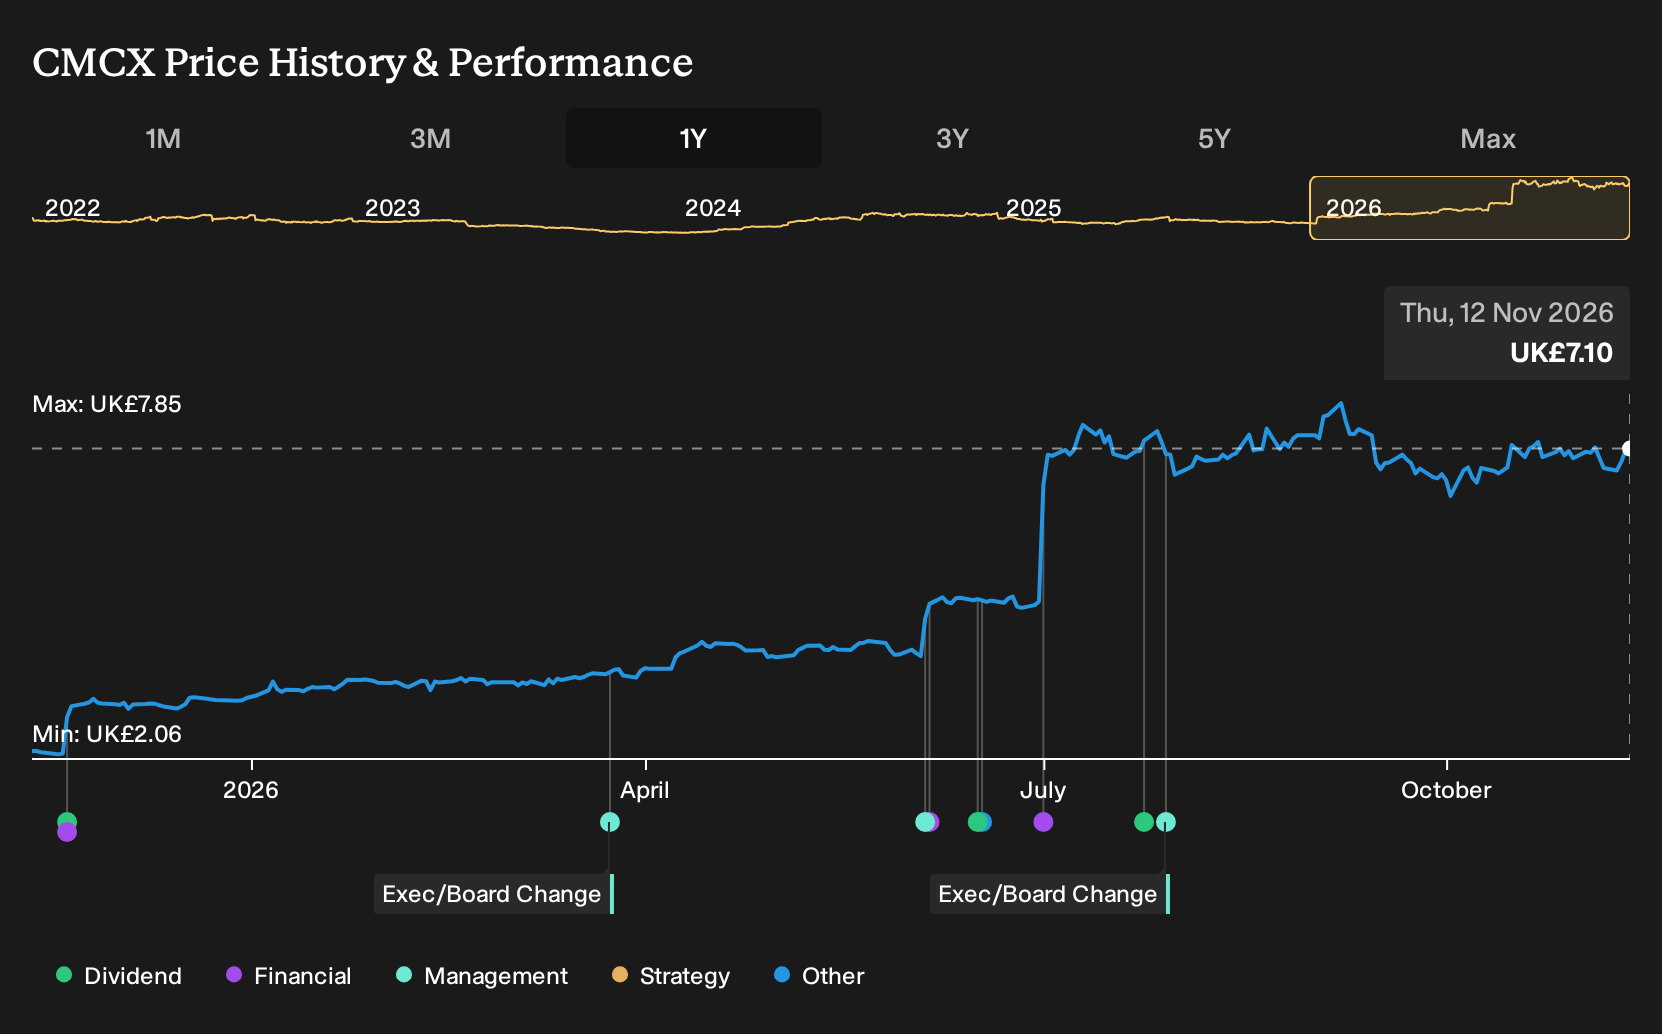
CMC Markets (LSE:CMCX)
Overview: CMC Markets runs online trading and investing platforms that let retail, professional and institutional clients access leveraged markets globally.
Operations: CMC Markets generates about £319.6 million from Trading and £70.1 million from Investing across the UK, Australia and other regions.
Market Cap: £1.9b
CMC Markets links into the Healthy high growth potential theme through its high margin Trading arm. A scalable online platform ties growing client activity to earnings power, and the analyst consensus Narrative on Simply Wall St sets out how that digital engine could evolve from here.
"Expansion of CMC Markets' institutional and B2B partnerships with Tier 1 banks and neobanks, including relationships with ANZ, Westpac, Revolut and ASB, is increasing wholesale and platform driven activity and can support higher net operating income and profit margins over time."
The real swing factor is what happens if one assumption about that future institutional order flow and cost base calibration fails to hold.
If that core assumption is starting to look fragile or accelerating, the full narrative for CMC Markets explains how CMC Markets' earnings story could be quietly reshaped.
Seeking Fresh Alternatives Before Others Do
Some opportunities move from quiet to crowded quickly. Fresh ideas gain momentum, prices start flying, and the best entry points get caught by early movers. Consider acting early rather than waiting.
- Target resilient cash generators and use the list of solid balance sheet and fundamentals (9 results) to scan for businesses where robust finances support staying power when momentum shifts.
- Hunt for potential income workhorses and tap into the 5 dividend fortresses that filters for higher yielding payers built on sturdier balance sheets.
- Pursue under the radar future themes and let the 25 quantum computing stocks surface focused plays in a niche many investors still overlook.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com