


EN
Should Design Platform Launch Require Action From Cadence Design Systems Stock Investors?
- Cadence Design Systems recently launched the OrCAD Xplore Design Platform, a connected environment that combines component research, verified libraries, AI tools and procurement to simplify the path from evaluation to production-ready PCB designs.
- The platform pulls supply-chain intelligence and DigiKey purchasing directly into OrCAD X Capture, which can cut manual component work and reduce rework for engineers managing complex electronic systems.
- We will now see how Cadence Design Systems' investment narrative could be influenced by OrCAD Xplore's AI driven and supply chain aware design workflow.
Cadence Design Systems Investment Narrative Recap
To own Cadence Design Systems, you need to believe that AI heavy chip and system complexity keeps pushing customers toward richer tool flows, and that Cadence turns that need into durable, high margin software and IP revenue. The analyst consensus Narrative on Simply Wall St leans heavily on agentic AI super agents, high recurring revenue and a US$8.1b backlog to support that view. The near term swing factor is whether operating margins hold up as Hexagon Design & Engineering adds US$20m to US$25m of costs in the back half of 2026.
That is where today’s risk sits. A premium P/E, insider selling of roughly US$67.5m over three months and extra Hexagon integration expense all mean any wobble in growth or profitability could hit the share price quickly. OrCAD Xplore itself looks more incremental than transformational to the short term story. The bigger questions are still execution on AI agents, integration delivery and China or export control exposure.
The OrCAD Xplore launch connects cleanly with the existing AI and systems design catalyst that analysts focus on. It pushes Cadence Design Systems further into supply aware, AI assisted workflows inside PCB and system design, which lines up with the push into agentic AI super agents like ChipStack and ViraStack. Tighter integration between front end design, verified libraries and procurement can help customers reduce rework and keep projects on schedule.
Among the recent items, the Expedera collaboration around the Tensilica NeuroEdge 130 AI co processor feels most relevant. It keeps Cadence silicon IP and AI compute blocks in the conversation for edge inference designs across smartphones, autos and data centers. That sort of IP adoption is one of the core catalysts analysts look for, because it supports higher value content per design and can offset risks such as Hexagon dilution and any pressure from export controls.
Cadence Design Systems' current analyst narrative points to revenues of US$8.4b and earnings of US$2.0b by 2029, based on an assumed 12.9% yearly increase in revenue and a move in earnings from US$1.4b today to that US$2.0b figure, which is about a 43% uplift in profit.
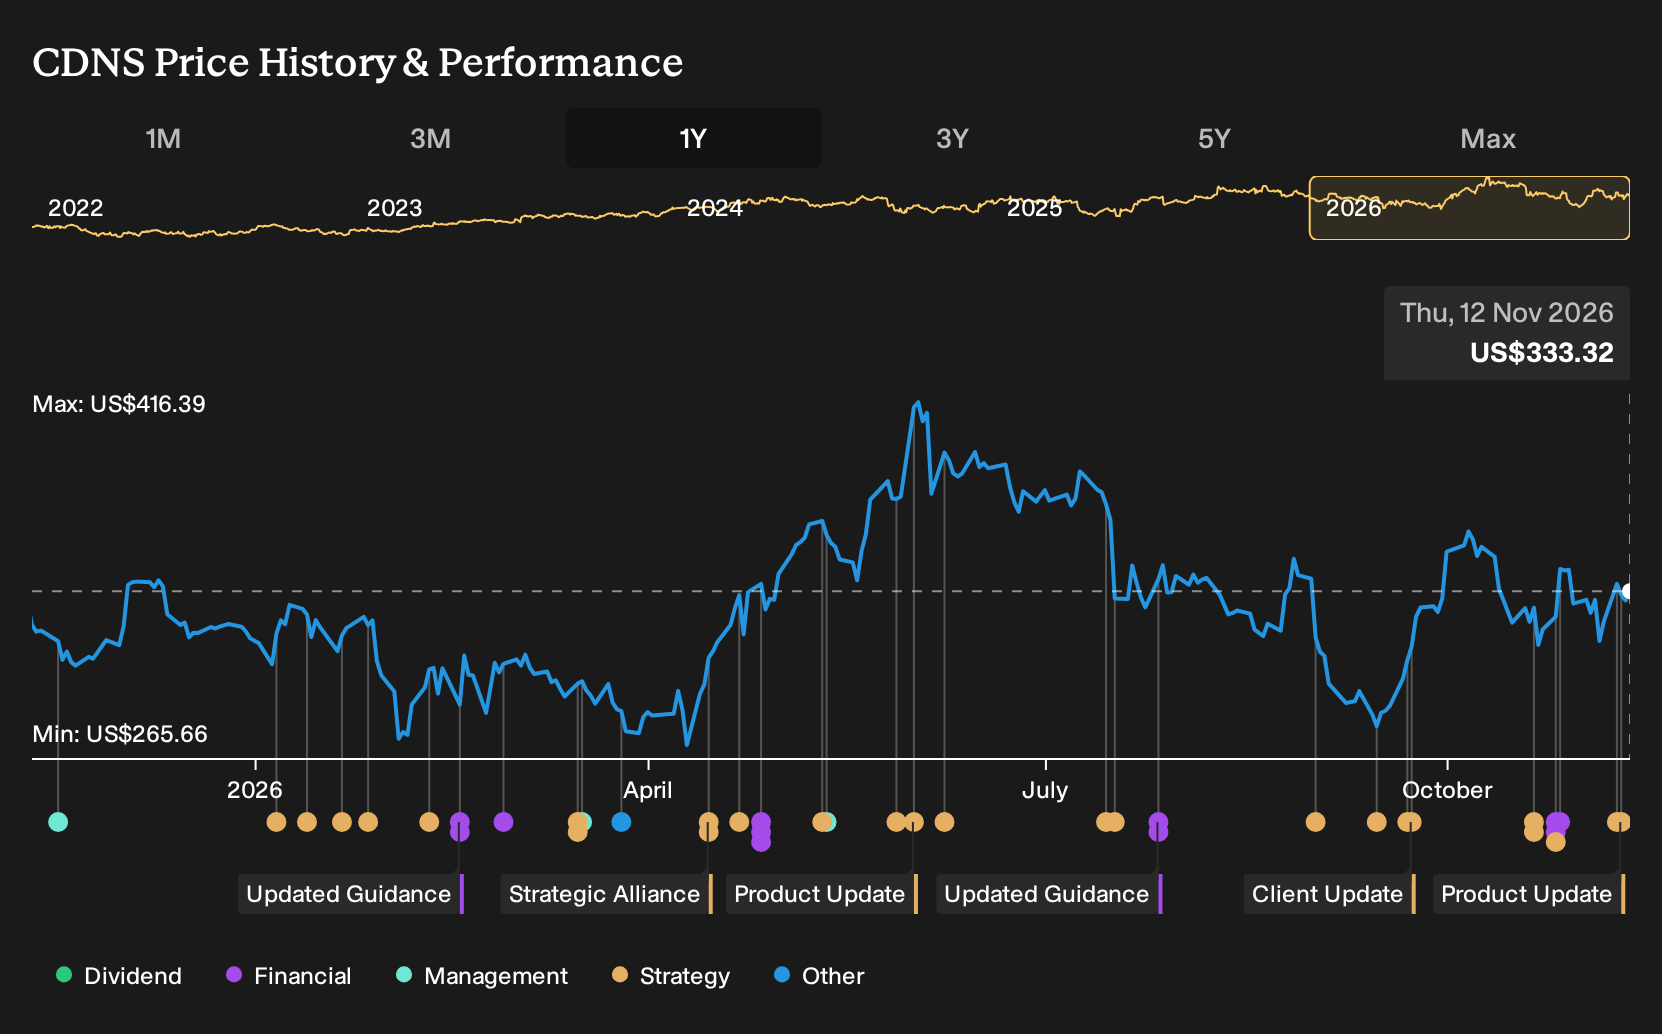
Uncover why Cadence Design Systems' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame OrCAD Xplore as fuel for Cadence Design Systems' AI tool and IP flywheel, not just a PCB add on. Before this launch, that group was already penciling in revenues of about US$9.3b and earnings near US$2.7b by 2029. You might see those forecasts shift if this connected, supply aware workflow wins or disappoints, so it is worth comparing several viewpoints rather than relying on a single story.
Explore 5 other Cadence Design Systems fair value estimates, including one that suggests up to 41% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Cadence Design Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cadence Design Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cadence Design Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cadence Design Systems?
If the Cadence Design Systems story has sharpened your thinking about AI, cash flows and risk, it can help to widen the lens and compare it with other opportunities that fit different portfolio goals.
- For investors who care most about quality at a reasonable entry point, start with a focused group of 31 high quality undervalued stocks that already pass strict fundamental filters.
- If capital preservation and a smoother ride matter more to you than chasing every swing, consider a basket built from 29 resilient stocks with low risk scores that score well on resilience metrics.
- When you want sturdier balance sheets and cleaner accounts to anchor a portfolio, scan our list of solid balance sheet and fundamentals (23 results) to see which businesses currently fit that brief.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com