


EN
What PVA TePla Doubters Overlooked
If you only skimmed PVA TePla headlines about higher 2026 revenue and a swing from a small quarterly loss to a modest profit, you might not expect the shareholder outcome that followed. For PVA TePla shareholders, the return over the past year was 31.6%, including dividends. If you had been weighing those bullish and bearish analyst notes back in November 2025, what exactly in the business record would have justified taking that risk?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put PVA TePla in the middle of this trade. Scan 85 robotics and automation stocks for other companies exposed to it.
The Two Stories Investors Had To Choose Between On PVA TePla
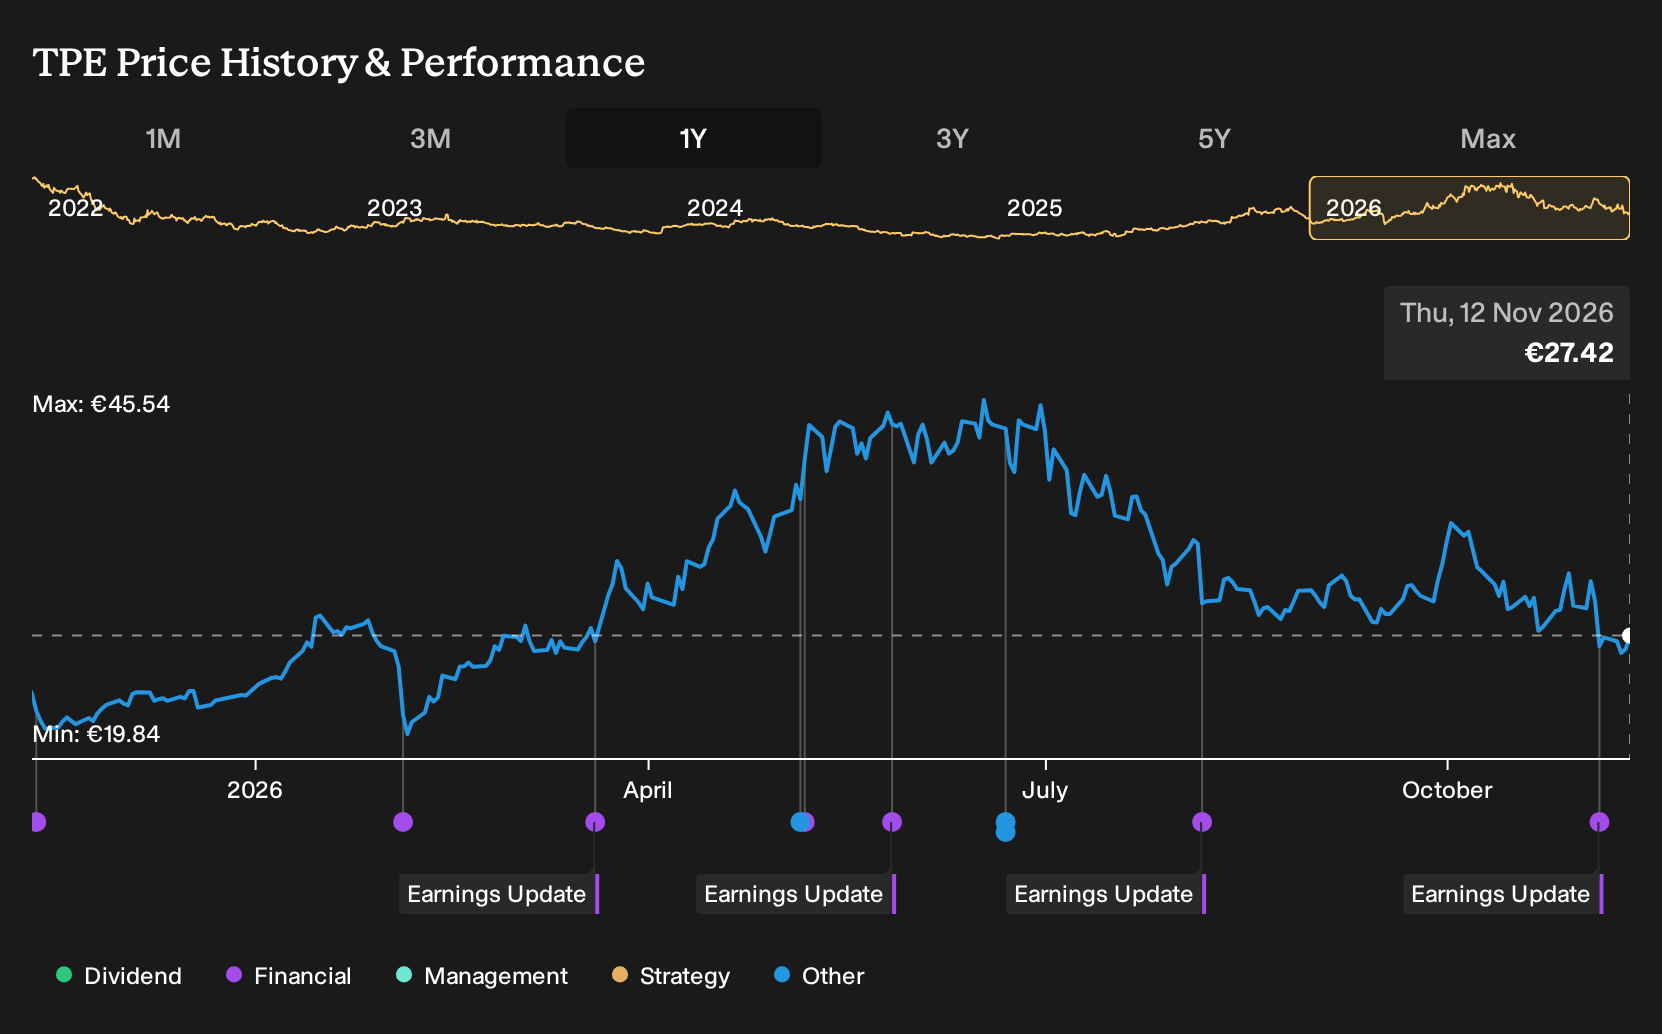
The shares cost €21.64 at the start of the period, and anyone looking at PVA TePla then had two very different stories on the table.
The bullish narrative pointed to a fair value of €27.46, 27% above the start price, anchored in the idea that revenue could grow 15.2% with profit margins reaching 10.0% and a future P/E of 16.0x.
The bearish view saw fair value at €15.50, 28% below the start price, and focused on revenue growth of 8.3%, with margins easing to 7.2% and a future P/E of 15.1x amid geopolitical and regulatory pressure.
What The Results Changed For PVA TePla
The clearest new fact for PVA TePla was the Q3 2026 result. Revenue was €62.689m and net income moved from a small loss to a profit of €0.763m, lifting net margin from roughly 0.0% to 1.2%. That supported the optimistic case on direction, although profitability stayed far below the 10.0% margin that the bullish story used as a reference point.
The two AGM headlines and the Morgan Stanley stake change gave investors extra context on growth plans and shareholder backing, but they did not settle the earnings debate. The lesson is simple: when a thesis leans on margin expansion, track net margin in each report and compare it directly with the percentage in the original assumption.
What PVA TePla's Price Now Asks You To Believe
PVA TePla trades at €27.42 today, after a 31.6% gain over the past year. The analyst consensus Narrative on Simply Wall St sets its Fair Value above that level, based on how current orders might reshape earnings power.
The Narrative argues the price still underplays execution on metrology backlog and new materials projects converting into steadier, higher quality profits.
"PVA TePla is focusing on expanding its high-margin metrology business, now backed by record metrology order intake of €62.7m in Q1 2026 and first in-fab HBM and logic orders scheduled into 2027. This supports potential improvement in net margins and earnings as this backlog converts."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where PVA TePla’s Demand Rhymes
PVA TePla points you toward one corner of the AI buildout. Nearby, another company quietly tackles a different constraint.
Advanced AI systems need more than process control and metrology. They also rely on specialist memory that keeps data extremely close to computation.
An anonymous manufacturer concentrates on that layer, providing working storage tuned for intense, continuous access.
As AI workloads press against existing capacity, its focus highlights memory’s shift from interchangeable component toward durable infrastructure.
That unresolved shift leaves a key question: how central does this hidden layer become?
That argument has a Narrative and a number behind it. → See the company one Narrative values 57% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com