


EN
NextDecade (NEXT) Turns Profitable In Q3 On A Valuation Test
NextDecade (NEXT) just swung from a third quarter loss to net income of US$155.38 million, with positive basic and diluted earnings per share from continuing operations. This shift has put the latest results squarely in the spotlight for investors.
At a share price of US$6.54, NextDecade has posted a 1-day share price return of 2.99% and a 7-day share price return of 4.64%. The 30-day and 90-day share price performance has slipped slightly. However, the year-to-date share price return of 21.56% and 3-year total shareholder return of 36.25% indicate that momentum has generally been building as investors react to the earnings turnaround.
Scan beyond NextDecade's earnings swing by comparing it with hand picked energy peers in the 16 nuclear energy infrastructure stocks, which are also tied to large scale infrastructure build outs.
The earnings swing has already pushed NextDecade higher, yet the share price still sits below published analyst targets. Investors may now be asking whether most of the rerating is already reflected, or whether the recent move leaves more room in the valuation work ahead.
Most Popular Narrative: 41% Undervalued
The bullish analyst Narrative on Simply Wall St sets a fair value of $11.00 for NextDecade, which sits well above the last close at $6.54 and frames the latest earnings swing as just one part of a much bigger Rio Grande LNG story built on optimistic forecasts and pricing assumptions.
The decision to keep roughly 1,100 TBtu of early ramp up LNG volumes unhedged, including about 700 TBtu between Q1 2029 and Q2 2031, leaves meaningful exposure to possible upside in a tight market for physical cargoes and can significantly affect realised net margins and distributable cash flow.
See why 6 investors see NextDecade as 41% undervalued.
Result: Fair Value of $11.00 (UNDERVALUED)
Still, the bullish NextDecade narrative can crack if ongoing net losses force more equity issuance, or if Rio Grande LNG cash flows lag against its growing debt load.
Find out about the key risks to this NextDecade narrative.
Another View: What NextDecade’s P/B Ratio Is Saying
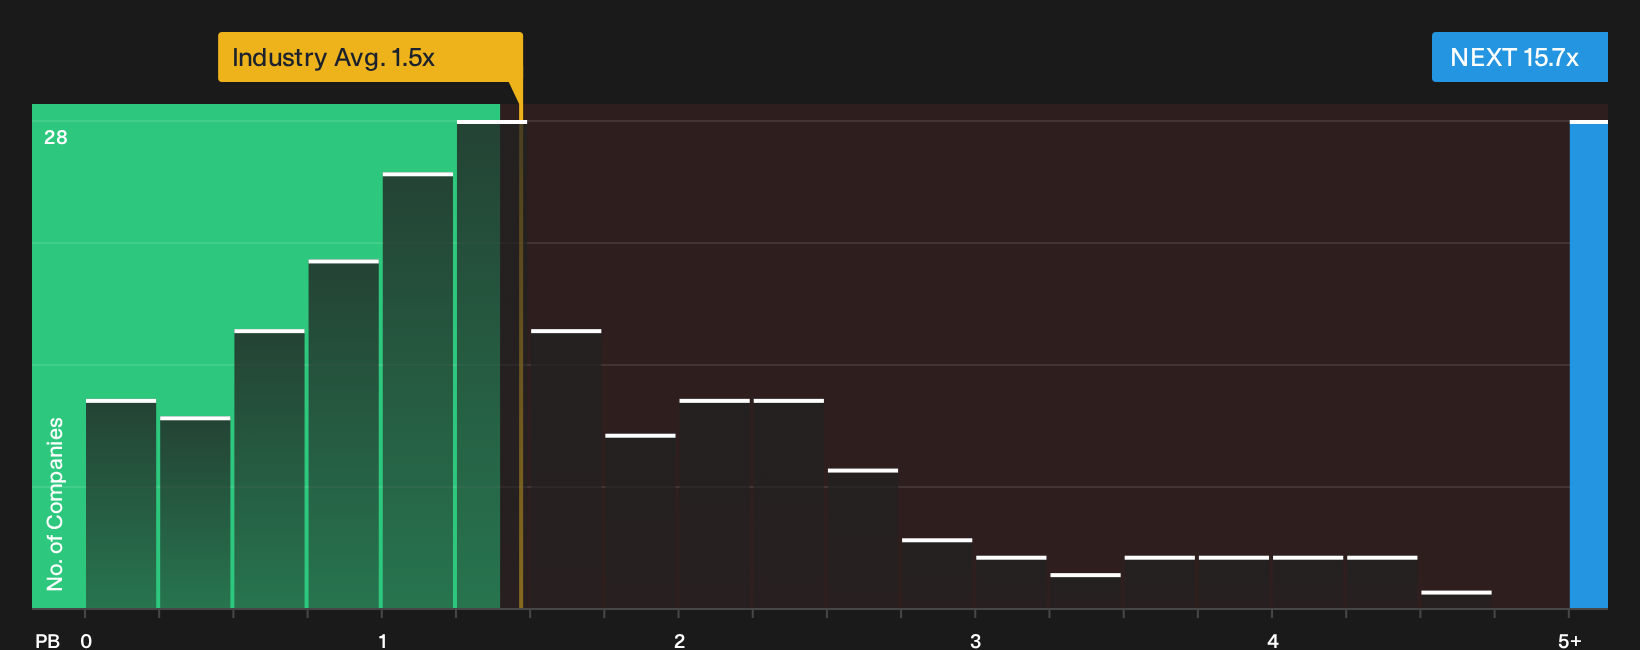
The bullish fair value for NextDecade leans heavily on future LNG cash flows, yet today the stock trades on a P/B of 15.7x versus 1.4x for the wider US Oil and Gas group and 2.1x for peers. That is a steep premium for a loss making business with no current revenue and less than one year of cash runway. The real question is whether investors are being paid enough for that valuation risk.
To see how this price tag stacks up against the underlying numbers and where market expectations might be stretched, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the upbeat fair value story and the stretched P/B multiple for NextDecade? Move quickly, review the full data for yourself, and weigh both sides with the help of 1 key reward and 3 important warning signs
Looking for more investment ideas beyond NextDecade?
If NextDecade has sharpened your focus, do not stop here. Fresh ideas often come from scanning outside your comfort zone and comparing very different opportunities.
- Target potential mispricings by checking companies that pair strong fundamentals with attractive valuations through the 32 high quality undervalued stocks.
- Lock in income-focused ideas by reviewing a curated list of high yielding opportunities in the 6 dividend fortresses.
- Stay on the front foot by searching for financially resilient businesses with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com