


EN
RHI Magnesita And 2 British Dividend Stocks To Watch
The UK economy just posted 0.7% growth in the third quarter, with artificial intelligence related activity playing a big role. That kind of tech driven momentum puts reliable cash payers in an interesting spot. Investors looking for income may care more than ever about dividends that look durable, covered and steadily rising. This article walks through three high yielding UK dividend stocks that clear those hurdles.
The three stocks highlighted here offer a compelling starting point if you want exposure to income payers with 3%+ yields that look well covered, growing and relatively steady. However, if you want the absolute best, these 4 dividend aristocrats stocks are the cream of the crop.
RHI Magnesita (LSE:RHIM)
Overview: RHI Magnesita supplies high temperature refractory materials, services and recycling solutions that keep steel and other heavy industrial plants running safely and reliably, supporting the cash generation that underpins its 3%+ dividend profile.
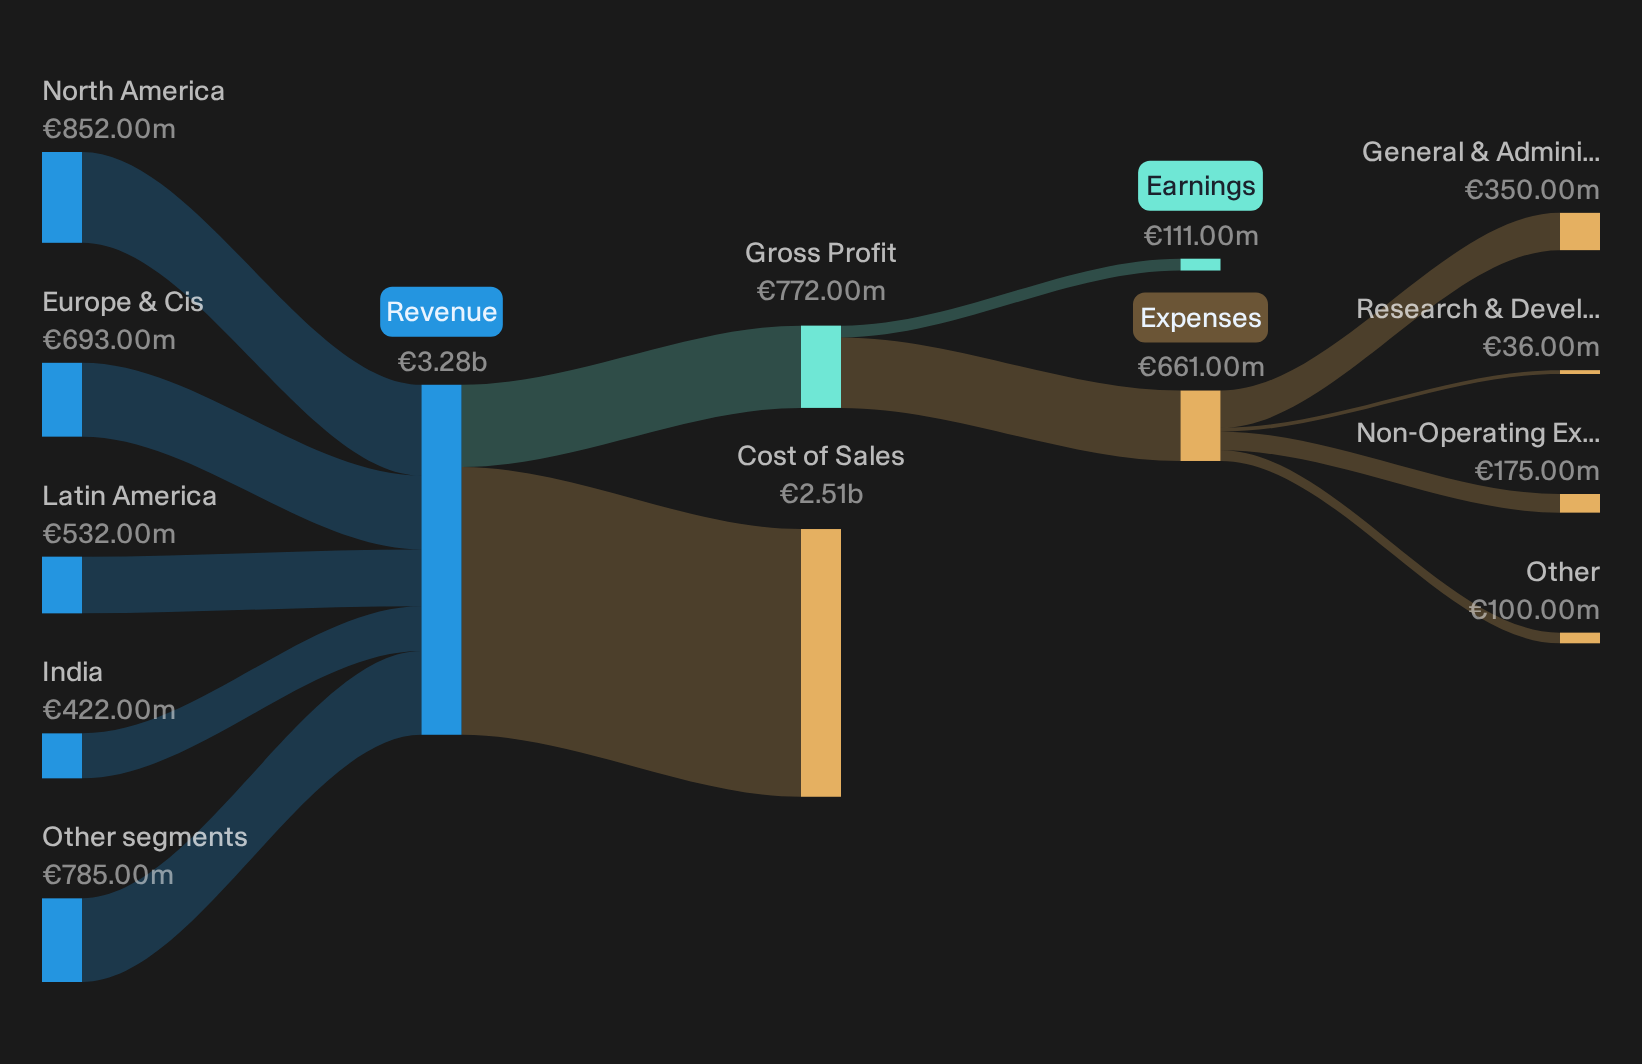
Operations: RHI Magnesita generated €3.3b revenue in 2026, led by North America at €852 million and Europe & CIS at €693 million, with meaningful contributions from Latin America, India and other regions.
Market Cap: £1.32b
RHI Magnesita matters to this dividend screen because its steel focused refractory contracts can create repeat business and cash flows that support a high, serviceable payout. The analyst consensus Narrative on Simply Wall St argues that self help on costs and recycling are central to that story.
"The company's leadership in developing circular economy solutions via new recycling infrastructure is still intended to attract more ESG focused customers and reduce raw material cost exposure. This can support both sales volumes and gross margins as recycling usage increases."
What investors really need to watch is how one less visible cost pressure ultimately feeds through to margins and dividend breathing room.
That cost pressure is the real hinge, and the full narrative for RHI Magnesita sets out how recycling, pricing and capital allocation could reshape RHI Magnesita's dividend headroom for patient holders.
Man Group (LSE:EMG)
Overview: Man Group runs global long only and alternative investment funds, earning recurring management and performance fees that support its 3%+ dividend profile.
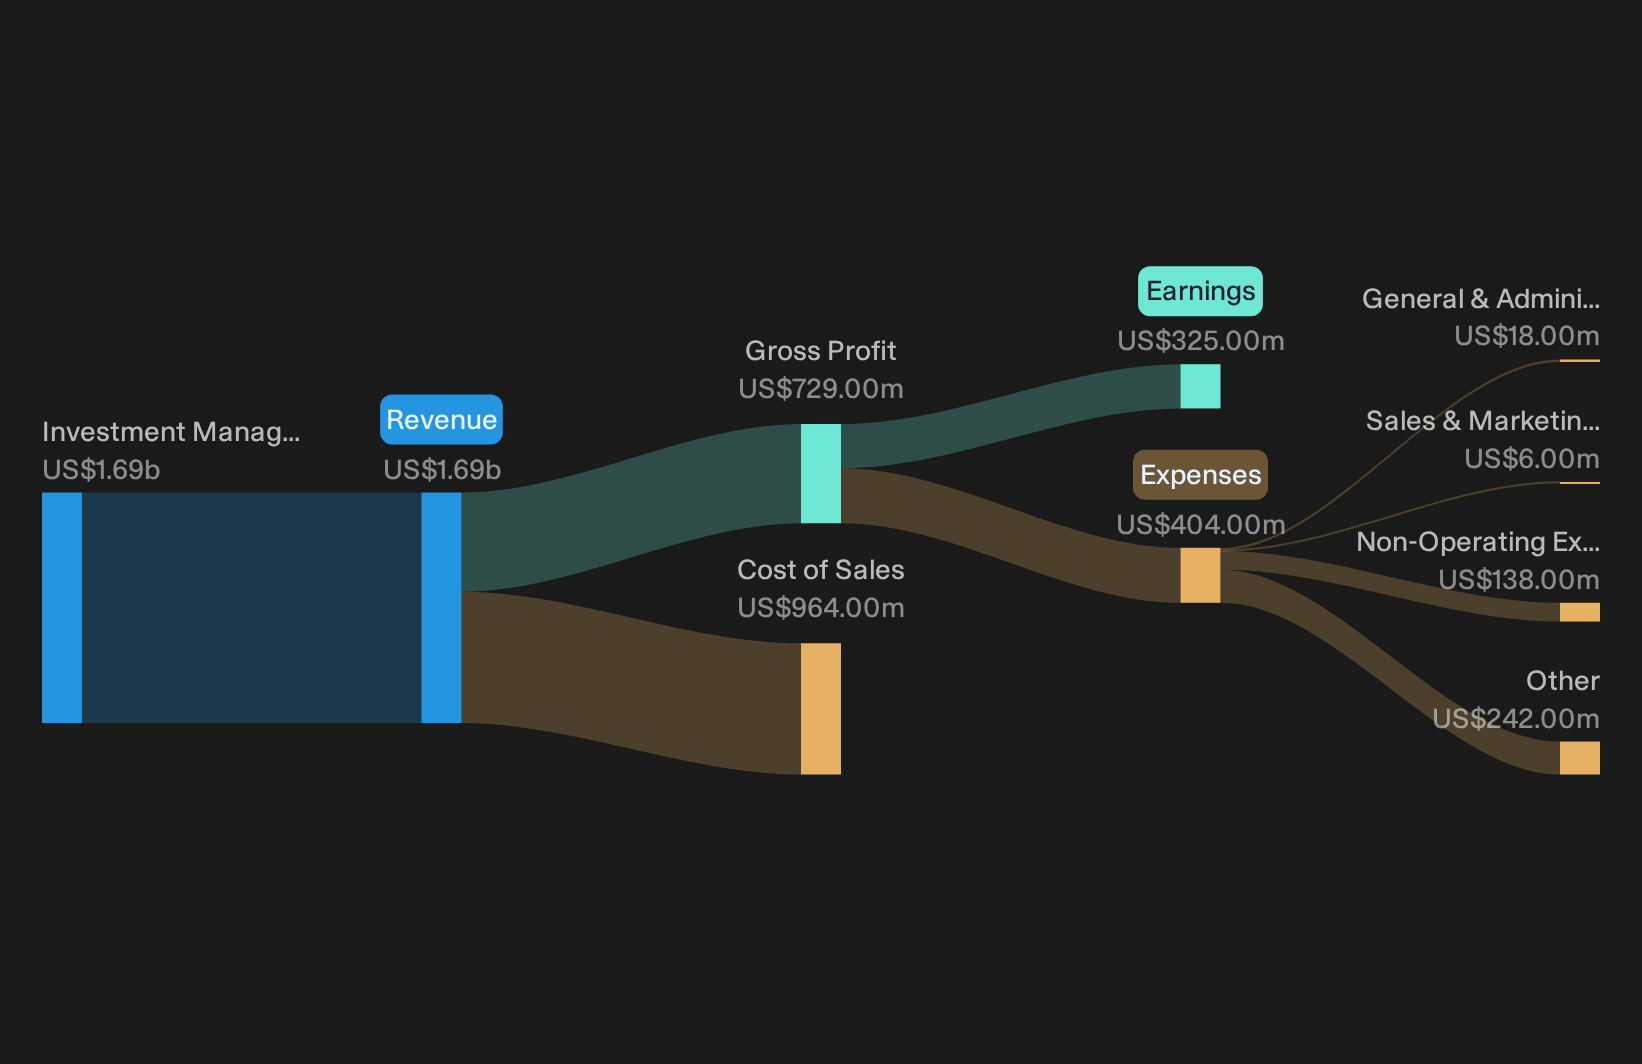
Operations: Man Group generated US$1.7b revenue from its Investment Management Business, largely driven by fees on client assets across multiple strategies.
Market Cap: £3.52b
Income investors looking at Man Group are really asking whether its fee engine can keep funding a well covered, rising dividend. The analyst consensus Narrative on Simply Wall St highlights how that fee pool is being reshaped by growth in credit and private markets.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
The real test now is how resilient dividend cover remains if one key source of fee momentum slows faster than many expect.
If that fee engine does slow, the full narrative for Man Group shows how Man Group could still keep dividend cover moving, using capital returns and risk levers that many overlook.
Grafton Group (LSE:GFTU)
Overview: Grafton Group runs building materials distribution and merchanting chains like Selco, Leyland SDM and Chadwicks, whose steady trade counter cash flows support its 3%+ dividend profile, alongside complementary DIY retail and manufacturing operations across several European markets.
Operations: Grafton Group produced about £1.13b revenue from the Island of Ireland, £746 million from Great Britain, £478 million from Northern Europe and £254 million from Iberia in its latest breakdown.
Market Cap: £1.94b
For income focused investors, Grafton Group matters because those merchanting branches and trade counters feed the dependable cash stream that backs its 3%+ yield. The analyst consensus Narrative on Simply Wall St now ties that income profile to how management uses its European footprint.
"Grafton Group's continued build out of its Iberian HVAC platform, now including both Salvador Escoda and Mercaluz with around 120 branches and a shared focus on own brand products, allows further branch openings, new customer channels and exports to support higher revenue and EBITA margins in the region."
The real swing factor is how one margin sensitive region handles cost inflation and demand softness that could quietly tighten future dividend cover.
If that squeeze on cover is what you care about, the full narrative for Grafton Group explains how Grafton Group could turn margin pressure into an accelerating income story.

Seeking Fresh Alternatives Before Others Do
Markets move fast and today's quiet opportunities can turn into tomorrow's crowded trades once momentum starts flying. Scan fresh ideas that are under the radar for now and consider them before they become widely followed.
- Target resilient payers with strong cash cushions by running the 4 dividend fortresses while yields still look appealing and the crowd has not fully caught on.
- Look for potential breakout compounders through the 5 high quality undiscovered gems before wider attention arrives and narrows the entry window available today.
- Track the next wave of infrastructure momentum using the 42 power grid technology and infrastructure stocks while valuations still reflect cautious sentiment instead of faster-moving optimism.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com