


EN
Does Goodwill Write Down Change The Bull Case For Bruker Stock (BRKR)?
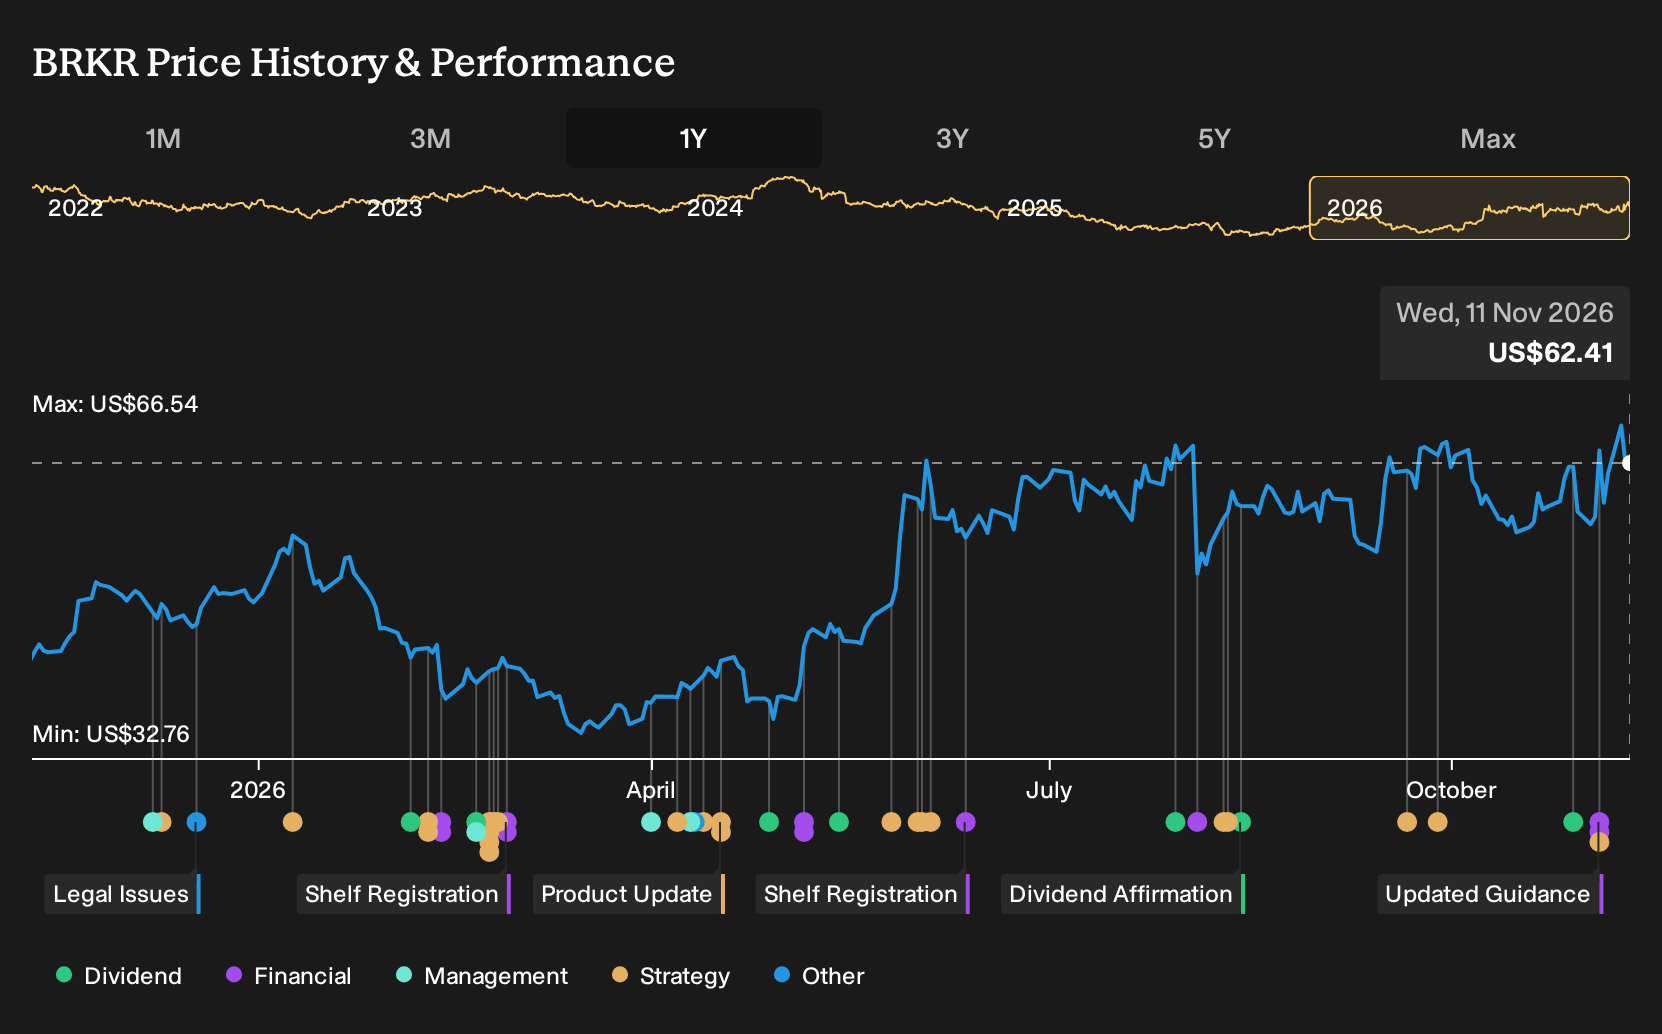
- Bruker reported third quarter 2026 results that showed sales of US$874 million and a net loss of US$111.8 million, alongside a US$174.5 million non cash goodwill impairment. The company also issued 2026 revenue guidance of US$3.52 billion to US$3.56 billion.
- The combination of higher goodwill write downs and continued losses, despite year to date sales of US$2,535.9 million, highlights pressure on Bruker to align past acquisitions and its current cost structure with its guided 2026 revenue trajectory.
- We will now look at how Bruker’s larger goodwill impairment and ongoing losses could reshape the investment narrative that was built before this update.
Scan how Bruker’s impairment hit compares with peers under pressure by reviewing the hand picked 30 resilient stocks with low risk scores that pair resilient balance sheets with more contained risk profiles.
Bruker Investment Narrative Recap
To own Bruker, you need to believe the core instrument and diagnostics platforms can convert modest reported revenue guidance of US$3.52b to US$3.56b for 2026 into a clearer path back to profitability. The near term swing factor is whether cost actions and mix shift can offset the recent net loss of US$111.8 million.
The biggest operational risk right now is that repeated goodwill impairments and loss making activities keep absorbing cash while debt is not well covered by operating cash flow, as flagged in the analyst consensus Narrative on Simply Wall St. If impairments remain largely non cash and underlying demand holds, the latest charge may not materially alter the short term thesis.
The most relevant update for this story is Bruker’s fresh 2026 revenue guidance of US$3.52b to US$3.56b, which implies reported growth against 2025 revenue of US$3.44b. For you, the question is whether this outlook is compatible with the large goodwill write down and the current loss making position.
That guidance now sits alongside a much larger non cash goodwill impairment of US$174.5 million for the third quarter and a year to date net loss of US$149.4 million. How management executes on the cost reduction and restructuring program, and how it manages underperforming businesses tied to past acquisitions, will shape whether that revenue range becomes a catalyst or a pressure point.
Bruker's narrative projects US$4.1b revenue and US$609.3 million earnings by 2029. This projection assumes 5.5% yearly revenue growth and an earnings increase of about US$776.6 million from current earnings of a US$167.3 million loss.
Discover how Bruker's fair value aligns with its current price.
Exploring Other Perspectives
One alternate Bruker storyline treats U.S. academic funding risk as the real swing factor. Those bearish analysts already plugged in slower revenue growth of 4.2% a year and 2029 earnings of about US$640.1 million. That is still optimistic on profits, yet more cautious than consensus, and today’s goodwill hit could push some views even lower.
Explore 2 other Bruker fair value estimates, including one that suggests up to 12% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bruker research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bruker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bruker's overall financial health at a glance.
Looking For More Bruker Investment Alternatives?
If Bruker now feels like only one piece of your watchlist puzzle, it can help to scan a wider field of stocks and compare business quality, balance sheet strength, and income potential side by side.
- If you want potential quality at a discount, start with companies that combine fundamental strength with pricing that still looks reasonable through the 32 high quality undervalued stocks.
- If capital protection sits high on your checklist, filter for businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results).
- If you are hunting for opportunities that may be off most radars, broaden your search with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com