


EN
Do Long Term Optical Deals Change The Bull Case For Corning (GLW)?
- Corning has secured several long term, multibillion dollar optical supply agreements with carriers including Verizon and AT&T and is expanding United States solar manufacturing. This reinforces its role in AI data center connectivity and domestic clean energy supply chains.
- Capital Group funds have increased their Corning exposure by adding the stock to portfolios and building larger positions, signaling confidence in the firm’s fiber, photonics and solar platforms as it works toward its Springboard operating targets.
- We will look at how Corning's investment narrative is shaped by long term optical contracts that tie directly into AI data centers.
Scan how Corning's AI data center story compares with other infrastructure plays by reviewing our hand picked list of 53 AI infrastructure stocks in one place.
What Is Corning's Investment Narrative?
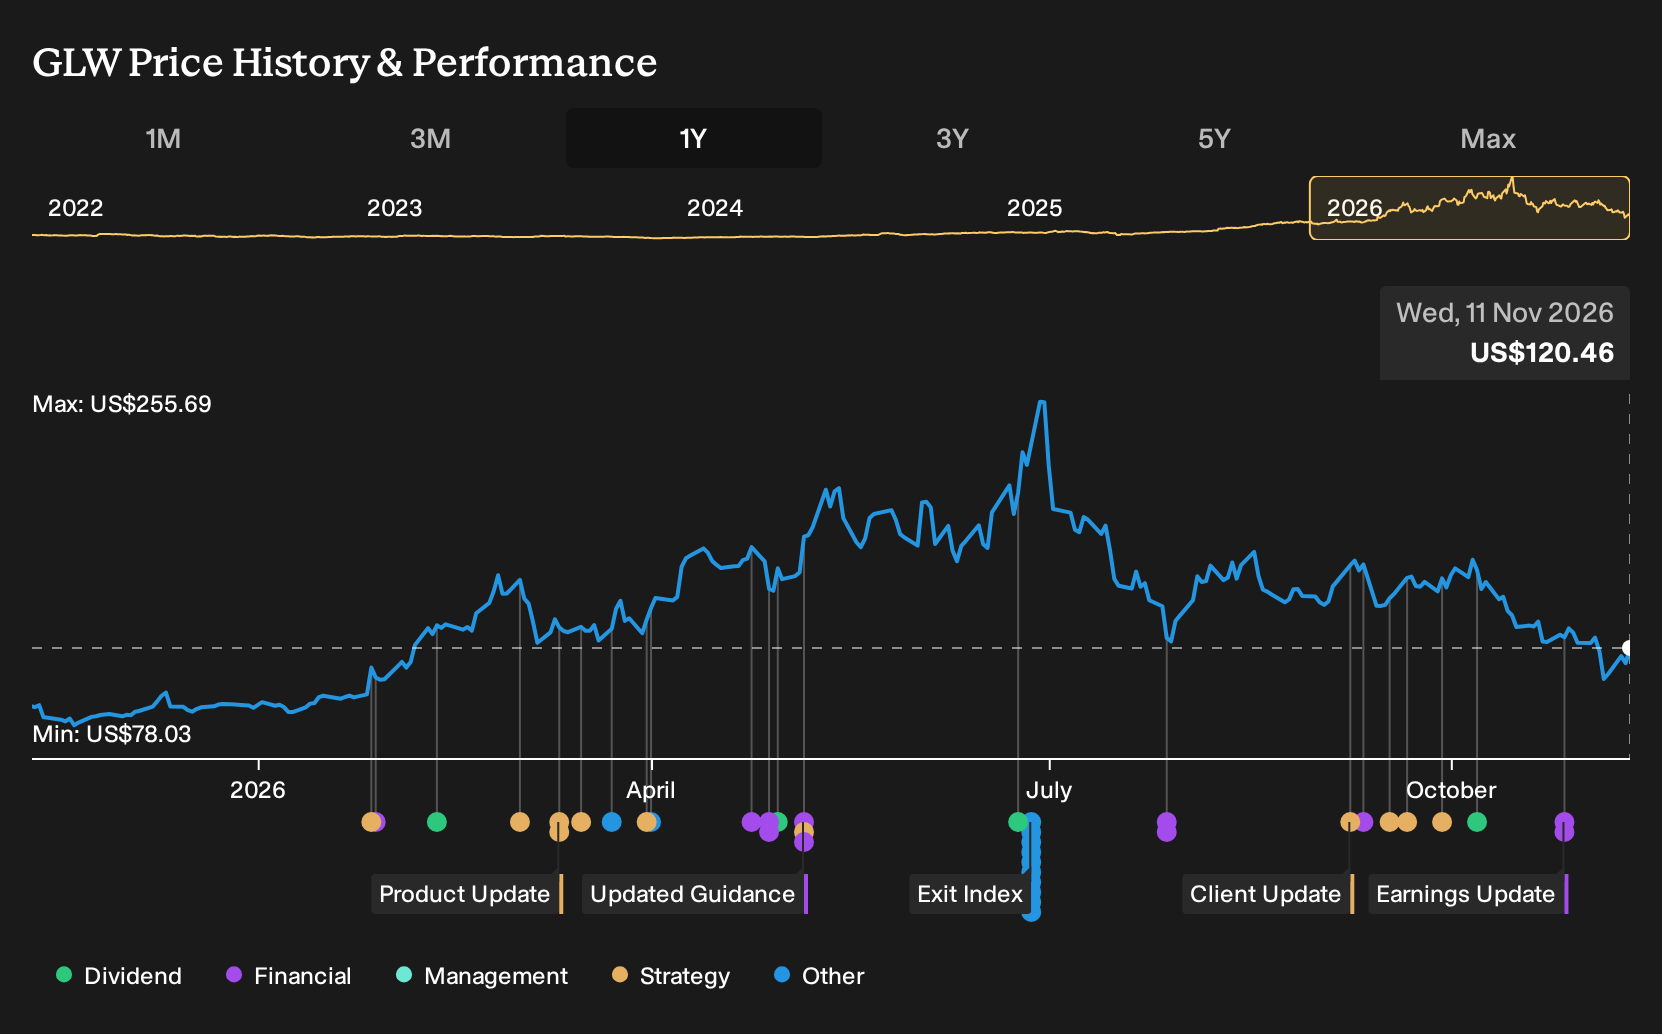
For Corning, the big picture you need to believe in is pretty simple. The thesis rests on durable demand for optical connectivity into AI data centers, steady execution on the Springboard efficiency plan, and the capital heavy choice to keep building out glass, fiber, and solar capacity. The stock has pulled back 28.4% over the last month even after a 36.5% total return over the past year, which tells you sentiment has cooled in the short term even as earnings and revenue have grown and net margin moved from 9.2% to 12.1%.
Those new multibillion dollar optical contracts and the ETF buying wave fit directly into the near term catalysts investors already watch. They speak to visibility on volume, not to what Corning can charge or how smoothly it can ramp factories to hit its Springboard targets. High capital intensity, a 48.3x P/E against industry at 26x, and significant insider selling in the past three months all keep execution risk front and center, even with forecasts calling for earnings growth of 28.8% a year and revenue running ahead of the broader US market.
Yet the cleaner story around Corning and AI infrastructure gets messier once you focus on one pressure point that rarely makes the headlines...
There's only one way to know the right time to buy, sell or hold Corning. Head to Simply Wall St's company report for the latest analysis of Corning's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts frame Corning’s heavy capital spending as the key upside catalyst. Before this news, the bullish camp was penciling in revenue climbing to about US$34.2b and earnings of US$7.4b by 2029. You can treat that as one possible path and compare it with more cautious views that may now shift.
Explore 6 other Corning fair value estimates, including one that suggests potential upside of up to 83% from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Corning research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
If you want to stress test your Corning thesis, the fastest way is to line it up against other potential opportunities. Use the Simply Wall St screener to scan different types of businesses, compare fundamentals side by side, and spot ideas that match your risk tolerance and return goals.
- For investors hunting for underappreciated quality, review companies that screen as attractively priced with strong fundamentals through our 32 high quality undervalued stocks.
- If capital preservation matters more to you than chasing the highest upside, focus on businesses that show resilient balance sheets and lower risk profiles with the 30 resilient stocks with low risk scores.
- When you want exposure to sturdier finances without sacrificing growth potential, start with the list of solid balance sheet and fundamentals (23 results) to narrow in on companies combining sound leverage and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com