


EN
Incyte (INCY) Expands Beyond JAKAFI, Is The Stock Still Cheap?
Incyte (INCY) just paired its push beyond JAKAFI with fresh news in colorectal cancer. A new phase II collaboration with Natera centers on INCA33890 and MRD-guided patient selection using Signatera.
Incyte’s recent earnings update, guidance raise for 2026 and conference appearance have landed alongside this Natera tie-up, and the stock’s momentum has been building, with a 12.57% 1 month share price return and a 3 year total shareholder return of 126.47% off a US$122.27 close.
Spot opportunities beyond Incyte by scanning a curated set of pharma and biotech names with strong momentum and robust finances through the list of solid balance sheet and fundamentals (23 results).After a sharp move in Incyte following guidance tweaks and fresh pipeline headlines, the question now is whether to lean into the momentum or wait for a cooler entry as valuation gets unpacked next.
Most Popular Narrative: 6.7% Undervalued
Incyte’s analyst consensus Narrative on Simply Wall St puts fair value at $131.08, a touch above the recent $122.27 close, and anchors that view on how the pipeline can offset a guided revenue decline and margin reset over the next few years.
The upcoming launches and label expansions of therapies like Opzelura, povorcitinib and Niktimvo in indications such as atopic dermatitis, vitiligo, hidradenitis suppurativa and GVHD remain a key driver for Incyte. Updated 2026 guidance points to higher total net sales of US$5.13 to 5.26b and Opzelura net sales of US$1.05 to 1.10b, which helps frame expectations for future revenue and earnings.
See why 61 investors see Incyte as 7% undervalued.
Analysts feeding into that Narrative are using a 7.42% discount rate. They pair a forecast 3.3% annual revenue decline and a move from a 6.7% net margin today toward 14.3% by 2029 with a future P/E of 47.8x on projected earnings of $775.4m. For this view to hold, investors would need to accept that a higher multiple than the 19.2x currently used for the US Biotechs industry can be supported by execution in non Jakafi assets, even as reported net income growth and one off items have created a noisy recent profit picture.
Result: Fair Value of $131.08 (UNDERVALUED)
Still, Incyte faces two clear pressure points: potential setbacks in key GI oncology and MPN trials, and heavier R&D spend that could squeeze future profitability.
Find out about the key risks to this Incyte narrative.
Another View: Incyte Looks Expensive On Earnings
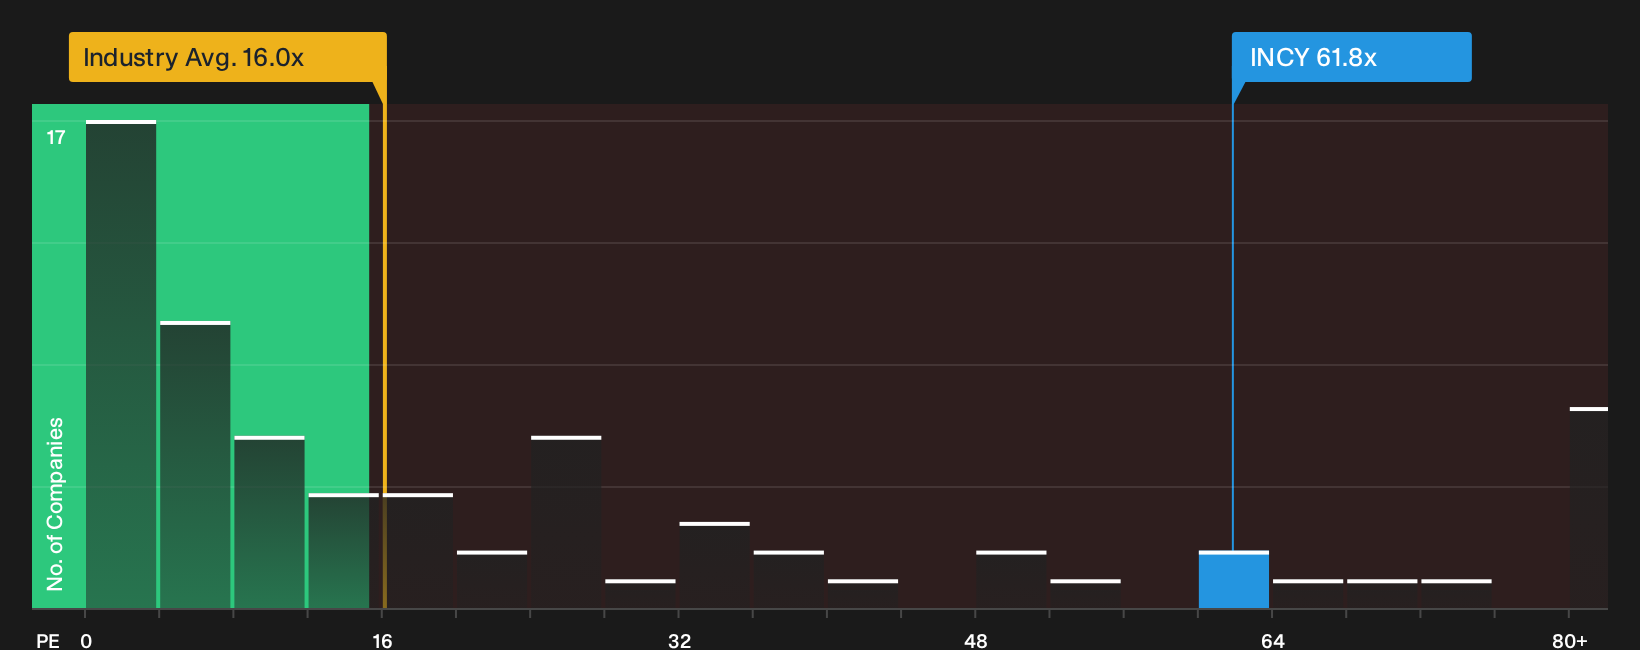
While the analyst Narrative leans on a fair value of $131.08, Incyte screens very differently on simple earnings maths. The stock trades on a P/E of 61.8x versus 16x for the wider US Biotechs industry and 18.3x across direct peers, while the fair ratio sits at 25.1x. That is a wide gap for anyone who worries about multiple compression if sentiment cools.
For investors who prefer to anchor decisions on earnings based markers rather than long dated forecasts, this contrast raises a straightforward question: Is the current premium P/E a price you are comfortable paying for the portfolio risk that still needs to play out, or would you prefer the market to move closer to that fair ratio before acting?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Incyte can feel messy, so move quickly, inspect the full dataset, and weigh both sides through the 2 key rewards and 3 important warning signs
Looking for more ideas beyond Incyte?
Once you have a view on Incyte, widen the lens and use screeners to spot other setups that match your risk tolerance and return goals.
- Explore potential mispricing by scanning a curated pool of quality stocks that trade below their implied worth through the 32 high quality undervalued stocks.
- Find income ideas by focusing on companies that pair higher yields with sturdier cash flows using the 6 dividend fortresses.
- Manage portfolio risk by filtering for businesses with resilient balance sheets and stronger fundamentals via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com