


EN
NeoGenomics (NEO) Stock Looks Overvalued Despite Its 68% One Year Run
NeoGenomics has delivered a 68.3% return over the past year, which naturally puts a spotlight on whether the current share price lines up with the sales the business is generating. With that kind of move on the board, the question for you is how much revenue power the market is now baking into the stock.
- Over the last 12 months, NeoGenomics has gained 68.3%, so any fresh money going in today is effectively paying a very different sales tag than a year ago.
- The group relies on converting its cancer diagnostics demand into consistent revenue growth and healthy gross margins, which can shape how much investors are willing to pay for each dollar of sales.
- There is a second opinion on NeoGenomics worth weighing. See what analysts think NeoGenomics's shares could be worth.
The issue now is whether NeoGenomics' current share price is justified by its sales when judged against the Fair Ratio benchmark.
If you want a quick sense check on NeoGenomics' sales driven story, lining it up against 32 high quality undervalued stocks can help you see how other businesses with similar quality filters are currently priced.
Does NeoGenomics Look Pricey on Sales?
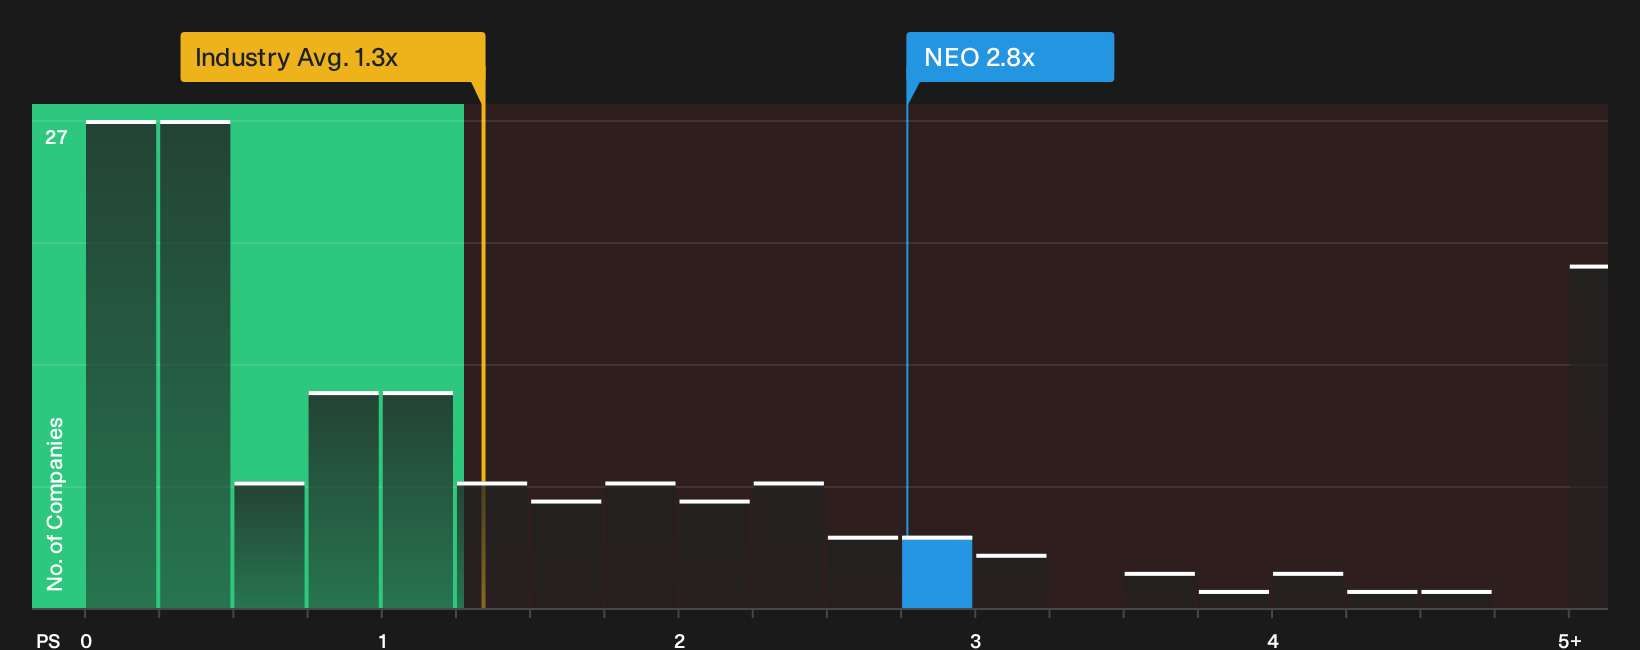
The P/S ratio tends to suit NeoGenomics because the market is clearly focused on what its cancer testing franchise can generate in sales rather than current profits. NeoGenomics trades on a P/S of 2.8x, which is above both the broader Healthcare sector on 1.3x and the closer peer group at about 1.3x as well.
The Fair Ratio, which adjusts for NeoGenomics' own mix of growth prospects, margins, size and risk, sits below the current P/S level. That gap means the shares screen as overvalued on this sales based lens, so you would need strong conviction in the quality and durability of future revenue to be comfortable paying this kind of premium multiple. Explore the numbers behind NeoGenomics's P/S valuation.
The NeoGenomics Narrative: What Would Justify Today's Price?
Narratives for NeoGenomics on Simply Wall St pick up where this valuation puzzle leaves off and explain what kind of growth, margins and earnings outcomes would need to occur for the stock to be worth materially more or less than today’s price, based on a range of clearly stated views from the Community page. Rather than relying on a single ratio or model, each narrative lays out the assumptions behind its fair value so you can compare them with future results as they arrive.
One of the top narratives on NeoGenomics: 26% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Investments in new digital pathology capabilities, automation, and the integration of a unified LIMS are expected to generate material operating efficiencies and enable greater operating leverage."
Discover why this Narrative puts NeoGenomics at 26% undervalued.
NeoGenomics' valuation still leaves one crucial angle unanswered
Price tags on future sales only tell part of the story, because the people setting priorities, taking risks and approving budgets can tilt outcomes in ways the ratio cannot capture. See who runs NeoGenomics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com