


EN
Did Record 2027 Bookings Just Shift Carnival (CCL) Investment Narrative?
- Carnival, through its Cunard brand, has outlined a detailed refurbishment plan for Queen Mary 2, including new Grill Suites, upgraded wellness facilities and refreshed interiors that pay tribute to the original 1936 liner, ahead of the ship’s scheduled return to service in May 2027.
- Alongside this design overhaul, Carnival is emphasizing higher yield opportunities through premium accommodations, strong 2027 bookings and lower fuel costs, while continuing to pay down debt and refine fleet deployment.
- This article examines how Carnival's investment narrative is influenced by record 2027 bookings and the focus on higher yielding premium products.
Scan beyond Carnival and see how other travel and leisure stocks with pricing power and premium offerings stack up in our hand-picked 32 high quality undervalued stocks.
Carnival Investment Narrative Recap
Carnival shareholders need to believe that a relatively fixed fleet can still drive higher earnings through pricing, onboard spending and cost discipline rather than big capacity additions. According to fabien_levoyageur, an investor in the Simply Wall St Community, the cruise group already benefits from scale and a broad brand portfolio, but still carries meaningful debt. The key short term catalyst is how booked occupancy and pricing for 2027 translate into cash generation that can further strengthen the balance sheet.
Fuel costs and leverage remain the biggest swing factors. Recent easing in oil prices and continued debt repayment reduce pressure, yet high borrowings and insider selling keep financing risk on the table. The Cunard refurbishment news does not fundamentally change those near term drivers. It mainly supports Carnival's premium mix story rather than altering the core risk profile.
The Queen Mary 2 refurbishment is the clearest operational tie in here. Cunard is leaning into heritage rich, premium cabins and wellness spaces that align with Carnival's push toward higher yielding products and more profitable guests per berth. With capacity growth around 0.5% in 2027, any uplift in Grill Suites pricing or onboard spend matters more than simply adding ships.
For catalysts, that premium tilt sits alongside Celebration Key and other destination projects that can channel guests toward higher margin experiences. The main risk is execution, since design heavy projects must land on time and on budget to avoid squeezing returns. This is particularly important while Carnival still manages a high debt load and an unstable dividend track record highlighted by fabien_levoyageur.
On these figures, the narrative from fabien_levoyageur reaches a fair value of US$35.00 by applying a discounted cash flow style approach. It compounds 26.1% annual revenue growth toward an 11.2% future profit margin, then capitalizes those projected earnings into a single per share estimate.
Uncover why Carnival's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
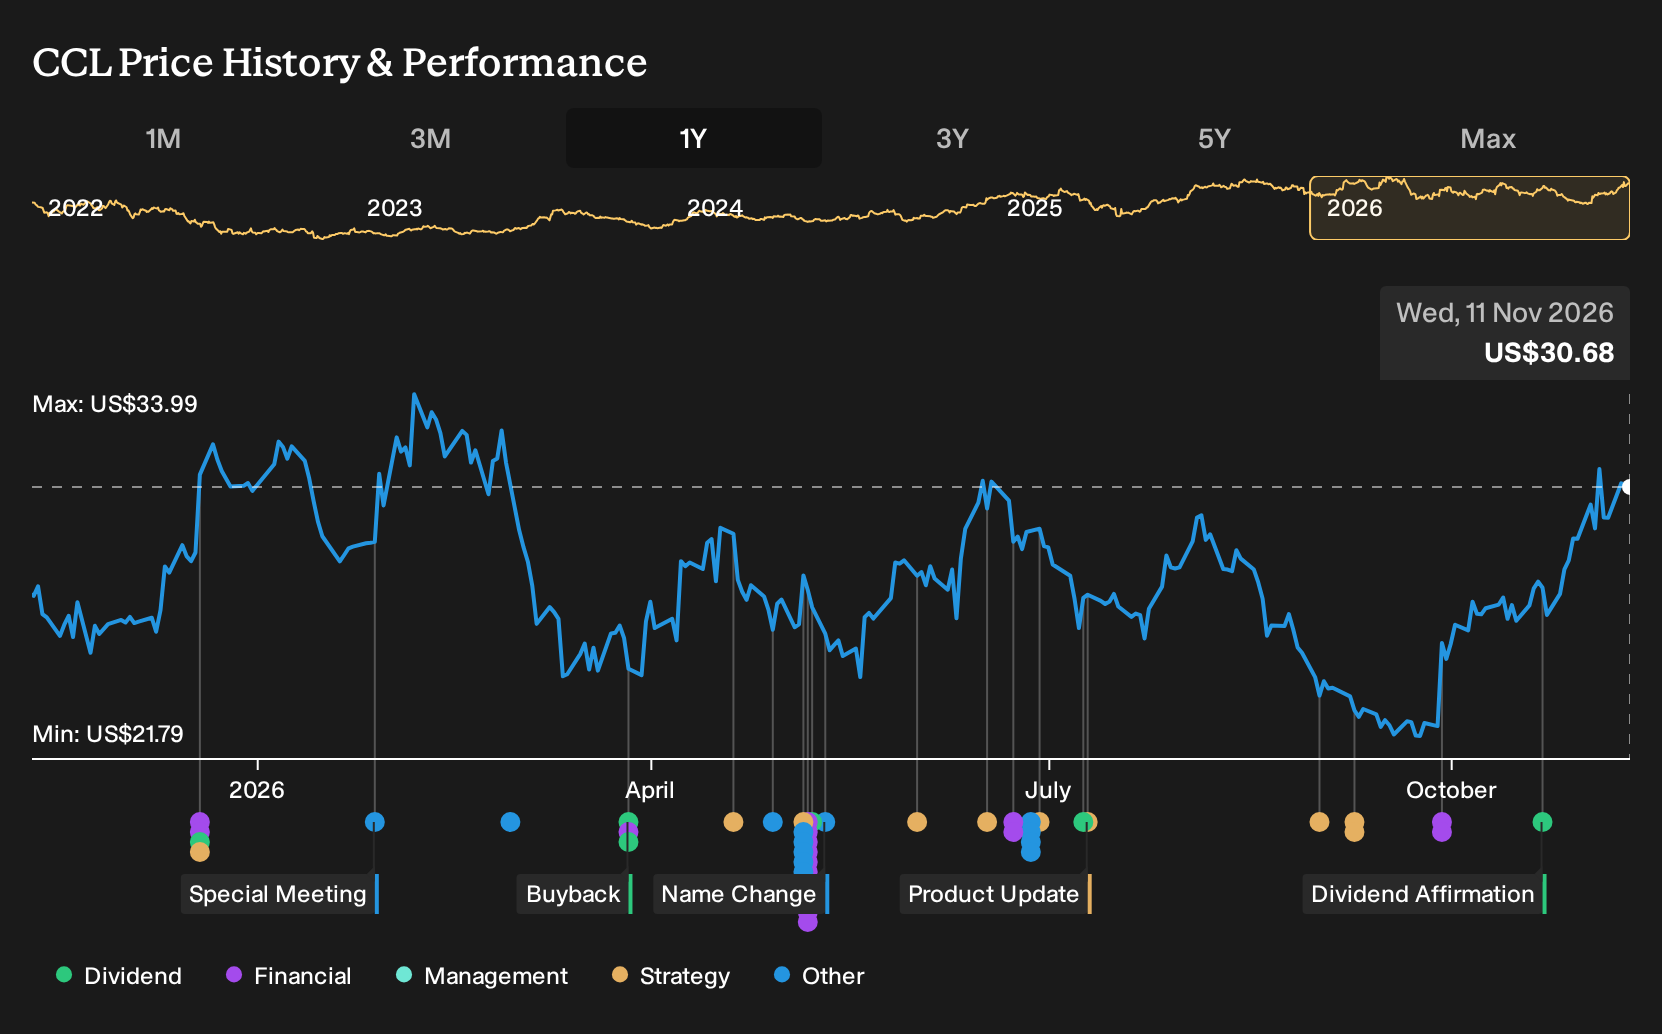
Exploring Other Perspectives
For contrast, focus on the bullish catalyst around earnings power. The most optimistic analysts were already pencilling in revenue of US$31.0b and earnings of US$4.8b by about 2029 for Carnival, based on stronger margins. They had not seen the Queen Mary 2 refurbishment plans yet, so their story could still shift.
Explore 5 other Carnival fair value estimates, including one that suggests as much as 49% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Carnival research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Carnival. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carnival's overall financial health at a glance.
Looking for more Carnival sized investment ideas?
Carnival is only one way to back pricing power and strong balance sheets in travel and leisure. If you want to stress test your thesis and widen your opportunity set, the Simply Wall St Screener can help you sift through other listed businesses using the same lens of quality, resilience and value.
Here are a few starting points that can surface very different types of opportunities depending on the kind of portfolio you want to build:
- If stability matters more than excitement, filter for resilient businesses using our low volatility and financial risk criteria with the 30 resilient stocks with low risk scores.
- For investors who care about robust finances before anything else, scan companies with strong cash buffers and moderate leverage through the list of solid balance sheet and fundamentals (23 results).
- If the goal is to find potential mispricings, search for quality firms trading below intrinsic value estimates using the 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com