


EN
How Earnings Low Point Will Impact Mosaic Stock
- Mosaic reported third quarter 2026 sales of US$3,100.6 million and a net loss of US$72.1 million, compared with net income a year earlier, alongside a loss for the first nine months of the year.
- The swing from profit to loss, driven in part by higher sulfur and ammonia costs and phosphate production curtailments, highlights how Mosaic's earnings profile currently leans heavily on cost control and asset mix rather than volume alone.
- We will now look at how Mosaic's investment narrative may shift given management's view that current earnings represent a low point.
Mosaic Investment Narrative Recap
For a shareholder in Mosaic, the core belief is that the fertilizer cycle and the business mix eventually offset the current earnings slump. Phosphates are under pressure from sulfur constraints and idle plants, while potash is still a key cash generator. The third quarter loss and year to date net loss keep the focus on how quickly operations can move back toward normal sulfur supply and more efficient use of existing assets.
The analyst consensus Narrative on Simply Wall St leans heavily on Mosaic reshaping its portfolio toward higher margin lines like Mosaic Biosciences while keeping debt, dividends and capital spending in balance. The most important near term catalyst is a reduction in raw material pressure, especially sulfur. Management’s view that earnings are near a low point therefore carries significant weight. The biggest risk right now is that cash flow stays tight, which could limit how fast the portfolio reshuffle and cost cuts translate into more resilient profitability.
The third quarter 2026 update is the key reference point here. Mosaic reported sales of US$3,100.6 million and a net loss of US$72.1 million for the quarter, with a net loss of US$602.5 million over the first nine months. Earnings per share swung from US$1.29 diluted earnings in the prior year quarter to a diluted loss of US$0.23, which keeps the balance sheet and dividend coverage under the microscope for now.
That setback links directly to the catalysts and risks in the analyst consensus Narrative on Simply Wall St. The thesis around global phosphate underapplication and higher margin products still hinges on Mosaic having enough financial headroom to run through this trough. With debt and the dividend described as not well covered by operating cash flow, the recent loss makes execution on cost cuts, working capital release and capital reallocation even more critical to the story investors are weighing today.
Mosaic's narrative projects US$13.1b revenue and US$674.0 million earnings by 2029. This assumes 2.4% yearly revenue growth and an earnings increase of about US$1.3b from current earnings of a US$638.5 million loss.
Uncover why Mosaic's fair value indicates a 14% potential upside to its current price that could narrow quickly.
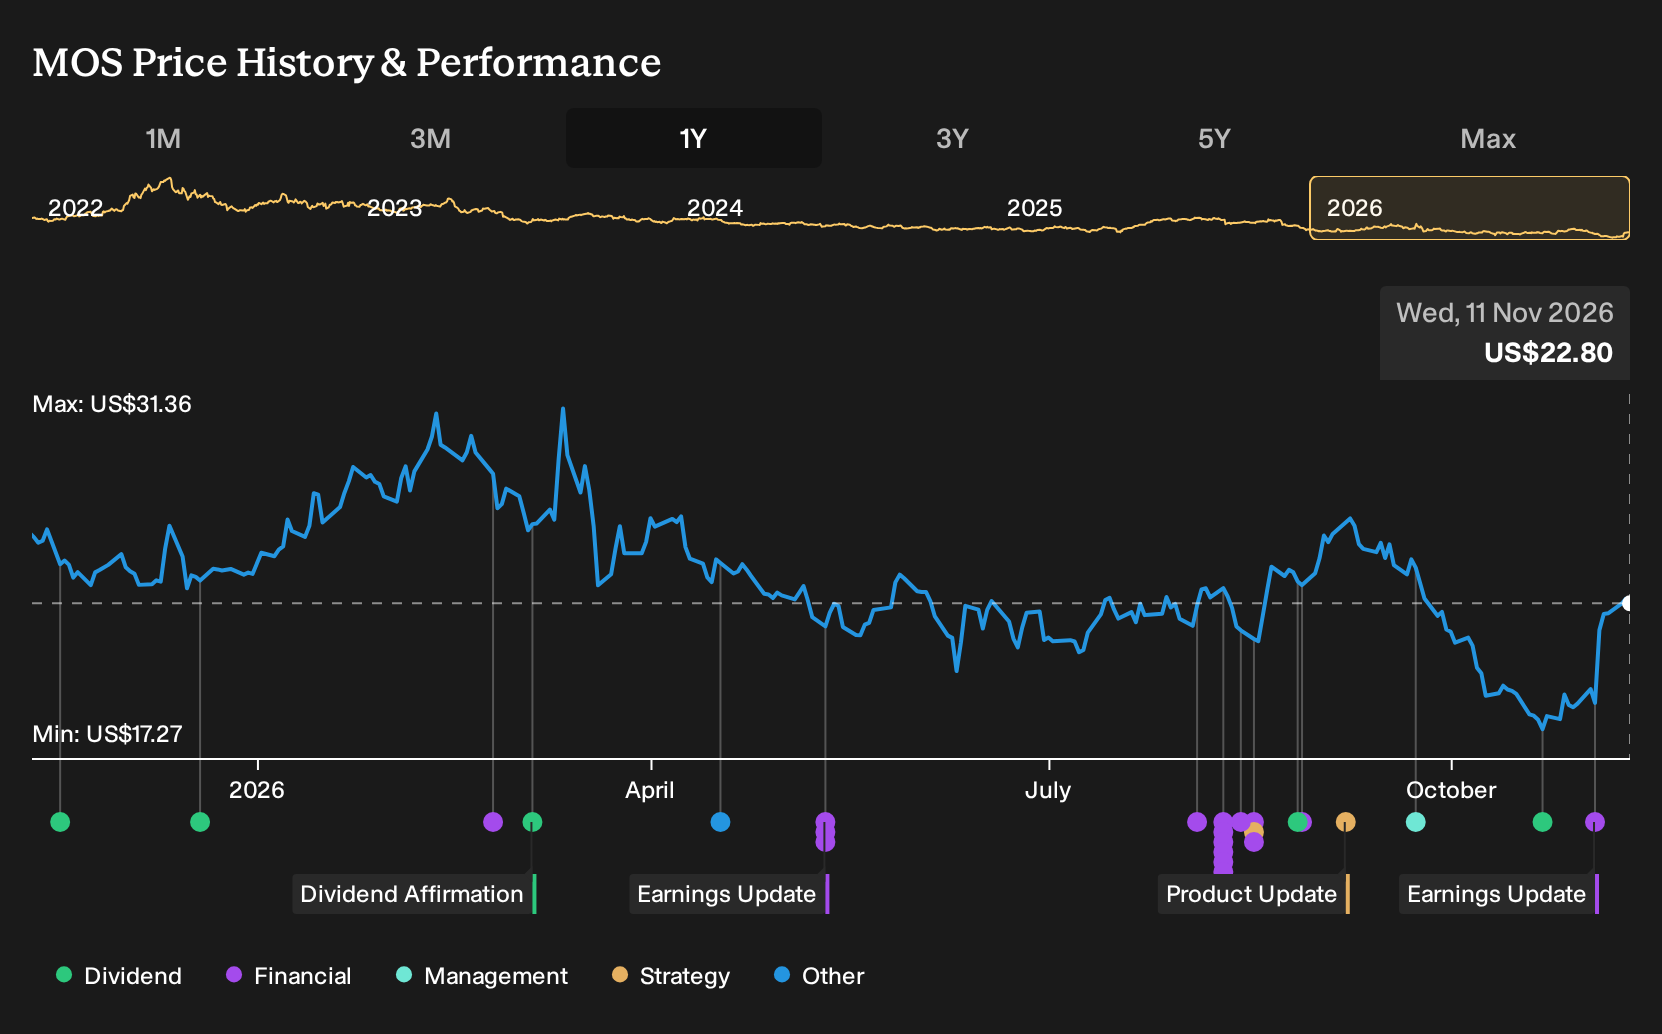
Exploring Other Perspectives
Some of the most optimistic analysts view Mosaic’s working capital release as a key catalyst. They were looking for revenue to reach about US$16.0b and earnings of roughly US$1.6b by 2029, compared with the consensus US$13.1b and US$674.0 million. The fresh quarterly loss may push those forecasts and opinions further apart.
Explore 4 other Mosaic fair value estimates, including one that suggests as much as 37% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mosaic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mosaic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mosaic's overall financial health at a glance.
Looking for more investment ideas beyond Mosaic?
Once you have a view on Mosaic, it can help to compare it with other businesses that share some of the quality or risk traits you care about most. The Simply Wall St Screener is a quick way to do that without getting lost in thousands of tickers.
- If capital preservation is a priority, start with companies that screen for resilience and steadier risk profiles through the 30 resilient stocks with low risk scores.
- If you want income to play a bigger role in your portfolio, look at businesses offering stronger yields and payout potential using the 6 dividend fortresses.
- If balance sheet strength matters most to you, focus on companies that pair solid finances with consistent fundamentals via the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com