


EN
S&P Index Addition Might Change The Case For Investing In McGrath RentCorp (MGRC)
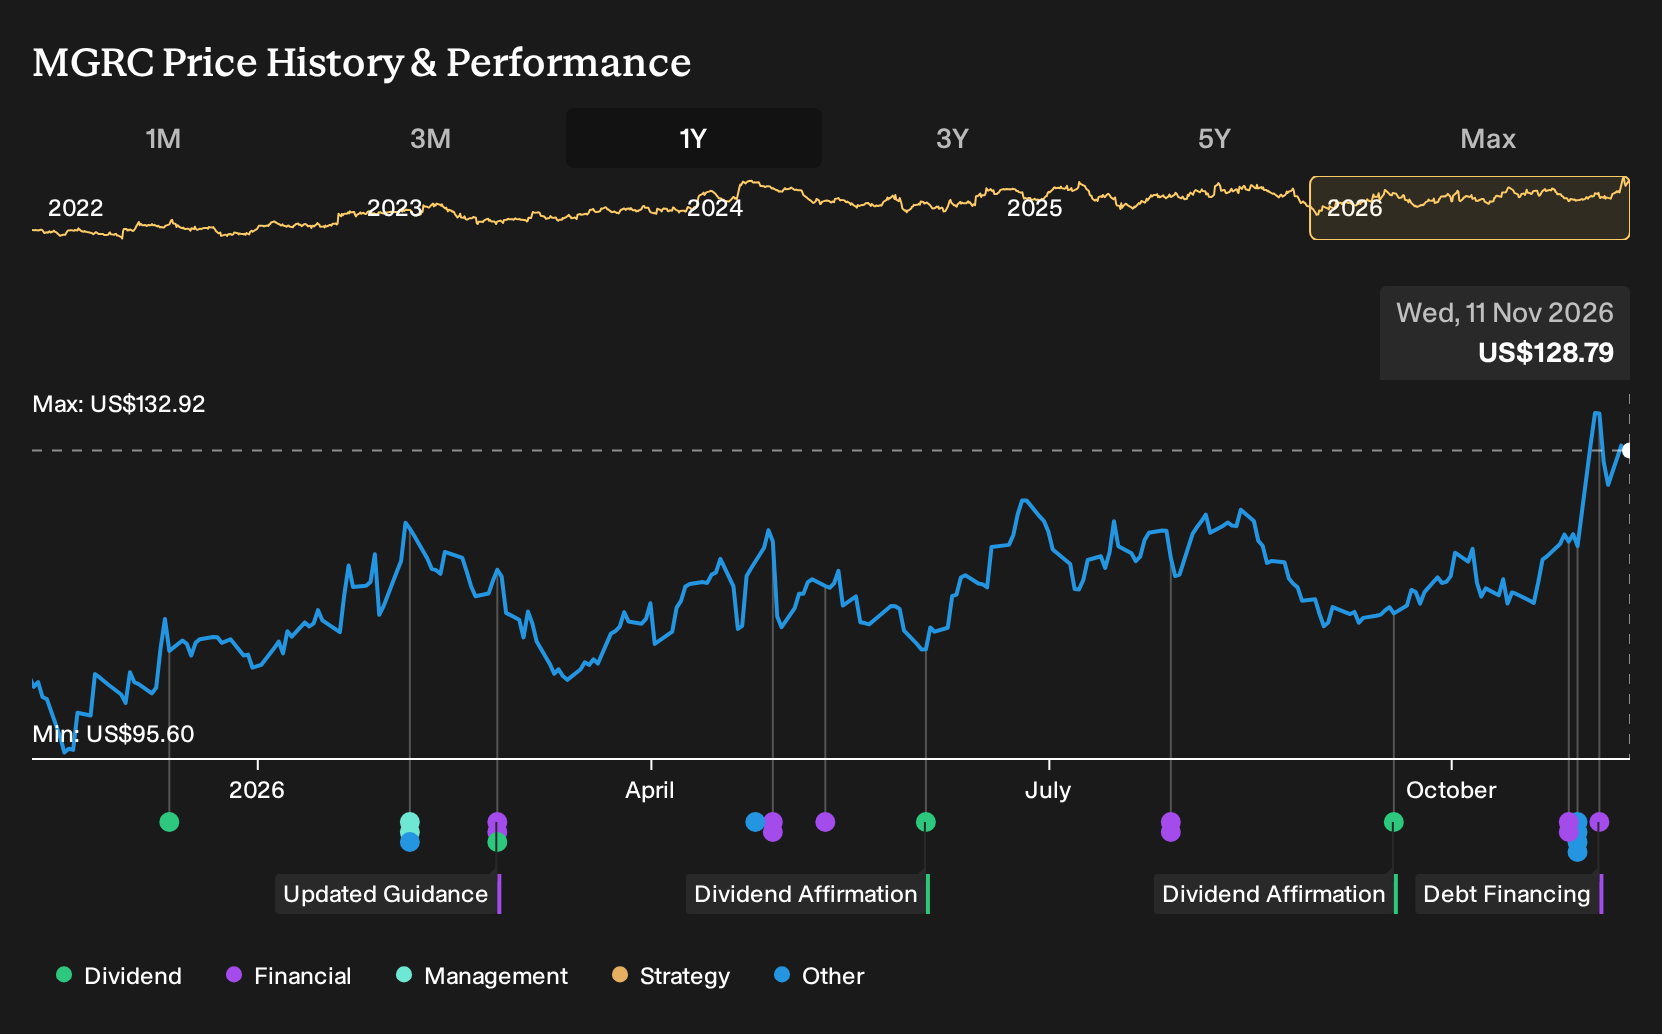
- McGrath RentCorp entered into an amended note purchase agreement and on 2 November 2026 issued US$75 million of unsecured 6.53% Series H Senior Notes maturing in 2031. The company also expanded its revolving private shelf facility to US$350 million and updated covenant thresholds.
- The company’s inclusion in multiple S&P indices, including the S&P 600 and S&P Composite 1500, may broaden its investor base as index trackers and institutional portfolios adjust to the new benchmark constituents.
- We will now look at how McGrath RentCorp’s index inclusion and stronger funding flexibility interact with the existing investment narrative.
Scan how McGrath RentCorp’s index inclusion and fresh funding compare with other potential opportunities by reviewing it alongside our hand picked 30 resilient stocks with low risk scores.
McGrath RentCorp Investment Narrative Recap
To own McGrath RentCorp, you need to be comfortable with a rental-led story in which Mobile Modular and TRS RenTelco keep doing the heavy lifting, while Portable Storage and Enviroplex stay weaker. The analyst consensus narrative on Simply Wall St focuses on continued equipment investment and geographic expansion. The fresh US$75 million of 6.53% Series H Notes and expanded shelf capacity support that funding path.
The most important short-term swing factor is still utilization and pricing in core rental segments, not the new debt itself. The biggest risk remains softer demand in Portable Storage and Enviroplex, where flat revenue and weaker EBITDA have already been flagged. The financing update mainly refines flexibility rather than changing those underlying demand questions.
The index additions to the S&P 600, S&P 1000 and S&P Composite 1500 look most relevant for how this new debt capital is interpreted. Inclusion can bring McGrath RentCorp into more portfolios that track those benchmarks. That can affect liquidity and ownership mix around the same time the balance sheet structure is evolving.
For catalysts, the story still centers on whether Mobile Modular bookings growth, TRS RenTelco utilization at 68.9% and higher capital expenditure in 2026 translate into sustained rental earnings. The recent credit facility expansion to US$725 million and now the Series H issuance give management more room to fund that plan, while higher debt and covenant thresholds keep leverage discipline firmly in focus.
McGrath RentCorp’s narrative projects US$1.1b revenue and US$192.0 million earnings by 2029, based on analysts’ estimates. That path assumes revenue grows at 5.1% per year and earnings rise by about US$39.2 million from US$152.8 million today.
Uncover how McGrath RentCorp's fair value indicates a 13% potential upside to its current price, which could narrow quickly if sentiment around the rental story improves.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range from US$56.01 to US$145.40, showing how far apart retail views on McGrath RentCorp can be. Some community members may lean on Mobile Modular and TRS RenTelco growth catalysts, while others focus on ongoing Portable Storage and Enviroplex weaknesses. Explore those contrasting viewpoints directly.
Explore another McGrath RentCorp fair value estimate, including one that suggests as much as 13% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your McGrath RentCorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for McGrath RentCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McGrath RentCorp's overall financial health at a glance.
Looking For More McGrath RentCorp-Like Investment Ideas?
Once you have formed a view on McGrath RentCorp, it can help to compare that thesis with other opportunities that share similar qualities, whether that is balance sheet strength, income potential, or mispricing based on fundamentals.
- If capital protection and a smoother ride appeal to you, start by scanning a curated set of 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- If income is your priority, use our screener featuring 6 dividend fortresses to focus on companies offering higher yields with an emphasis on durability.
- If you prefer to hunt for mispriced quality, broaden your search with a hand picked collection of 19 high quality undiscovered gems that pair solid fundamentals with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com