


EN
First Bank Of Toyama (TSE:7184) Looks Fully Priced On Raised Profit And Dividend Guidance
First Bank Of Toyama (TSE:7184) reset investor expectations after raising both earnings forecasts and dividend guidance for the fiscal year to March 31, 2027, directly linking its payout plans to the updated profit projections.
The raised earnings and dividend forecasts dropped into a market that had already re-rated First Bank Of Toyama sharply higher this year. The share price is still up 69.77% year to date despite a 13.53% decline over the past month and a 102.06% total shareholder return over the last 12 months, pointing to strong longer term momentum even as near term sentiment cools around the latest announcement.
Spot similar bank stories gaining traction by scanning our hand picked list of 20 high quality undervalued stocks, which combines upgraded outlooks with recalibrated market expectations.That surge in First Bank Of Toyama, followed by the recent pullback, leaves a simple tension: Is most of the easy upside already spent, or do the new earnings and dividend forecasts still leave meaningful value on the table?
Preferred P/E of 11.3x: Is it justified?
Valuation on First Bank Of Toyama now leans on a simple question for investors. A P/E of 11.3x sits below both the broader JP market on 13.2x and the domestic banks group at 13.9x, even after a strong share price run into ¥3,100.
The P/E multiple tracks how much the market is willing to pay today for each unit of current earnings. For a regional lender like First Bank Of Toyama, which reports high quality earnings and a net profit margin of 30.2%, that metric gives a quick read on how the market prices its profitability against local peers.
Strong historic earnings momentum adds another piece to the picture. Profit expanded by 64.6% over the past year compared to a 5 year average of 34.6% per year, and that recent growth rate also exceeded the wider banks industry figure of 41.5%. With that backdrop, an 11.3x P/E that screens cheaper than both the JP market and JP banks group indicates that investors are still assigning a lower tag to each yen of earnings relative to peers.
Compared with the sector, the discount is clear. The stock trades on 11.3x earnings where the JP banks industry sits on 13.9x. This indicates the market is valuing the bank at a meaningfully lower multiple than the typical domestic lender, even after the recent rally and pullback.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 11.3x (UNDERVALUED)
Still, the recent share price pullback and a relatively low value score of 2 remind you that sentiment can cool quickly if earnings or dividend plans disappoint.
Find out about the key risks to this First Bank Of Toyama narrative.
Another view on First Bank Of Toyama’s value
The SWS DCF model paints a cooler picture of First Bank Of Toyama. On that framework, the estimated future cash flow value is ¥2,744.77 per share, while the market price sits at ¥3,100. In simple terms, the stock screens as overvalued on this cash flow lens. So which signal would you trust more: the earnings multiple or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
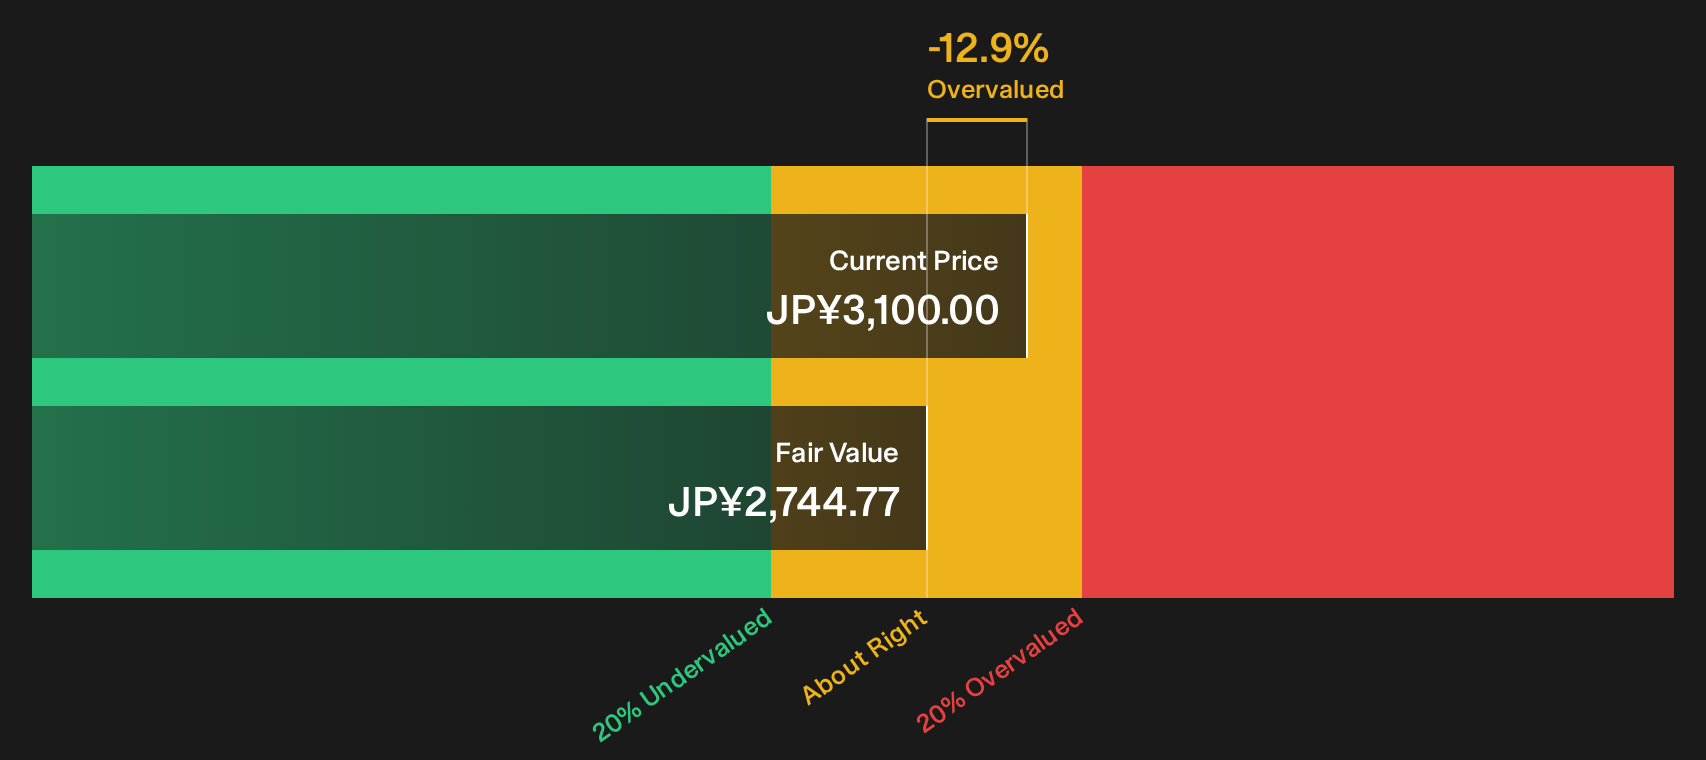
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Bank Of Toyama for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 20 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this combination of upbeat earnings signals and a cooler cash flow view leaves you undecided, act promptly and test the numbers against your own framework. Use our breakdown of 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond First Bank Of Toyama?
Do not stop with First Bank Of Toyama. Broaden your watchlist with fresh ideas sourced from data driven screeners that highlight different strengths and risk profiles.
- Target potential mispricings by scanning a curated set of high quality value opportunities through the 20 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that combine substantial yields with staying power using the 26 dividend fortresses.
- Dial down volatility risk by filtering for companies that score well on resilience through the 19 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com