


EN
TriMas (TRS) Could Be 15% Undervalued Following Its Delayed 10 Q Filing
TriMas (TRS) told investors on 10 November 2026 that it will not file its upcoming 10-Q by the SEC deadline, shortly after releasing third quarter earnings and fresh full year guidance.
TriMas shares closed at $38.08 on 11 November, with a 1-year total shareholder return of 20.53% and a 3-year total shareholder return of 56.97%. This points to solid longer term wealth creation, even though the year-to-date share price return of 4.93% and recent 7-day decline of 3.35% suggest momentum has cooled as investors reassess the filing delay in light of October's earnings beat and updated full year guidance.
Spot potential peers to TriMas facing similar filing or sentiment shifts by scanning our hand picked 30 resilient stocks with low risk scores, which still pair resilient balance sheets with more predictable fundamentals.TriMas now trades below the average analyst target and below some intrinsic value estimates after the filing delay headline. Is that discount justified by risk, or has the pendulum swung too far for this stock?
Most Popular Narrative: 15% Undervalued
On the Simply Wall St analyst consensus Narrative, TriMas is priced below an implied fair value of $45, compared with the recent $38.08 close, which frames the filing delay against a thesis built on post Aerospace cash deployment and cost cuts.
The main thing that has to go right is that TriMas successfully deploys its more than US$1.2b of Aerospace divestiture proceeds into disciplined M&A, share repurchases, and organic investments, while delivering the planned US$15 to 16m of annual cost savings and improved execution at Norris Cylinder.
See why 1 investors see TriMas as 15% undervalued.
Result: Fair Value of $45 (UNDERVALUED)
Still, the narrative around TriMas can unravel if sustainability rules hit key packaging formats harder than expected or if Norris Cylinder’s low margins prove stubborn.
Find out about the key risks to this TriMas narrative.
Another View: TriMas Through A Cash Flow Lens
The first take on TriMas relied on analyst earnings and multiples to argue for a $45 fair value. A second yardstick, the Simply Wall St DCF model, tells a very different story. On that framework, the stock price of $38.08 sits well above an estimated future cash flow value of $4.52, which points to a valuation that looks rich rather than cheap. Which lens do you trust more when cash generation and required returns start to pull in opposite directions?
For readers who want to see how this cash flow based result is constructed step by step, it is worth going straight to the source in the SWS DCF model, then testing how changes in margins, growth, or discount rate would shift the outcome. Look into how the SWS DCF model arrives at its fair value.
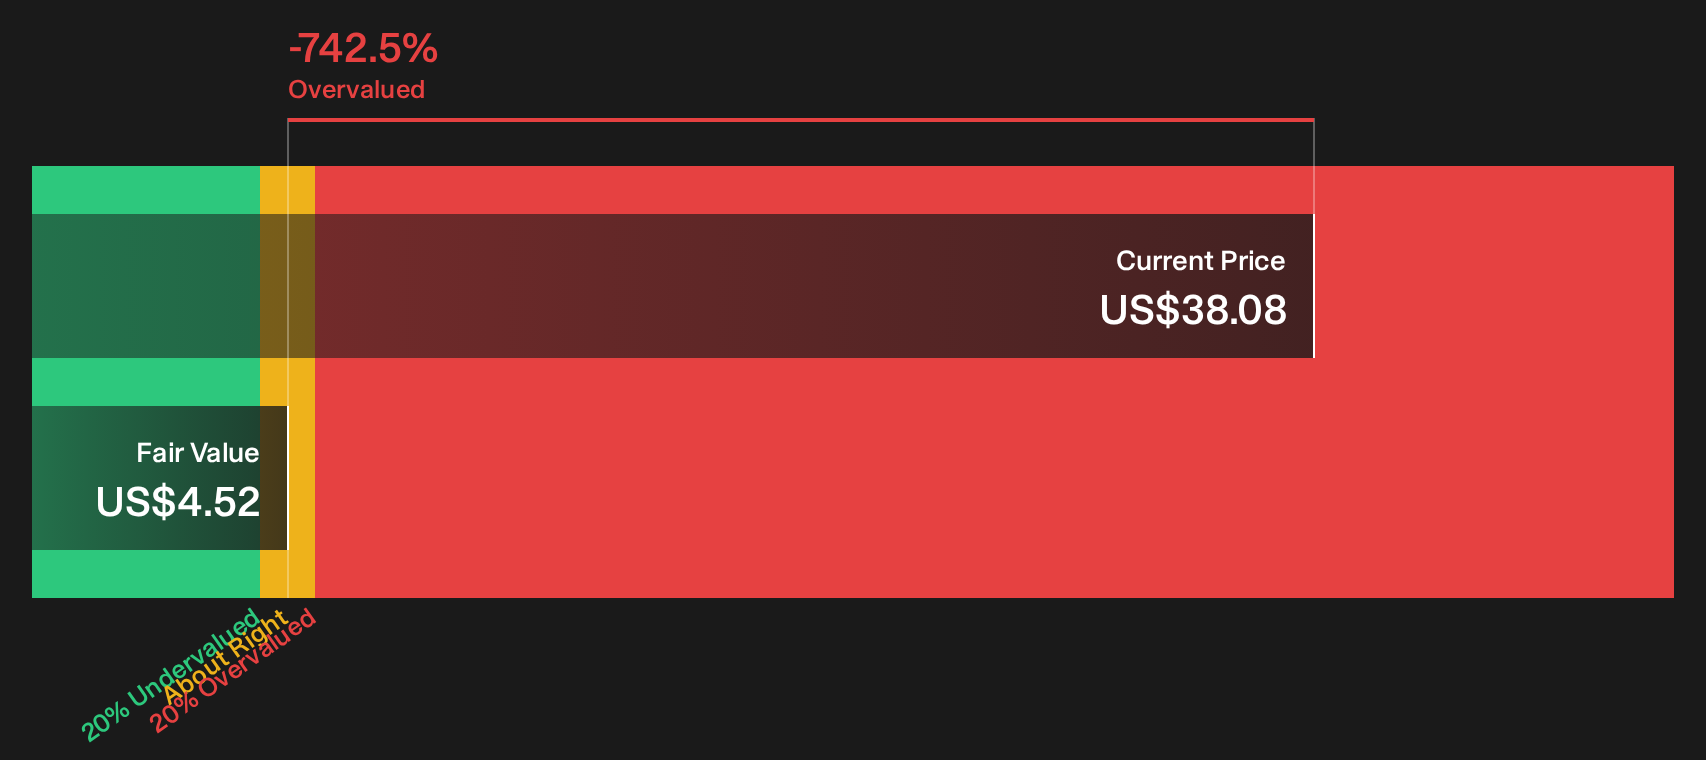
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TriMas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on TriMas valuation and risk can pull sentiment in opposite directions. Step into the numbers yourself, move quickly if needed, and weigh both the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TriMas?
If TriMas has sparked questions about valuation and risk, use that curiosity to widen your opportunity set with a few focused screens on Simply Wall St.
- Target resilient upside by scanning companies that pair strong fundamentals with dependable balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for price misalignments by checking the 32 high quality undervalued stocks that combine quality financials with discounts that might not last.
- Stack potential income on top of capital gains by reviewing the 6 dividend fortresses that focus on higher yielding payouts with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com